
You Added Your Kids to the House Deed to Avoid Probate.
Did You Just Create a Six-Figure Tax Problem?
Adding your children to your deed to skip probate feels free and smart. But it trades away the stepped-up basis your heirs would have gotten — and can bury them in capital-gains tax when the house sells. Here's the trap, the math, and how to avoid probate without it.
Here is where it bites, and it is almost never the person who signed the deed who feels it. It is a year after the funeral. Two adult kids are sitting at a title company in Kalispell, selling the family home they now own, and the closing agent slides a figure across the table: the capital-gains tax due on the sale. It is tens of thousands of dollars — sometimes more than a hundred thousand — on a house they always assumed would pass to them cleanly. Mom had added them to the deed years ago, on the advice of a well-meaning friend, specifically to keep things simple and “avoid probate.” It worked. It also quietly built a tax bill that probate never would have.
Adding your children to your house deed is one of the most common pieces of kitchen-table estate advice in America, and one of the most expensive. The move feels free and obvious. The cost is invisible — it hides inside two words most people have never heard, stepped-up basis — and it does not show up until the house is sold, long after the deed can be undone. Let's walk through exactly how a probate shortcut becomes a six-figure tax problem, and the ways to skip probate that don't. The basis and gift rules here are federal, so they work the same whether your house is in Montana, Texas, or Florida — we use Montana examples because it's our backyard, but swap in your own state and the math doesn't change.
By Jason Anderson
Co-Founder, 406 Consulting Group
Big-firm tax background with a Six Sigma discipline for systems and job costing.
This article is tax education, not legal advice; deed and estate decisions should be made with an estate attorney, and we are glad to run the tax numbers alongside them.
The Short Version
- When your kids inherit the house at your death, its tax “basis” resets to full market value — so they can sell it with little or no capital-gains tax.
- When you add them to the deed while you're alive, that share is a gift — and they take your old cost basis on it. The step-up is gone on that portion.
- The result can be tens of thousands to well over $100,000 in capital-gains tax on a sale that would otherwise have been nearly tax-free.
- You can avoid probate and keep the step-up — with a revocable living trust, a Montana transfer-on-death deed, or even a plain will. The deed shortcut is the one option that keeps the probate savings and throws away the tax break.
What We'll Cover
Two Ways a House Passes to Your Kids — and the IRS Treats Them Completely Differently
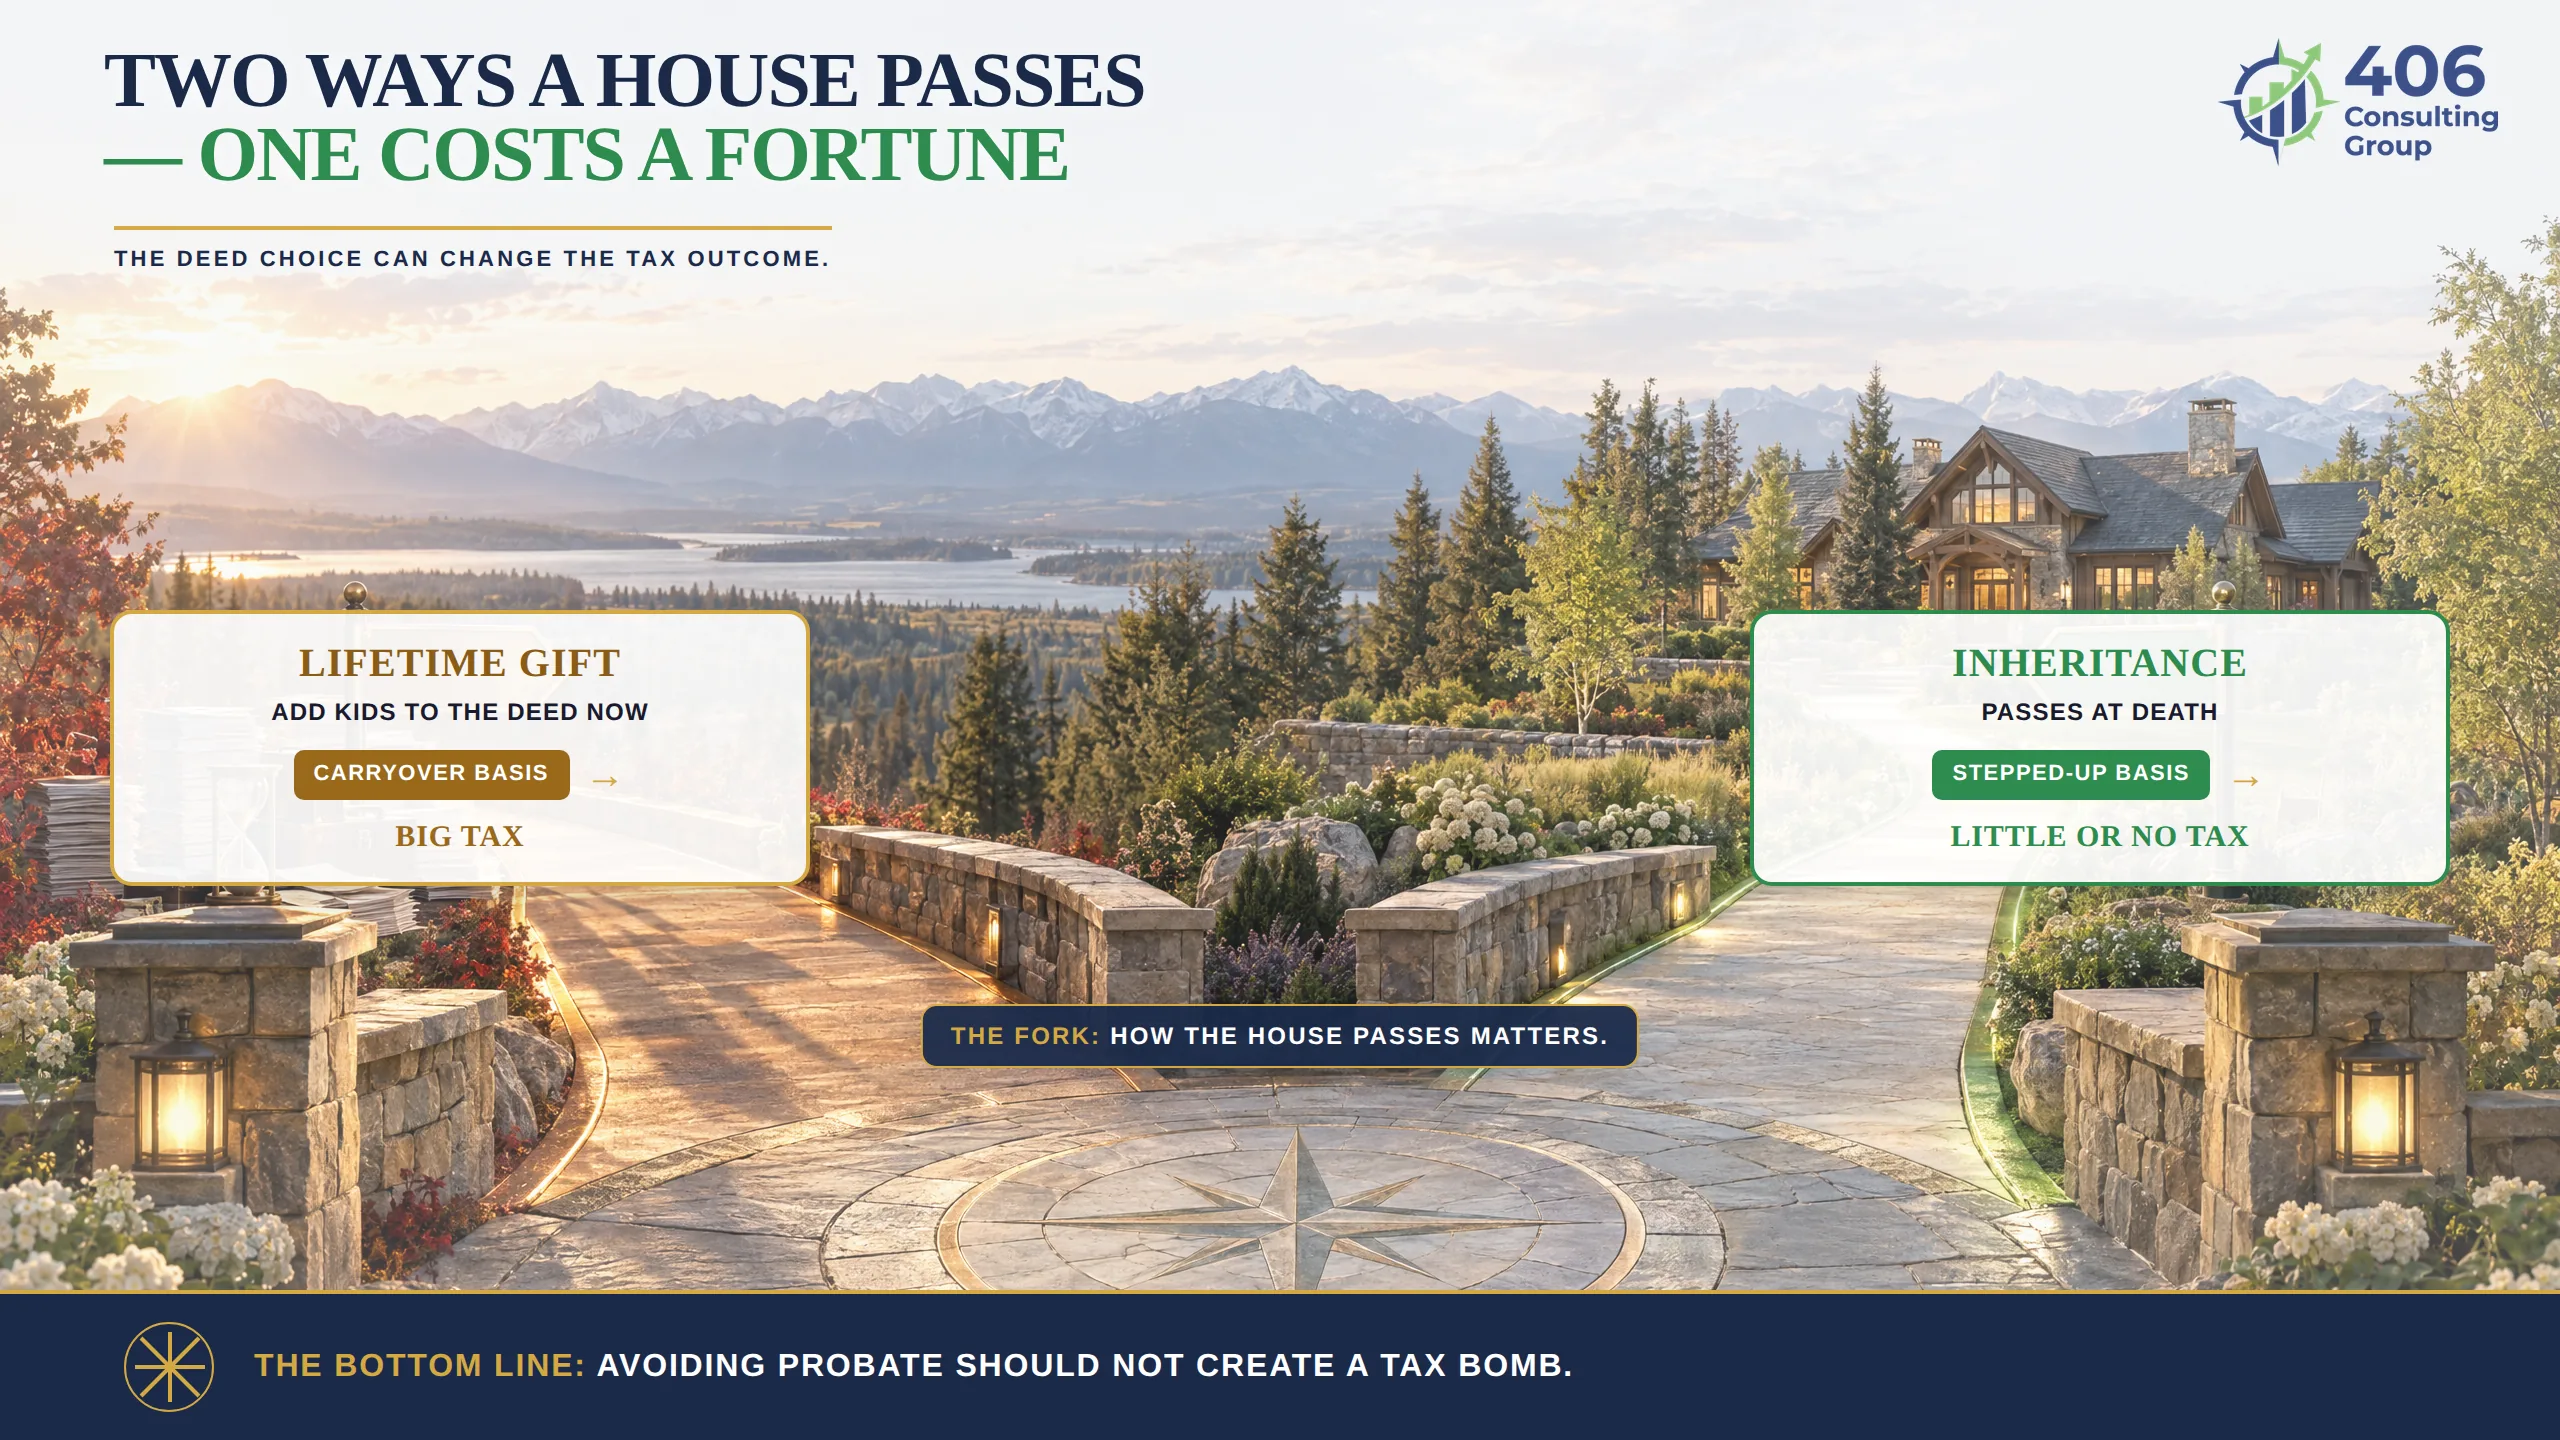
There are two fundamentally different ways to hand a house to the next generation, and the entire tax outcome turns on which one you pick. This is the fork in the road, and most people walk down the expensive side without ever seeing the sign.
Path A: They inherit it at your death
Through a will, a living trust, or a transfer-on-death deed, the house passes at death. The tax basis resets to market value. Capital-gains tax on a quick sale: usually near zero.
Path B: You add them to the deed now
You sign a new deed making the kids co-owners during your life. That share is a gift, and it carries your old basis forward. Capital-gains tax on a sale: potentially six figures.
Both avoid probate. Only one of them avoids the tax. To see why, you have to understand the single most valuable — and least understood — break in the tax code for families: the step-up.
Stepped-Up Basis: The Tax Break Most Families Don't Know They Have
“Basis” is just tax-speak for what you paid for something. When you sell, you pay capital-gains tax on the difference between the sale price and your basis. Buy a house for $95,000, sell it for $850,000, and you have a $755,000 gain the IRS wants a cut of.
But there is a quiet, powerful rule for inherited property (the tax code calls it Section 1014): when someone dies, the basis of what they owned resets to its fair market value on the date of death. The decades of appreciation that built up during their lifetime simply vanish for tax purposes. Your heirs start fresh at today's value.
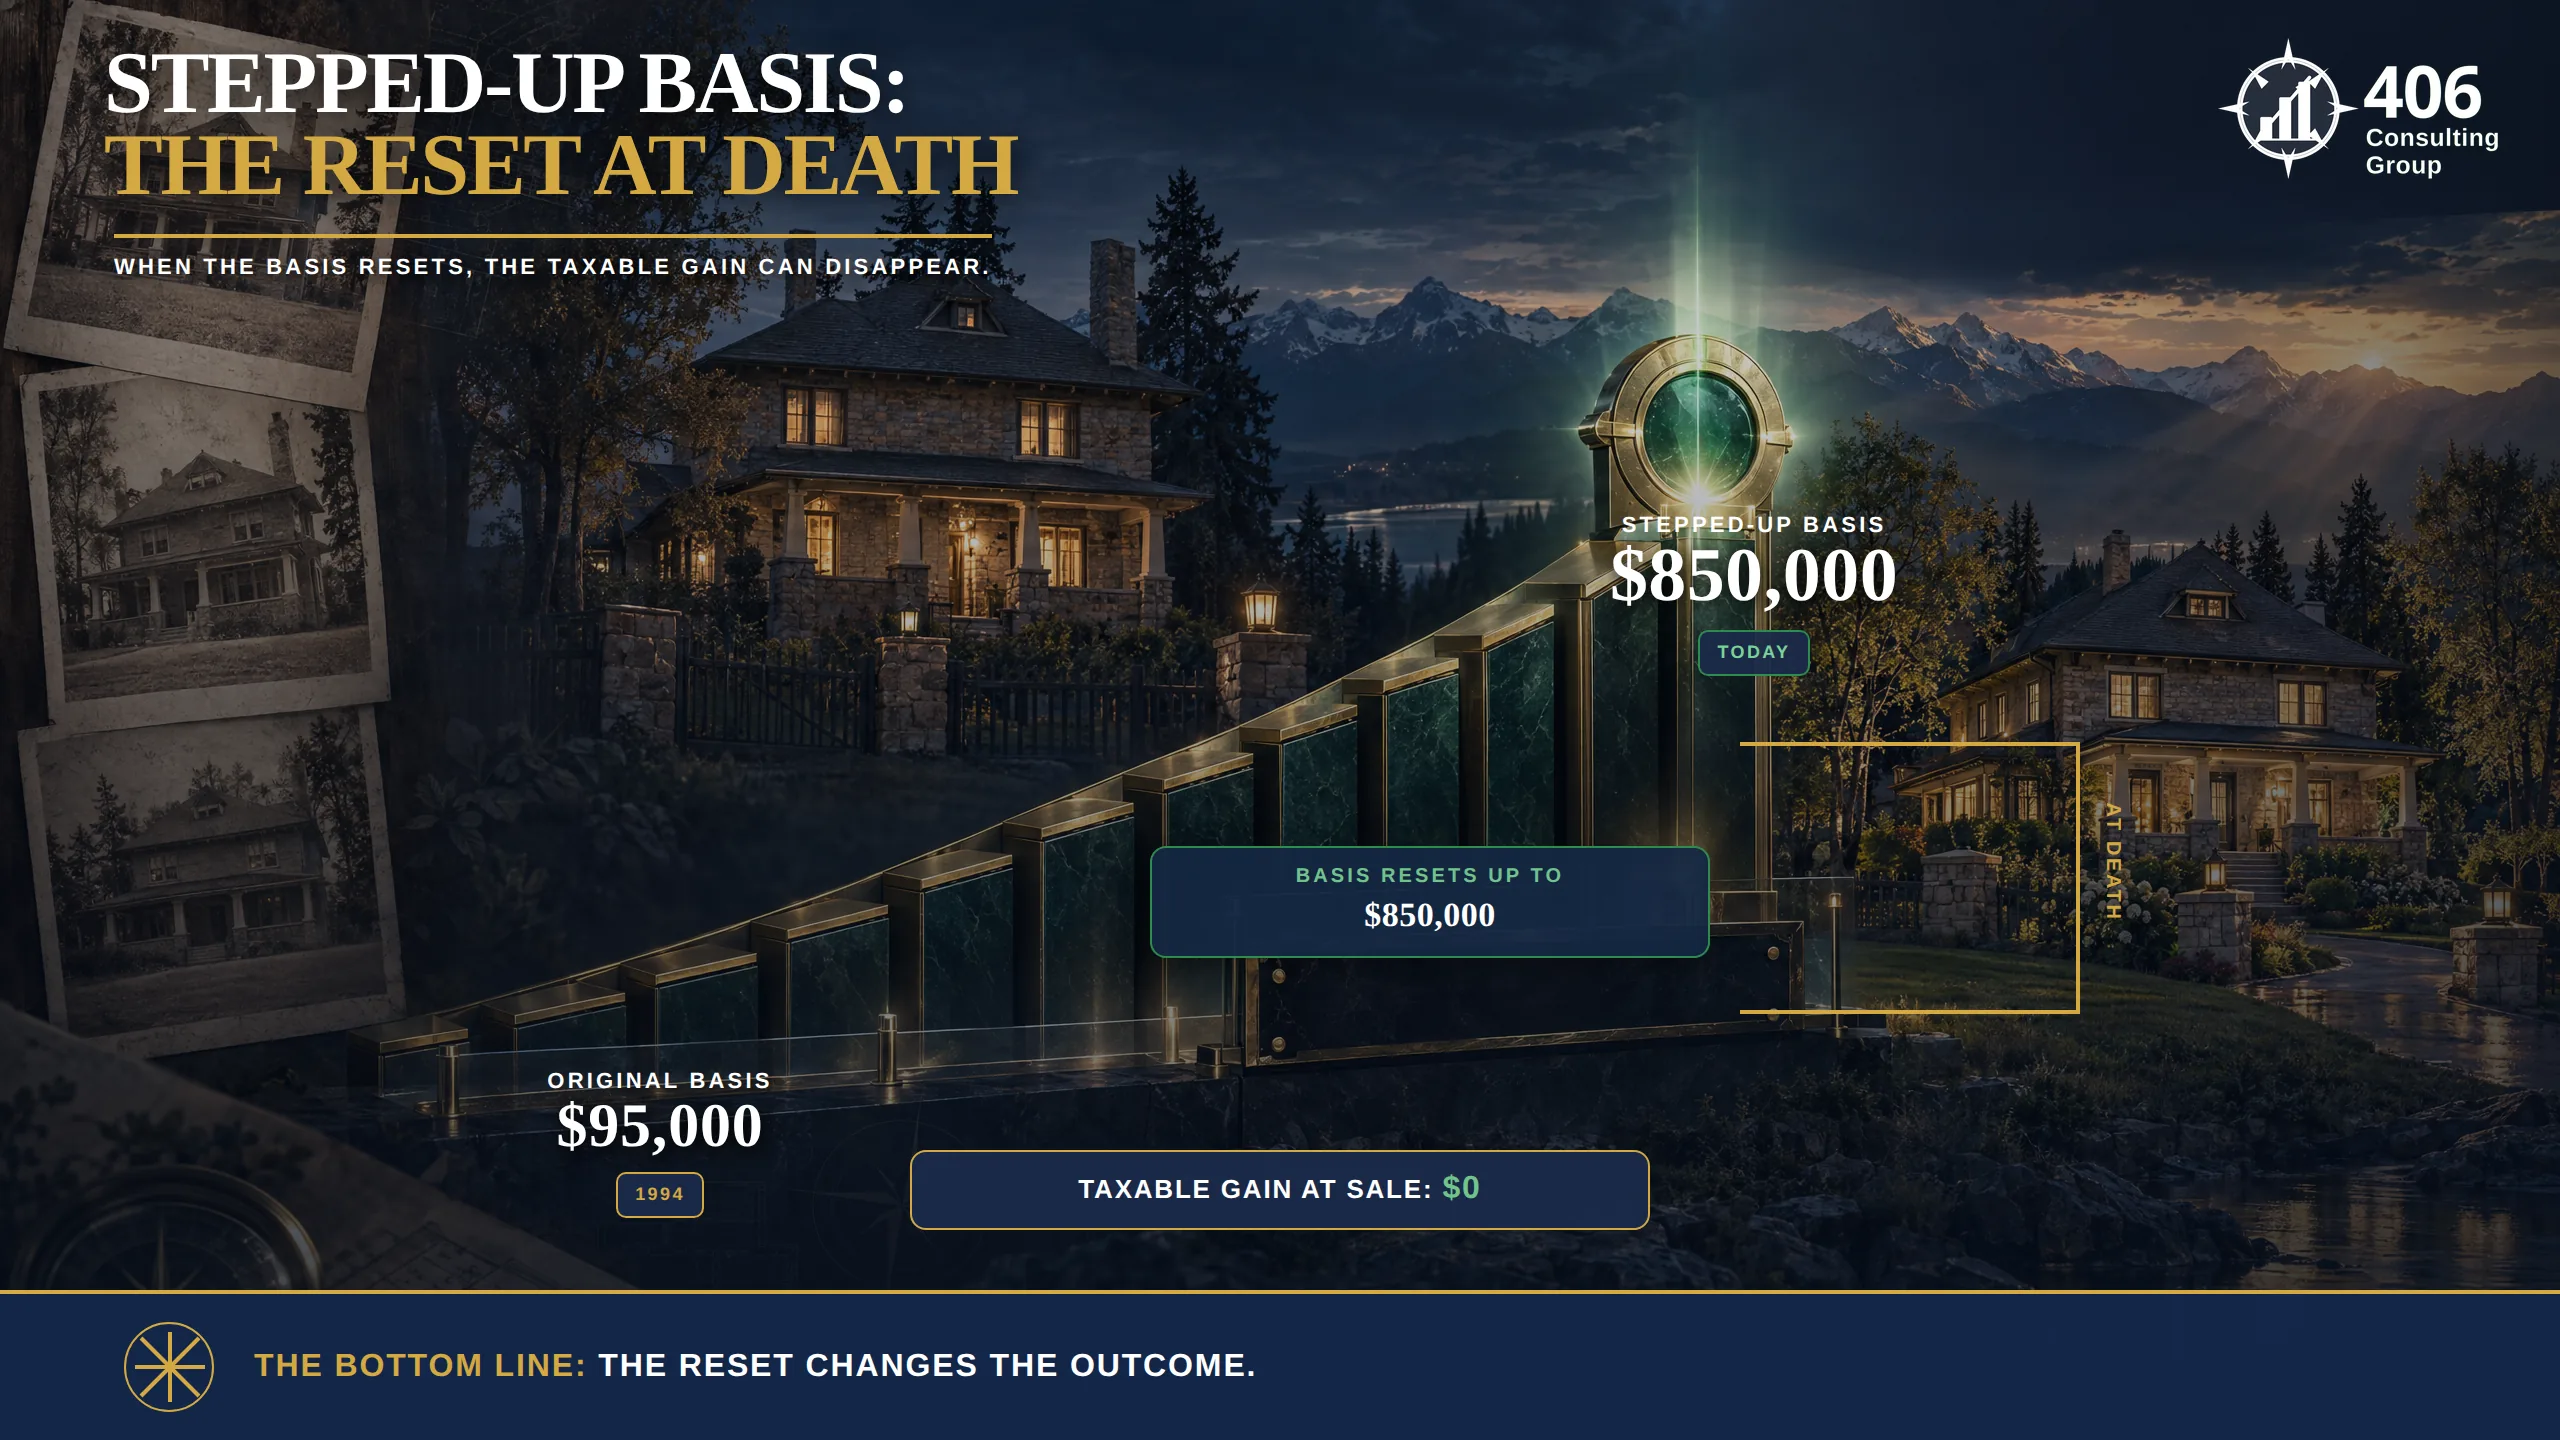
Illustrative example (hypothetical)
The Petersons bought their Bigfork home in 1994 for $95,000. Today it is worth $850,000. If their kids inherit it, the basis steps up to $850,000. If the kids sell it the next week for $850,000, their taxable gain is $0 — and so is the capital-gains tax. A lifetime of appreciation passes to the next generation completely untaxed. That is the break at stake.
Add a Child to the Deed Instead, and You Trade the Step-Up for Carryover Basis
Here is the part nobody explains at the kitchen table. The moment you add your child to the deed, you have made a gift of part of your house — and gifts come with a very different basis rule (Section 1015): the person receiving a gift takes the giver's original basis. There is no reset. Your child inherits your 1994 cost, not today's value, on the share you gave them.
So you have quietly converted the best basis rule in the code (step-up at death) into the worst one for appreciated property (carryover by gift) — on the portion you gave away. The house still avoids probate. It no longer avoids the tax.
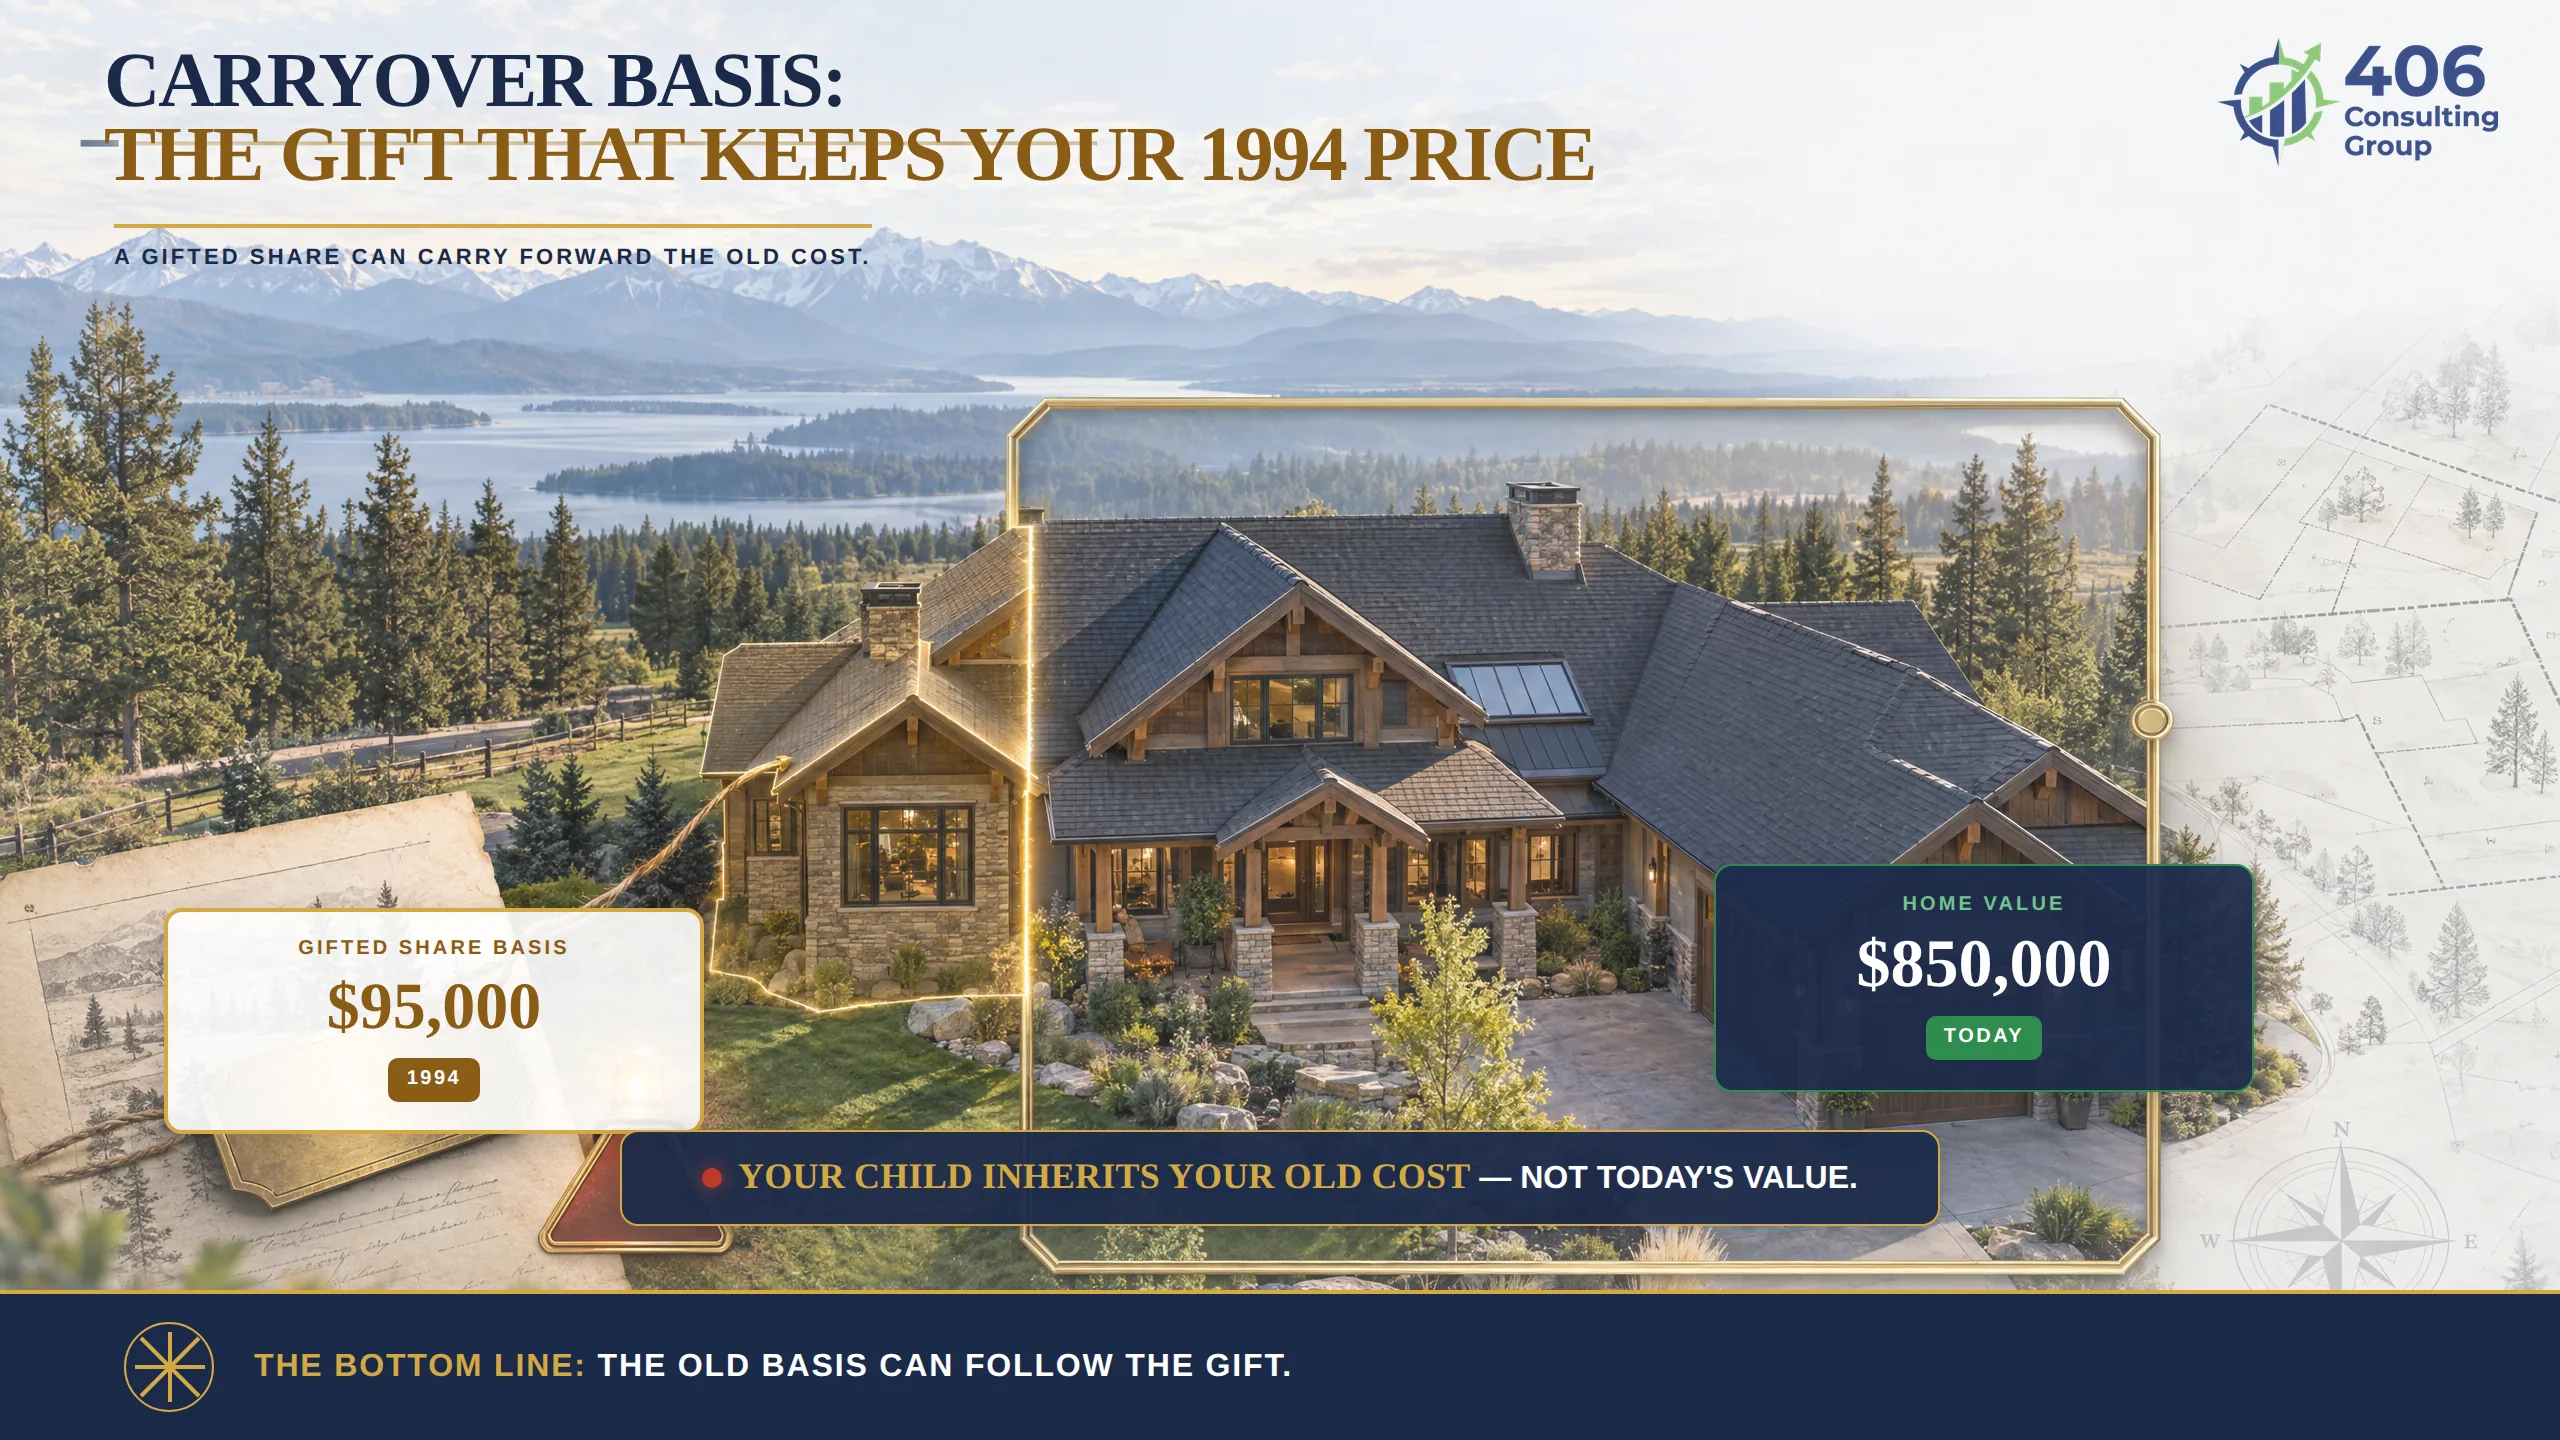
The timing trap: a gift is a lifetime transfer; a step-up only happens at death. By moving the house during your life, you move it out of the one event — your death — that would have reset its basis. The deed can't be un-gifted after the fact.
The Six-Figure Math
Numbers make it real. Take the same Bigfork house — $95,000 basis, $850,000 today — and say a widowed parent added her two adult children to the deed as equal co-owners (one-third each). Watch what happens at her death when the kids sell.
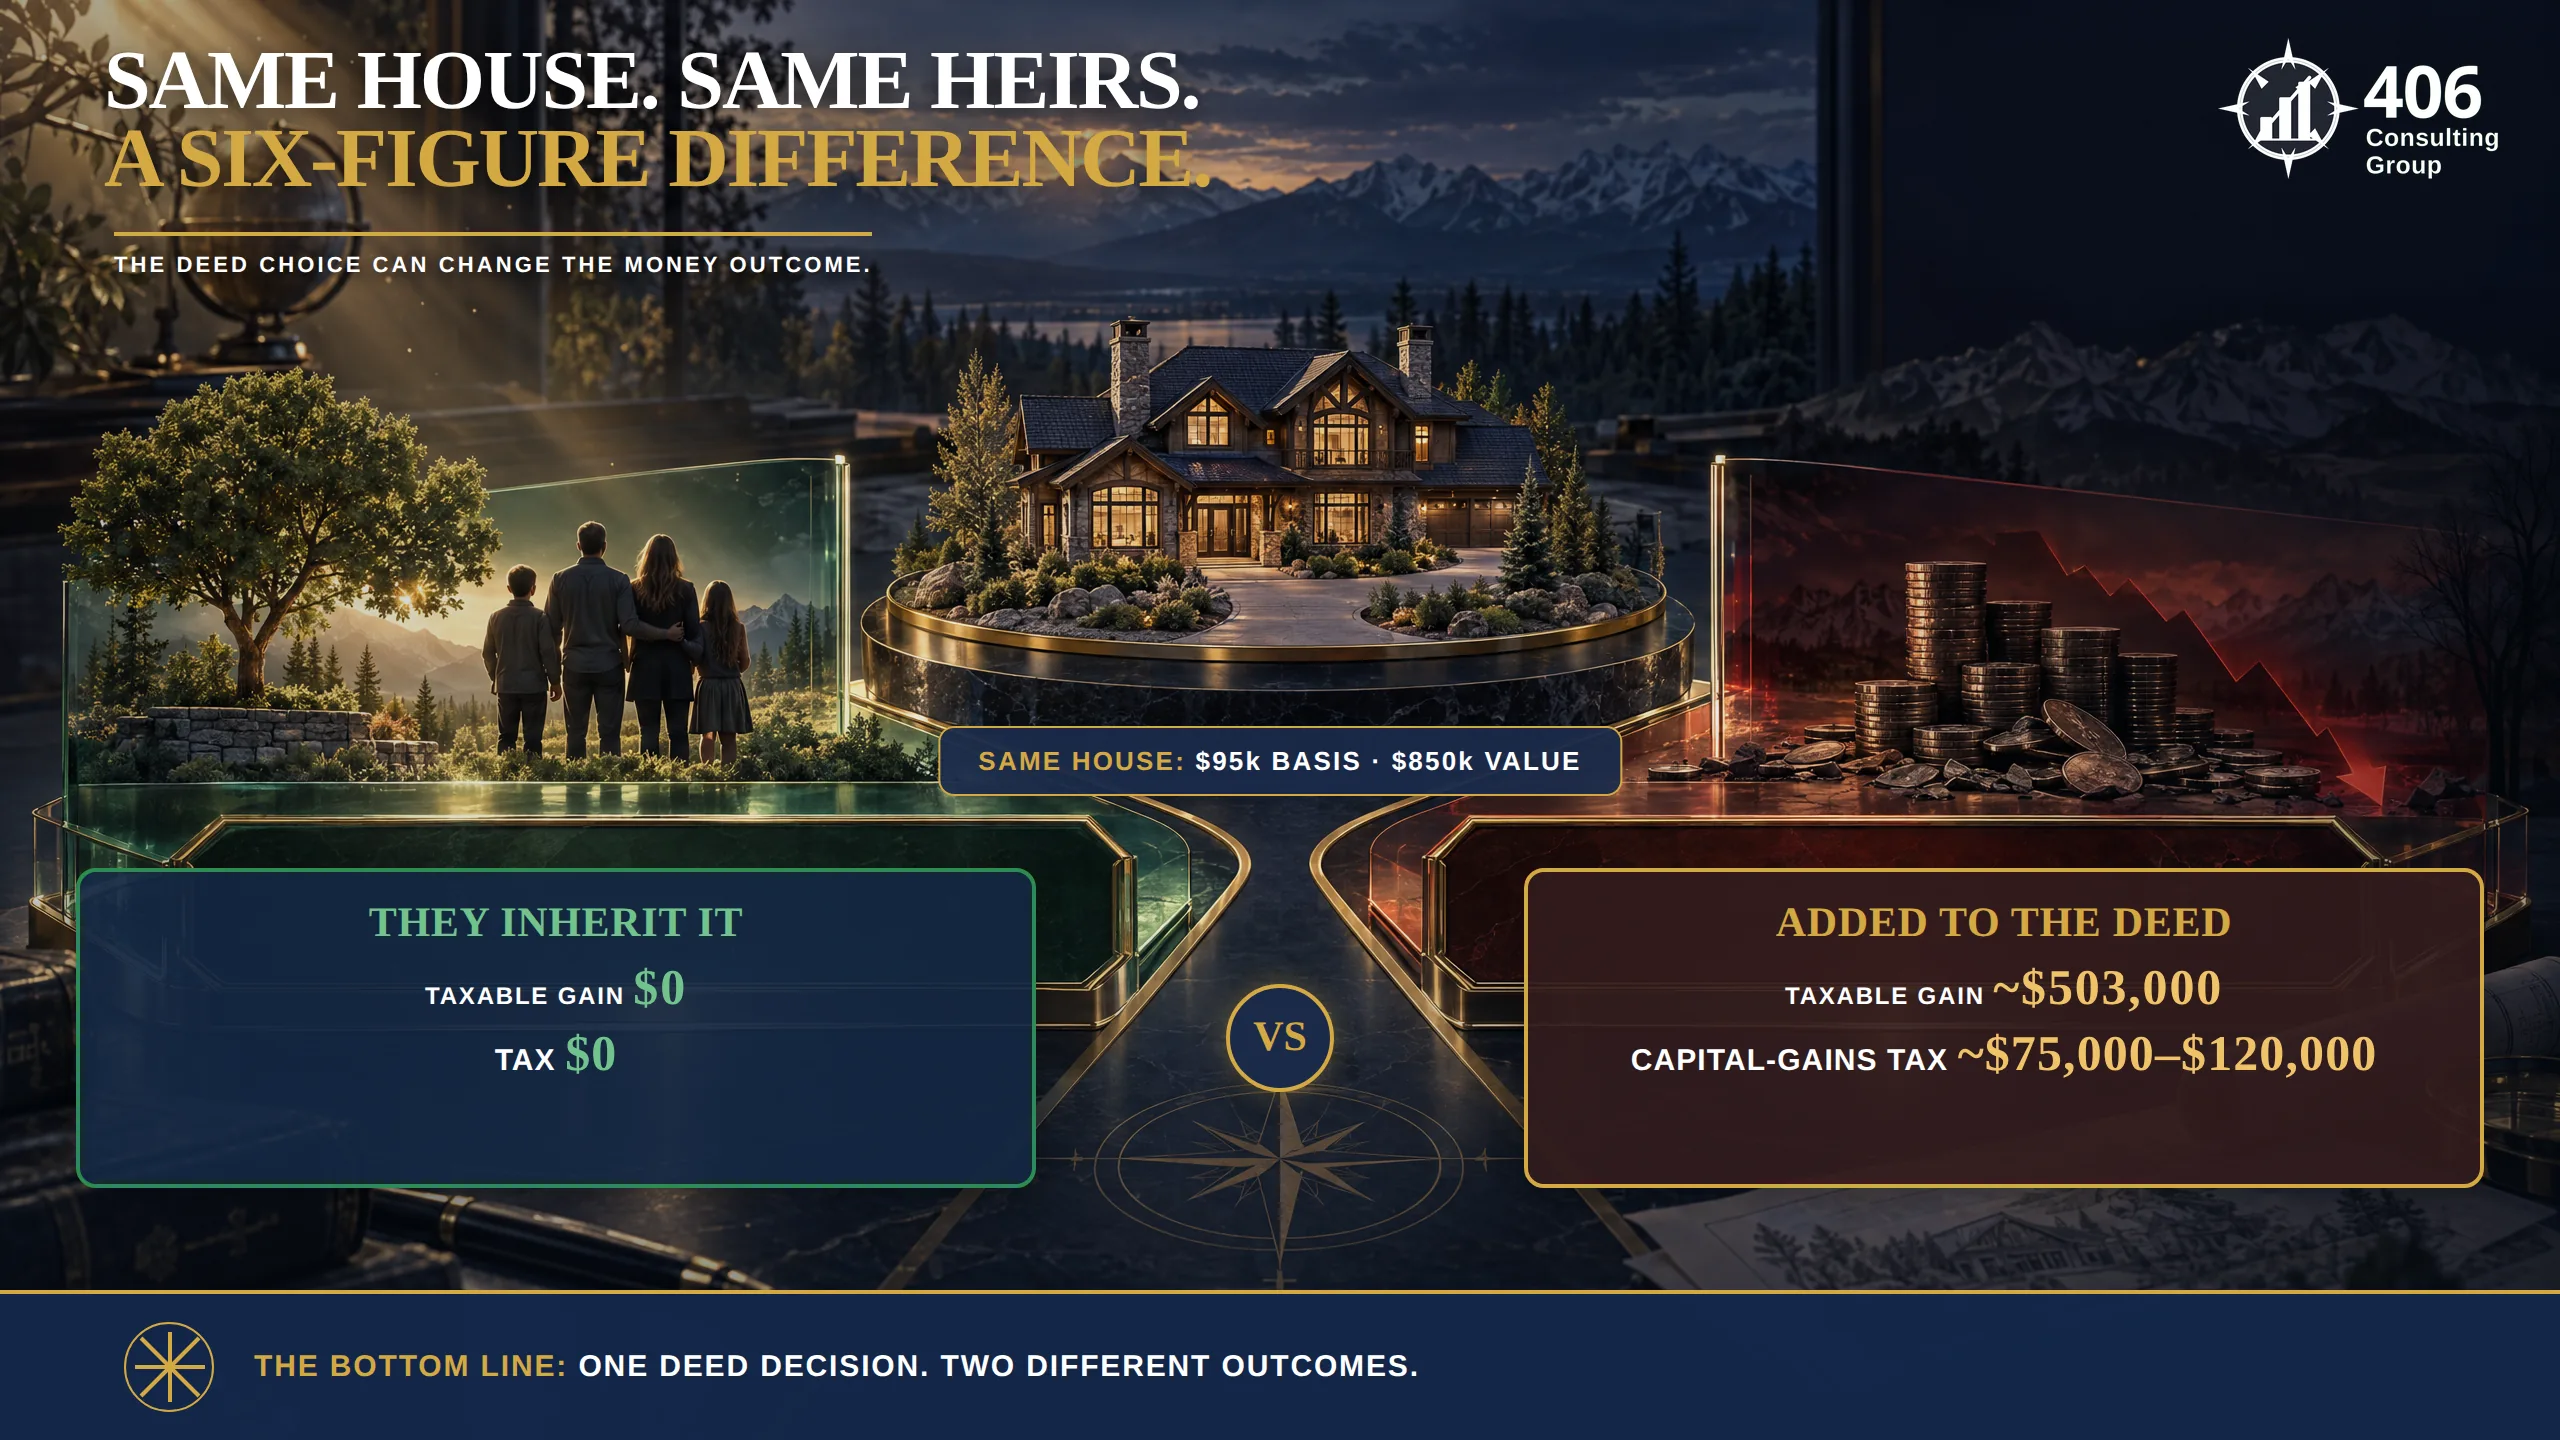
| They inherit it (trust / TOD deed / will) | Added to the deed years ago | |
|---|---|---|
| Sale price | $850,000 | $850,000 |
| Parent's retained 1/3 | Steps up: $283,333 | Steps up: $283,333 |
| Kids' gifted 2/3 | Steps up: $566,667 | Carryover: 2/3 × $95,000 = $63,333 |
| Total basis | $850,000 | $346,667 |
| Taxable gain | $0 | $503,333 |
| Federal capital-gains tax* | $0 | ~$75,000–$120,000 |
*Illustrative. Federal rate on long-term gains is typically 15% or 20% depending on the heirs' income, plus a 3.8% net investment income tax at higher incomes — and then Montana taxes the gain on top. Figures round for clarity; confirm current rates with your tax advisor.
Same house. Same heirs. Same probate avoided. The only difference is a deed signed years earlier — and it costs the family somewhere between a good used truck and a down payment on a second home. To dodge a probate process that, in Montana, a transfer-on-death deed handles for the price of a recording fee.
“But I Heard Joint Tenancy Still Gets a Step-Up” — the Dangerous “It Depends”
Here is where well-meaning advice gets slippery. There is a special rule for joint tenancies: if a parent paid for the whole property and simply added a child as a joint owner, the full value can be pulled back into the parent's estate at death — which would restore the full step-up. So someone, somewhere, will tell you “joint tenancy is fine, it still steps up.”
Sometimes that is true. The problem is the word sometimes. The outcome depends on the exact form of ownership, how the deed is written, whether the gift is treated as complete, state law, and whether anyone can document who paid for what decades later. A tenancy-in-common deed behaves differently than a joint tenancy. The step-up you get automatically and with certainty from a trust, a TOD deed, or a will becomes, with a deed change, a maybe you are betting six figures on.
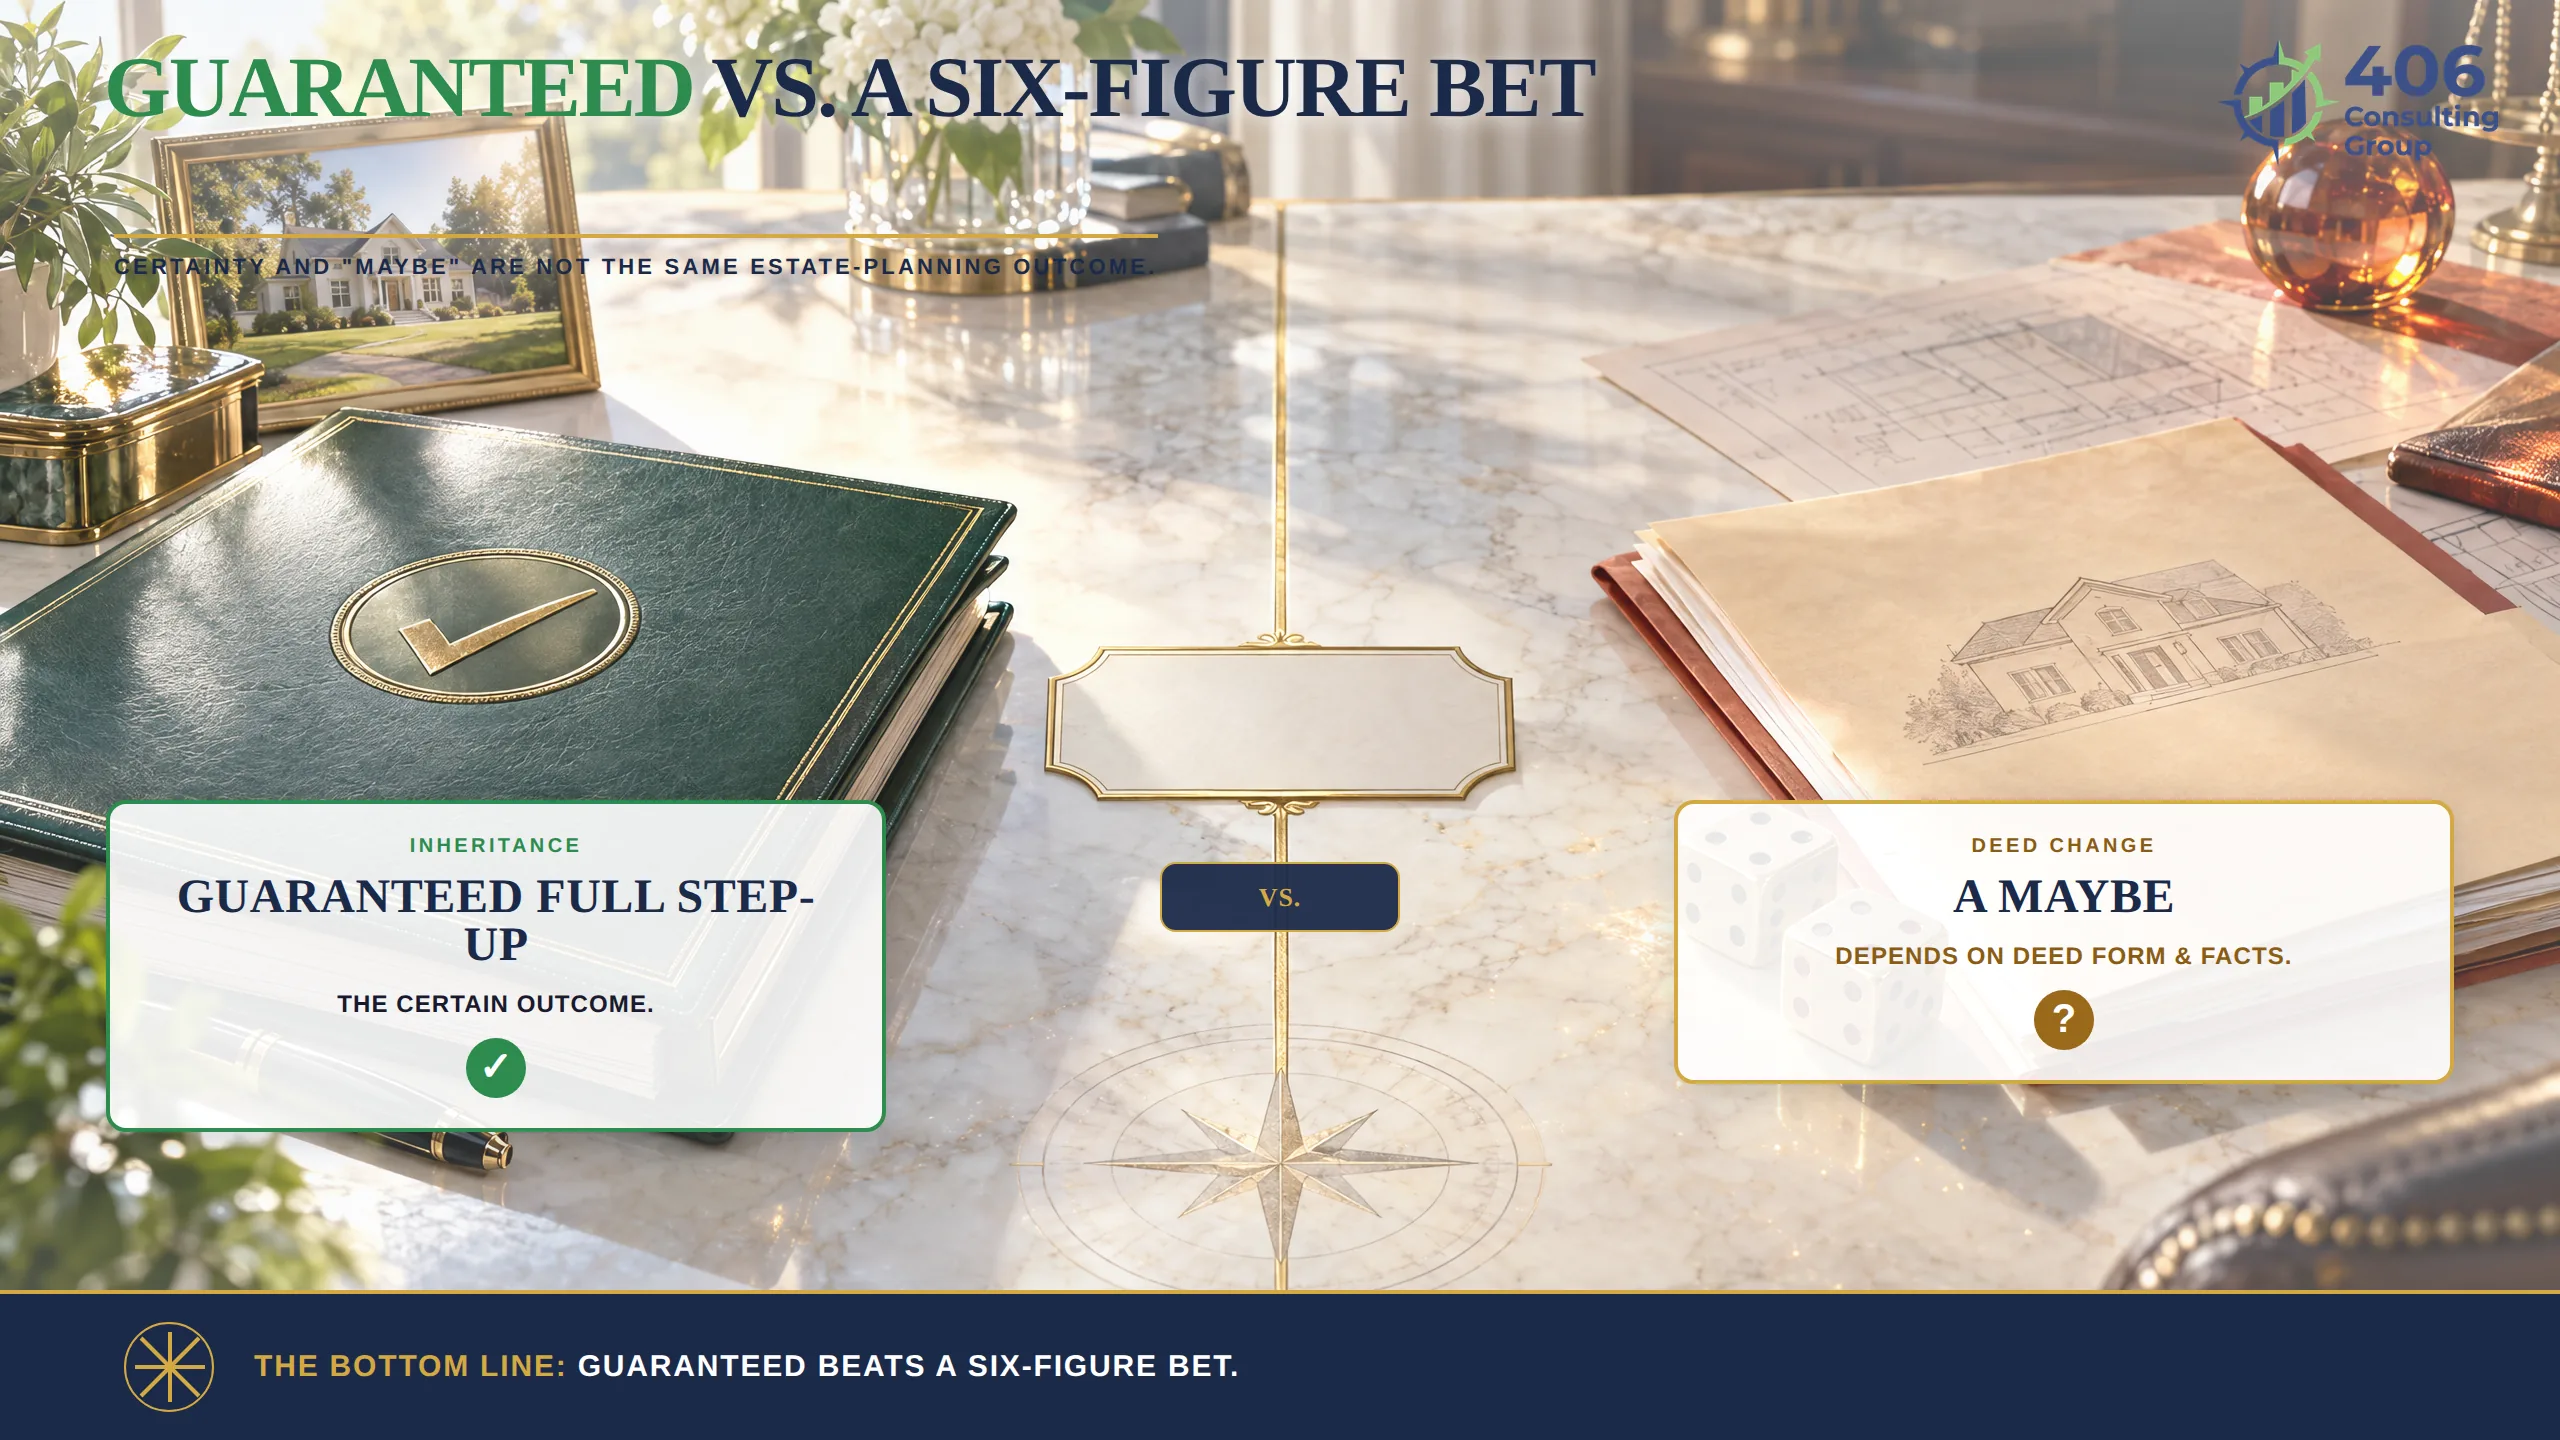
Inheritance
A guaranteed, clean, full step-up. No documentation gymnastics. No “it depends.”
Deed change
A fact-dependent maybe — and the IRS resolves ties years later, after the person who knew the facts is gone.
When the downside is a six-figure tax bill and the upside is saving a probate process you can skip other ways, “it probably works out” is not a plan. It is a wager.
The Gift-Tax Return You Didn't Know You Filed
There is a second, smaller surprise. Adding a child to a deed is a reportable gift. If the value of the share you give exceeds the annual exclusion — $19,000 per recipient in 2026 — you are required to file a federal gift-tax return (Form 709) for the year you signed the deed. Hand half of an $850,000 house to two kids and you have made gifts far north of that.
The good news, and the reason this is the smaller problem: almost no one actually owes gift tax. Every person has a lifetime gift and estate exemption of $15 million in 2026 (made permanent by the 2025 tax law), and the gift simply draws against that. You file the return, you use a sliver of a very large exemption, and you write the IRS a check for $0.
Keep the two straight: the gift tax on a deed change is usually a paperwork event, not a bill. The capital-gains tax from the lost step-up is the real money. People hear “no gift tax due” and assume the whole move is free. It isn't — the cost just shows up later, on a different form, in a different generation's hands.
The Non-Tax Landmines (Reasons It Backfires Even If the Tax Didn't)
Even set the capital-gains trap aside and the deed shortcut still carries risks that probate never would. The instant your child is a legal co-owner of your home, your home is exposed to their life.
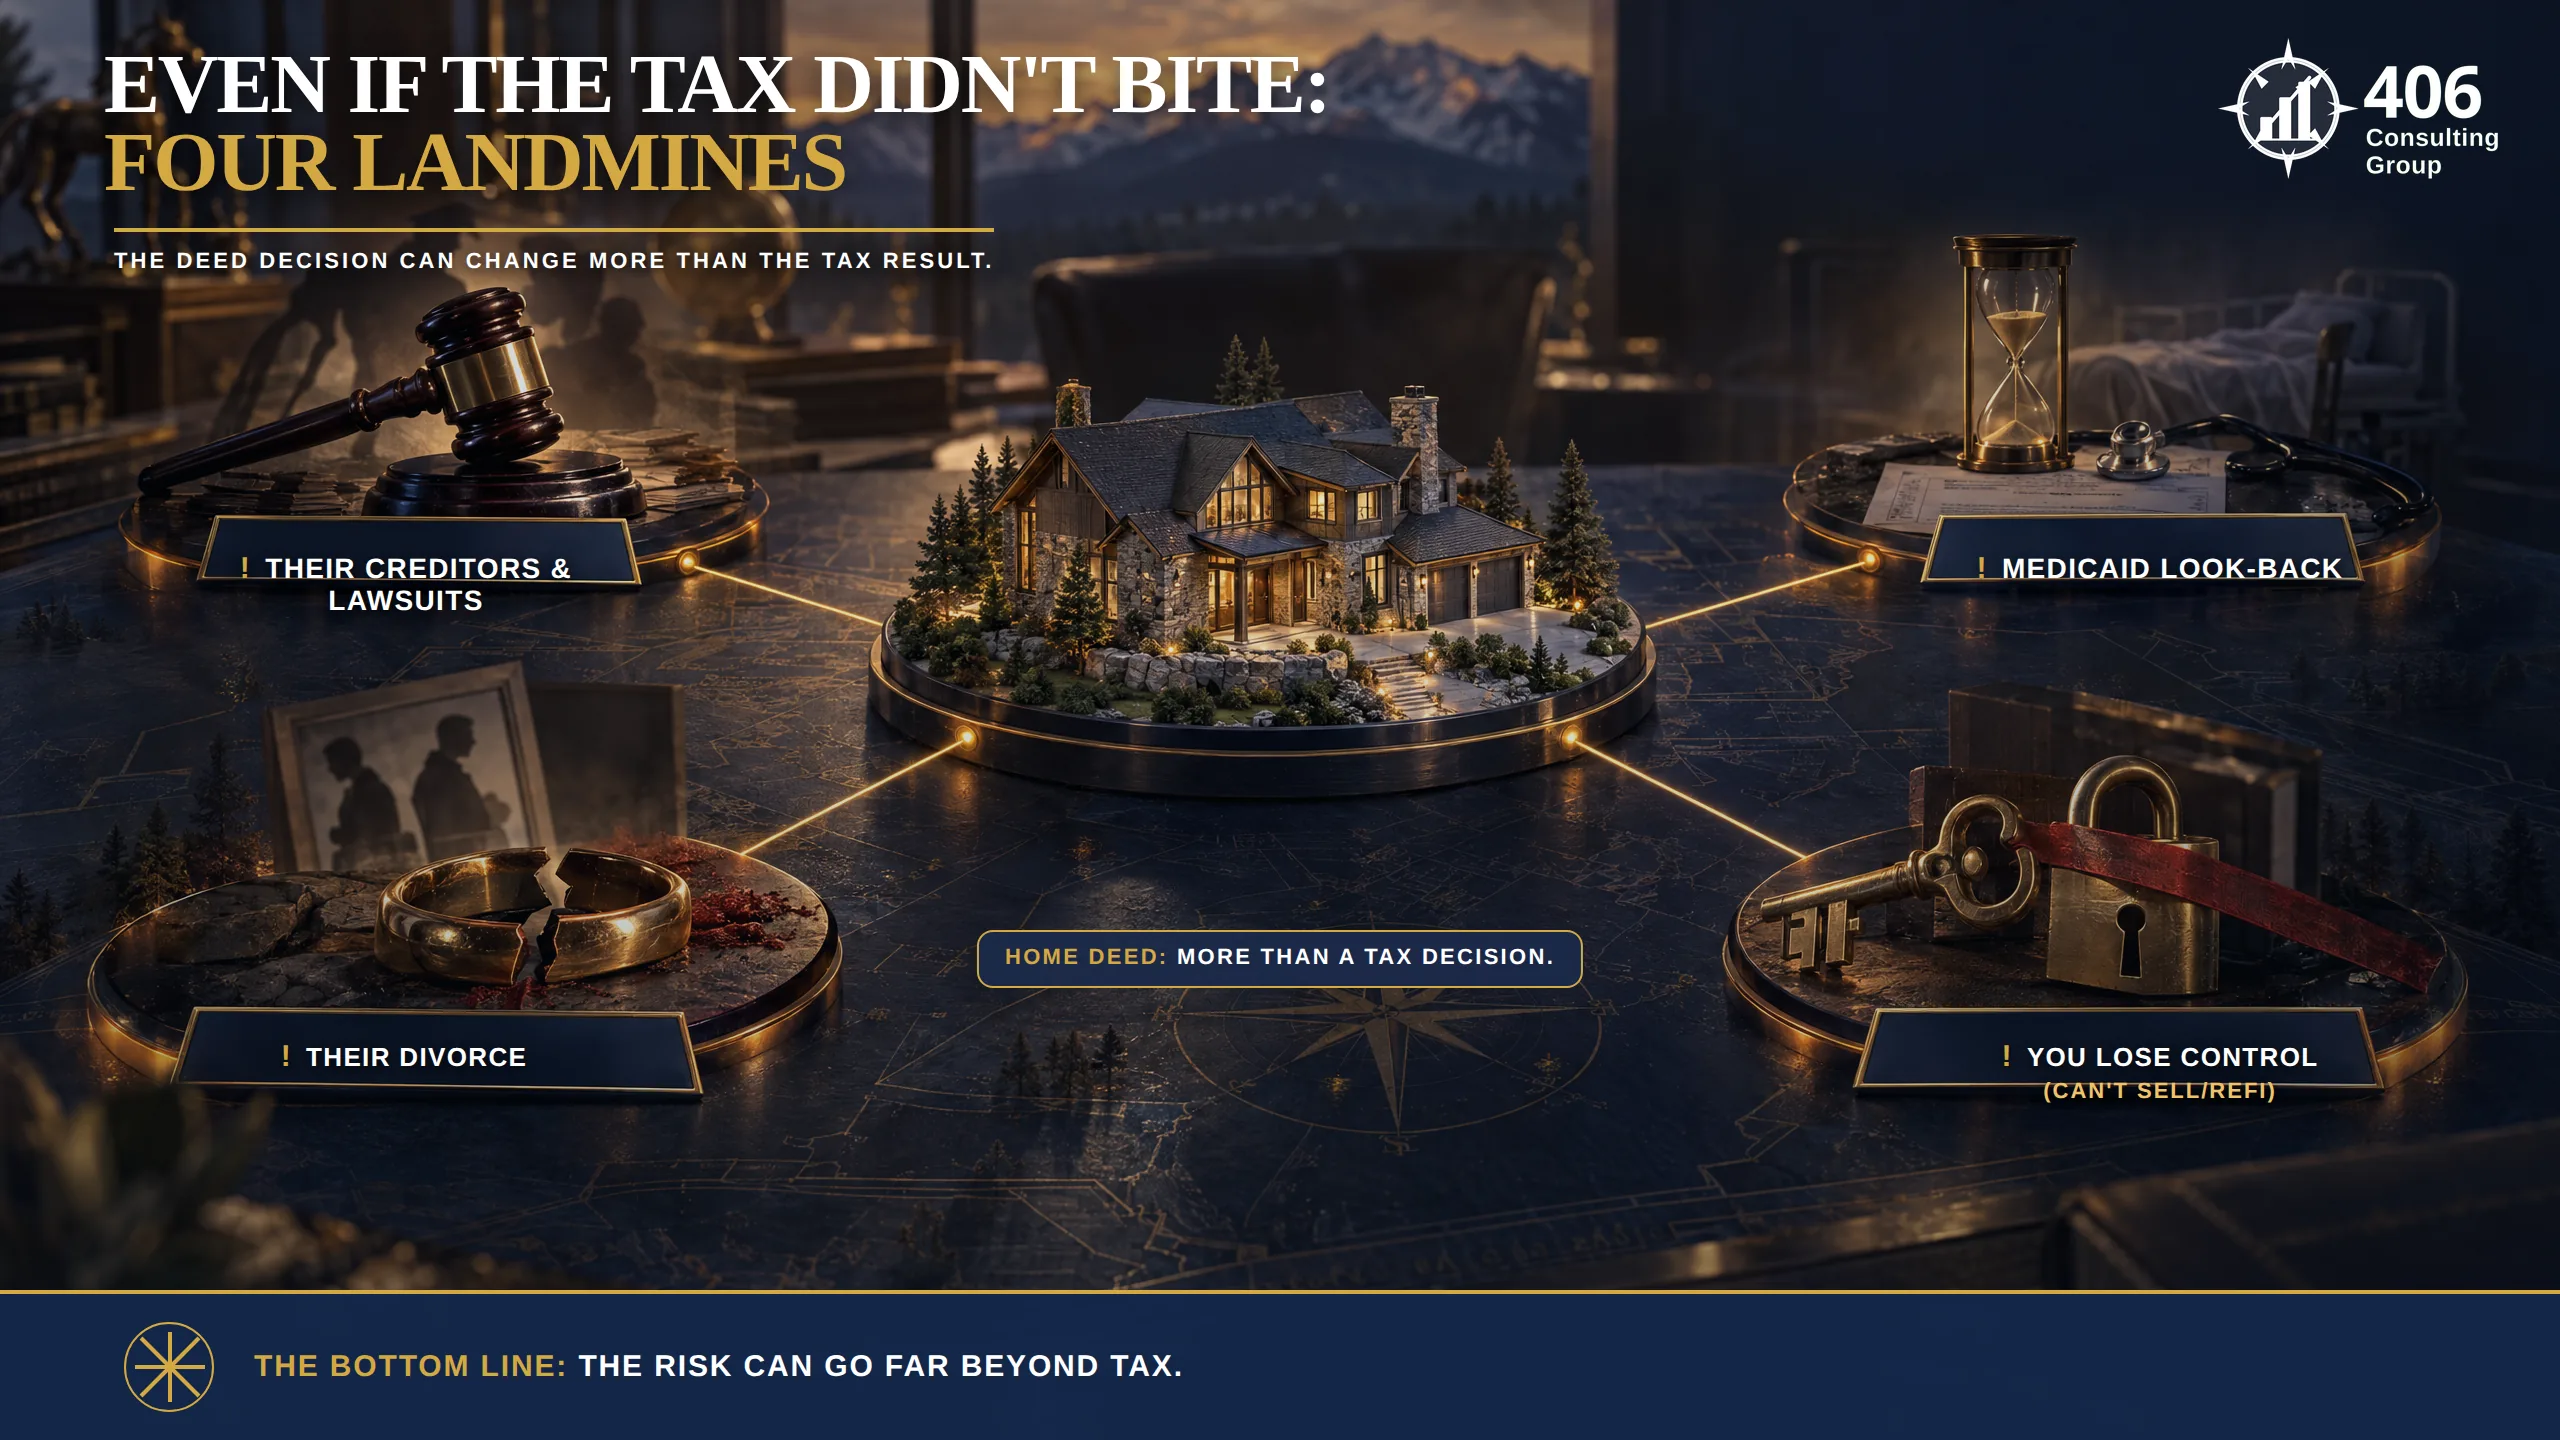
- Their creditors become your problem. A co-owner child's creditors, a lawsuit judgment, or a bankruptcy can attach to their share of your house. A car accident or a failed business on their end can put a lien on your home.
- Their divorce can pull your house in. A child's ownership interest can become a marital asset in a divorce, dragging your home into a settlement negotiation you are not even part of.
- You lose control. You now need your co-owner's signature to sell or refinance. If a child refuses, moves away, or you simply fall out, you can be stuck in your own home.
- Medicaid look-back. Giving away part of your home is a transfer that can trigger a penalty period for long-term-care Medicaid eligibility — the opposite of what many people are trying to protect.
How to Skip Probate Without the Tax Bomb
Here is the part that makes the whole thing frustrating: you can almost always get the probate savings and keep the step-up. The tools already exist. Which one fits is a legal and estate-planning decision for your attorney — our job is to make sure the tax consequences are on the table before you choose.
Revocable living trust
You put the house in a trust you control and can change at any time. It avoids probate, you keep full control while living, there is no lifetime gift, and because the home is still yours at death, it gets the full step-up. The most flexible option, especially with multiple assets or heirs.
Montana transfer-on-death (TOD) deed
Montana law (Title 72, Chapter 6, Part 4 — the Uniform Real Property Transfer on Death Act, which replaced the older “beneficiary deed” in 2019) lets you record a deed that passes the house to your chosen person at death. It has no effect while you're alive — you keep full control, you can sell or refinance, and you can revoke it anytime. The kids own nothing until you're gone, so the house avoids probate and gets the full step-up. For a single home, it is often the simplest clean answer. Outside Montana: most states now offer some version of a transfer-on-death or “beneficiary” deed — a handful don't — so check whether your state has one; where it isn't available, a revocable living trust does the same job everywhere.
A plain will
A will goes through probate — but probate in Montana is frequently faster and less expensive than the horror stories suggest, and property passing under a will still gets the full step-up. Sometimes the tax certainty is worth more than the probate savings.
Notice what every good option has in common: the house passes at death, not during your life. That one detail is what preserves the step-up. The deed shortcut is the only popular option that moves the house early — and that is exactly why it costs so much.
How 406 Looks at This
Most people who make this mistake got there honestly. They talked to a friend, or a title company, or even an attorney focused narrowly on avoiding probate — and nobody ran the capital-gains number for the day the house gets sold. The deed question got answered. The tax question never got asked.
That gap is exactly where we live. We don't draft your deed or write your trust — that is your estate attorney's job, and a good one is worth every dollar. What we do is sit in the money seat: we look at the whole picture, run the actual basis and capital-gains math on your specific house and your specific family, and make sure the tax consequence is visible before an irreversible deed gets signed — then we coordinate with your attorney so the legal tool and the tax outcome actually line up. We've seen how this one ends. The best time to look at it is before the ink is dry.
Frequently Asked Questions
Does adding my child to the deed actually avoid probate?
Often yes, if the deed is set up with a right of survivorship so your share passes to the co-owner automatically at death. That part usually works. The problem is the price: on appreciated property you trade away the stepped-up basis on the share you give, which can create a six-figure capital-gains bill when the house is sold. You can get the same probate avoidance from a trust, a Montana transfer-on-death deed, or a will without giving up the step-up.
Will my kids really lose the step-up if I put them on the deed?
On the share you give them during your life, generally yes — a gift carries your original cost basis forward (Section 1015) instead of resetting at death (Section 1014). Joint tenancies have a special rule that can sometimes pull the full value back into your estate and restore the step-up, but it is uncertain and depends on the deed form, state law, and documentation. Inheritance gives a guaranteed step-up; the deed change turns it into a maybe.
Do I owe gift tax if I add my child to the deed?
You likely have to file a gift-tax return (Form 709) because the share you give exceeds the 2026 annual exclusion of $19,000 per recipient, but you probably won't owe any gift tax. Every person has a lifetime gift and estate exemption of $15 million in 2026, and the gift just draws against it. The real cost of the deed move is almost never gift tax — it is the lost step-up and the capital-gains tax that follows.
Is a transfer-on-death deed better than adding my kids to the deed?
For most Montana homeowners trying to avoid probate on a single home, yes. A Montana transfer-on-death deed passes the house at your death, so it avoids probate and keeps the full step-up, and it has no effect while you are alive — you keep control and can revoke it anytime. Adding your kids to the deed gives up the step-up and hands them ownership (and its risks) now. Which tool is right for you is a decision to make with an estate attorney.
I already added my kids to the deed. Can I undo it?
Sometimes the ownership can be restructured, but it is fact-specific and can have its own tax and legal consequences, so it needs an estate attorney and a tax advisor working together — not a DIY fix. The sooner you look at it the more options you usually have. We can run the current tax exposure and coordinate with your attorney on the cleanest path.
Does 406 Consulting Group help with this?
Yes, on the tax and financial side. We are not an estate law firm and we do not draft deeds or trusts — that is your attorney's role. What we do is run the real basis and capital-gains math on your specific home and family, show you the tax consequence of each option before anything is signed, and coordinate with your estate attorney so the legal tool and the tax outcome line up. This is tax education, not legal advice.
The bottom line
Avoiding probate is a good goal. Adding your kids to the deed is the one way to do it that throws away the stepped-up basis — and can cost the family six figures in capital-gains tax. Keep the probate savings; keep the step-up.
Keep Reading
External Resources
Run the real numbers first
Before you sign anything, let's look at your home's basis and the tax of each option — and coordinate with your attorney.
This article is general tax education, not legal, tax, or financial advice for your specific situation. Deed and estate decisions should be made with a qualified estate attorney; we are glad to handle the tax analysis alongside them.