
How Much Can My Business Borrow?
The Number Lenders Actually Run
Lenders size your loan off your cash flow, not your ambition — using debt-service-coverage ratio (DSCR). Here's the math, why your number is often lower than you expect, and how to raise it.
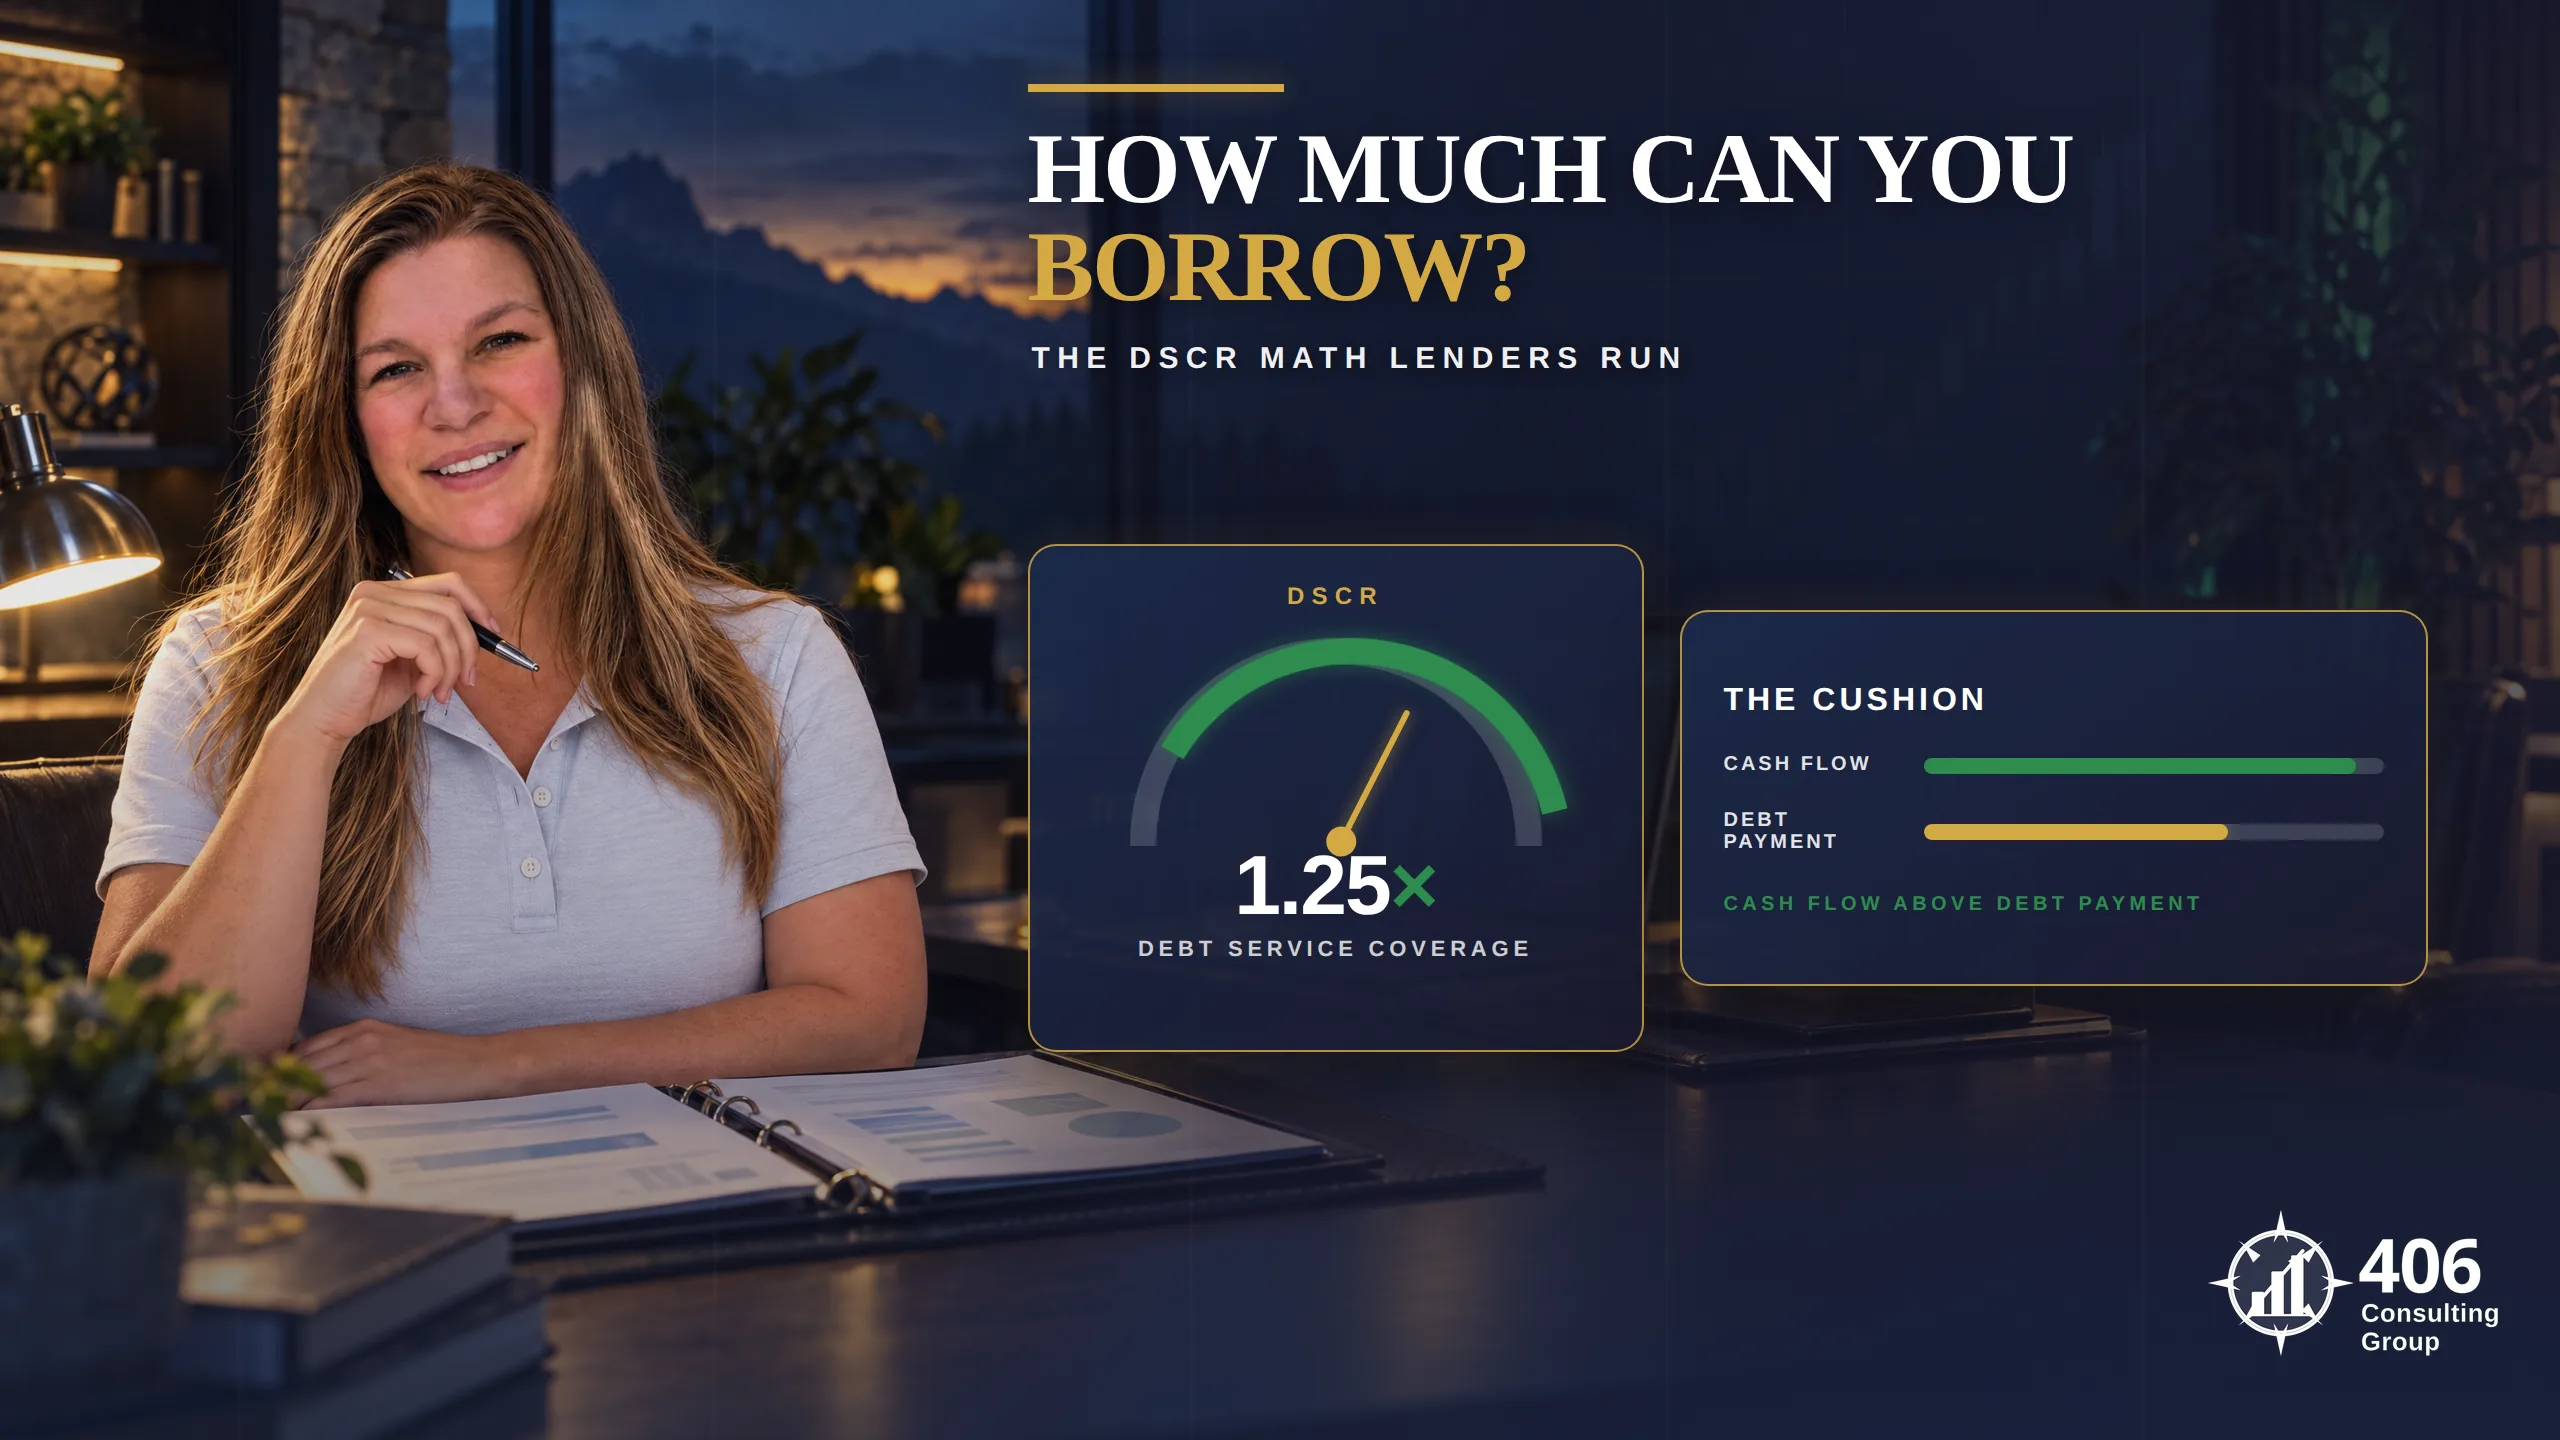
Lenders don't size your loan off what you want — they size it off your cash flow, using a number called the debt-service-coverage ratio (DSCR). DSCR is your annual cash flow available for debt divided by your annual loan payments. Most lenders want at least about 1.25— roughly $1.25 of cash flow for every $1 of payments. That ratio, not your ambition, sets your borrowing ceiling. Want to borrow more? You raise the cash flow the ratio is built on.
By Carrie Anderson
Co-Founder, 406 Consulting Group
Commercial banker and underwriter — 300+ loan files reviewed firsthand.
DSCR thresholds vary by lender and loan type and change over time; the figures below are typical, not a guarantee. Confirm specifics with your banker.
What's DSCR, in plain English?
It's the single number that tells a lender whether your business can comfortably make the payments on a new loan. Think of it as a cushion: how much more cash you generate than the loan would cost you.
The formula
DSCR = annual cash flow available for debt ÷ annual debt payments
If your business throws off $125,000 of cash flow a year and the loan payments would total $100,000 a year, your DSCR is 1.25. A 1.0 means you'd spend every dollar of cash flow on the payment with nothing left for a bad month — which is why lenders want a margin above it. Below 1.0, the math says you can't cover the loan, and the answer is usually no.
How lenders turn DSCR into a loan amount
They work backwards. They start with your cash flow, decide the minimum DSCR they'll accept, and that tells them the biggest annual payment you can support — which, at current rates and terms, sets the biggest loan they'll write. You don't pick the number; your cash flow does.
Working the math backwards
A Missoula contractor generates $150,000 a year in cash flow. At a required 1.25 DSCR, the lender divides $150,000 by 1.25 and gets $120,000 — the most they'll let the business spend on annual debt payments. Whatever loan size produces a payment at or under $120,000 a year (at today's rate and term) is the ceiling. Ask for more and the answer isn't “no forever” — it's “grow the cash flow first.”
Why your number is often lower than you expect
Because lenders are conservative with the top half of that ratio. They may add back some non-cash expenses but haircut optimistic ones, they stress-test against a slower year, and they count all your debt — existing loans, that line of credit you never paid to zero, sometimes even owner obligations (a “global” DSCR). The thresholds also move with the loan: an SBA loan might accept something near 1.1–1.15 because the government backs part of it, while an unsecured line can want 1.5 or more. The messier your books, the more they assume the worst — which shrinks the number.
How to raise your borrowing capacity
Grow real, provable cash flow — the top of the ratio is the biggest lever.
Clean up the books so legitimate add-backs actually count instead of being ignored.
Pay down existing debt — every payment you shed frees room under the ratio.
Don't run your line of credit evergreen; a permanent balance counts against you.
Bring current, accurate financials so the lender doesn't have to haircut for uncertainty.
I sized loans off this number for years. The owners who got the most weren't the ones who asked loudest — they were the ones whose books made the cash flow easy to see. When a lender can trust the numbers, they lend against the real figure instead of a discounted one.
When the loan is make-or-break, you usually get one shot
For the harder programs — an SBA 7(a) or 504 loan, a USDA business & industry loan — the bar is higher and the file is longer. These are often the loans that decide whether a business buys the building, lands the expansion, or makes the acquisition at all. And with a given bank, you frequently get one real shot: a weak, incomplete, or poorly-framed package gets declined, and a decline is hard to walk back with that lender.
This is where having someone who has sat on the lender's side changes the odds. We know what these programs weigh, how the file should be built, and how to frame your DSCR and cash flow the way an underwriter reads them — so the strongest version of your case is the one that lands on the desk the first time. On a loan that matters, that difference can be approval instead of a “no.”
Want to know your number before the bank does?
We'll calculate your DSCR, show you the loan size it supports, map the moves that raise it, and — on an SBA, USDA, or other make-or-break loan — help you walk in with your strongest file the first time, from someone who used to run this math on the lender's side.
FAQ
What DSCR do lenders require for a business loan?
Most conventional lenders want a debt-service-coverage ratio of at least about 1.25, meaning roughly $1.25 of cash flow for every $1 of loan payments. It varies by loan type: SBA loans may accept something closer to 1.1–1.15 because the government guarantees part of the loan, while an unsecured line of credit can require 1.5 or more. Below 1.0, the math says you can't cover the payments, and approval is unlikely. Always confirm the threshold with your specific lender.
How do I calculate my DSCR?
Divide your annual cash flow available for debt by your annual debt payments. A common starting point for the top number is net operating income plus non-cash expenses like depreciation; the bottom number is the total of principal and interest payments on the debt in question (and often your existing debt too). Example: $125,000 of cash flow divided by $100,000 of annual payments equals a DSCR of 1.25. Lenders may adjust your figures, so your calculation and theirs can differ.
How can I borrow more than my DSCR allows?
You raise the cash flow the ratio is built on — that's the biggest lever — and you reduce the payments side by paying down existing debt. Cleaning up your books also helps, because legitimate add-backs only count toward cash flow when a lender can verify them, and current financials mean the lender doesn't have to discount your numbers for uncertainty. In short: grow provable cash flow, shed debt, and make the numbers easy to trust.
This article is general financial education, not lending, legal, or financial advice for your specific situation. DSCR calculations and thresholds vary by lender and loan type.
In one line
Your loan ceiling is set by DSCR — cash flow ÷ payments, usually needing ~1.25x. Grow provable cash flow and shed debt to borrow more.