
What Counts as a "Reasonable Salary"?
The Part That Trips Up S-Corps
Your S-corp lives or dies on one number: your salary. Too low invites an audit; too high hands back the savings. What 'reasonable' really means, the many-hats method that produces a defensible number, and the myths that get owners in trouble.
Remember Sam — the contractor netting $150,000 who elected S-corp status to save on self-employment tax? Sam's entire strategy now hangs on a single number: his salary. Pay himself too little and he's waving a red flag at the IRS; pay himself too much and he hands back the savings he elected for in the first place. This one figure — "reasonable compensation" — is the part of the S-corp that trips up the most owners, and it's the part the cheap online advice gets dangerously wrong.
This guide is the deep dive on that number: what "reasonable" actually means, how the IRS decides, the method that produces a defensible figure, the myths that get people audited, and how to document it so it holds up. If you've read Should You Elect S-Corp? The Real Math, this is the sequel that keeps you out of trouble.
By Jason Anderson — Co-Founder, 406 Consulting Group. Big-firm-trained accountant who sets and defends reasonable-salary numbers for S-corp owners — and runs the payroll behind them. Illustrative figures below; your number depends on your role and your market.
Quick Answer: S-Corp Reasonable Salary
- →A reasonable salary is what you'd pay someone else to do the work you do in the business — based on real wage data, not a guess.
- →The IRS requires it before you take distributions; too low is a known audit trigger.
- →The best method is the "many hats" approach: split your time across the roles you play and price each at market.
- →Ignore the myths — there is no official "60/40 rule," and "pay yourself $0" is how you get reclassified.
- →Get a defensible number from the reasonable-salary calculator, then document it.
Table of Contents
The Number That Makes or Breaks Your S-Corp
Every dollar of S-corp savings comes from the profit you take as distributions instead of salary — because distributions skip the payroll tax. So the instinct is obvious: make the salary tiny, take everything as distributions, pocket the difference. The IRS knows that instinct exists, which is exactly why the law puts a floor under it. Your salary has to be reasonable, and that word is doing a lot of work. Set it right and the strategy sings. Set it wrong — in either direction — and you either overpay tax or invite an audit that can erase every dollar you saved.
The salary is the whole ballgame. It's the one number that decides both how much you save and how much risk you carry — and it's the one most owners pick out of thin air.
To set it well, it helps to understand why the IRS cares about it in the first place.
Why the IRS Watches This So Closely
Salary and distributions are taxed differently on purpose, and the gap is money the government doesn't collect. When an owner shifts pay from salary to distributions, Social Security and Medicare taxes go uncollected on the shifted amount — so understating owner salaries is, in the aggregate, a large revenue leak the IRS actively works to plug. That's why unreasonably low S-corp owner compensation is a well-known audit issue, and why the agency has won court cases reclassifying disguised distributions back into wages. It isn't looking for the "perfect" number; it's looking for owners who paid themselves suspiciously little to dodge payroll tax.
What the IRS suspects
A low salary next to big distributions looks like payroll tax being dodged — and that pattern is easy to flag.
What protects you
A salary you can explain with real wage data and a written rationale — a defensible number, not a lucky one.
So what does the law actually ask for? Less mysterious than it sounds.
What "Reasonable" Actually Means
Here's the plain-English test: a reasonable salary is what you'd have to pay someone else to do the job you doin your business. If Sam vanished and he had to hire people to cover everything he personally handles — the plumbing work, running the crews, quoting jobs, keeping the office straight — what would that cost at market rates? That number, adjusted for how much of each role he actually does, is his reasonable salary. It's not a percentage of profit, not last year's guess, and not the least he can get away with. It's the market value of his labor.
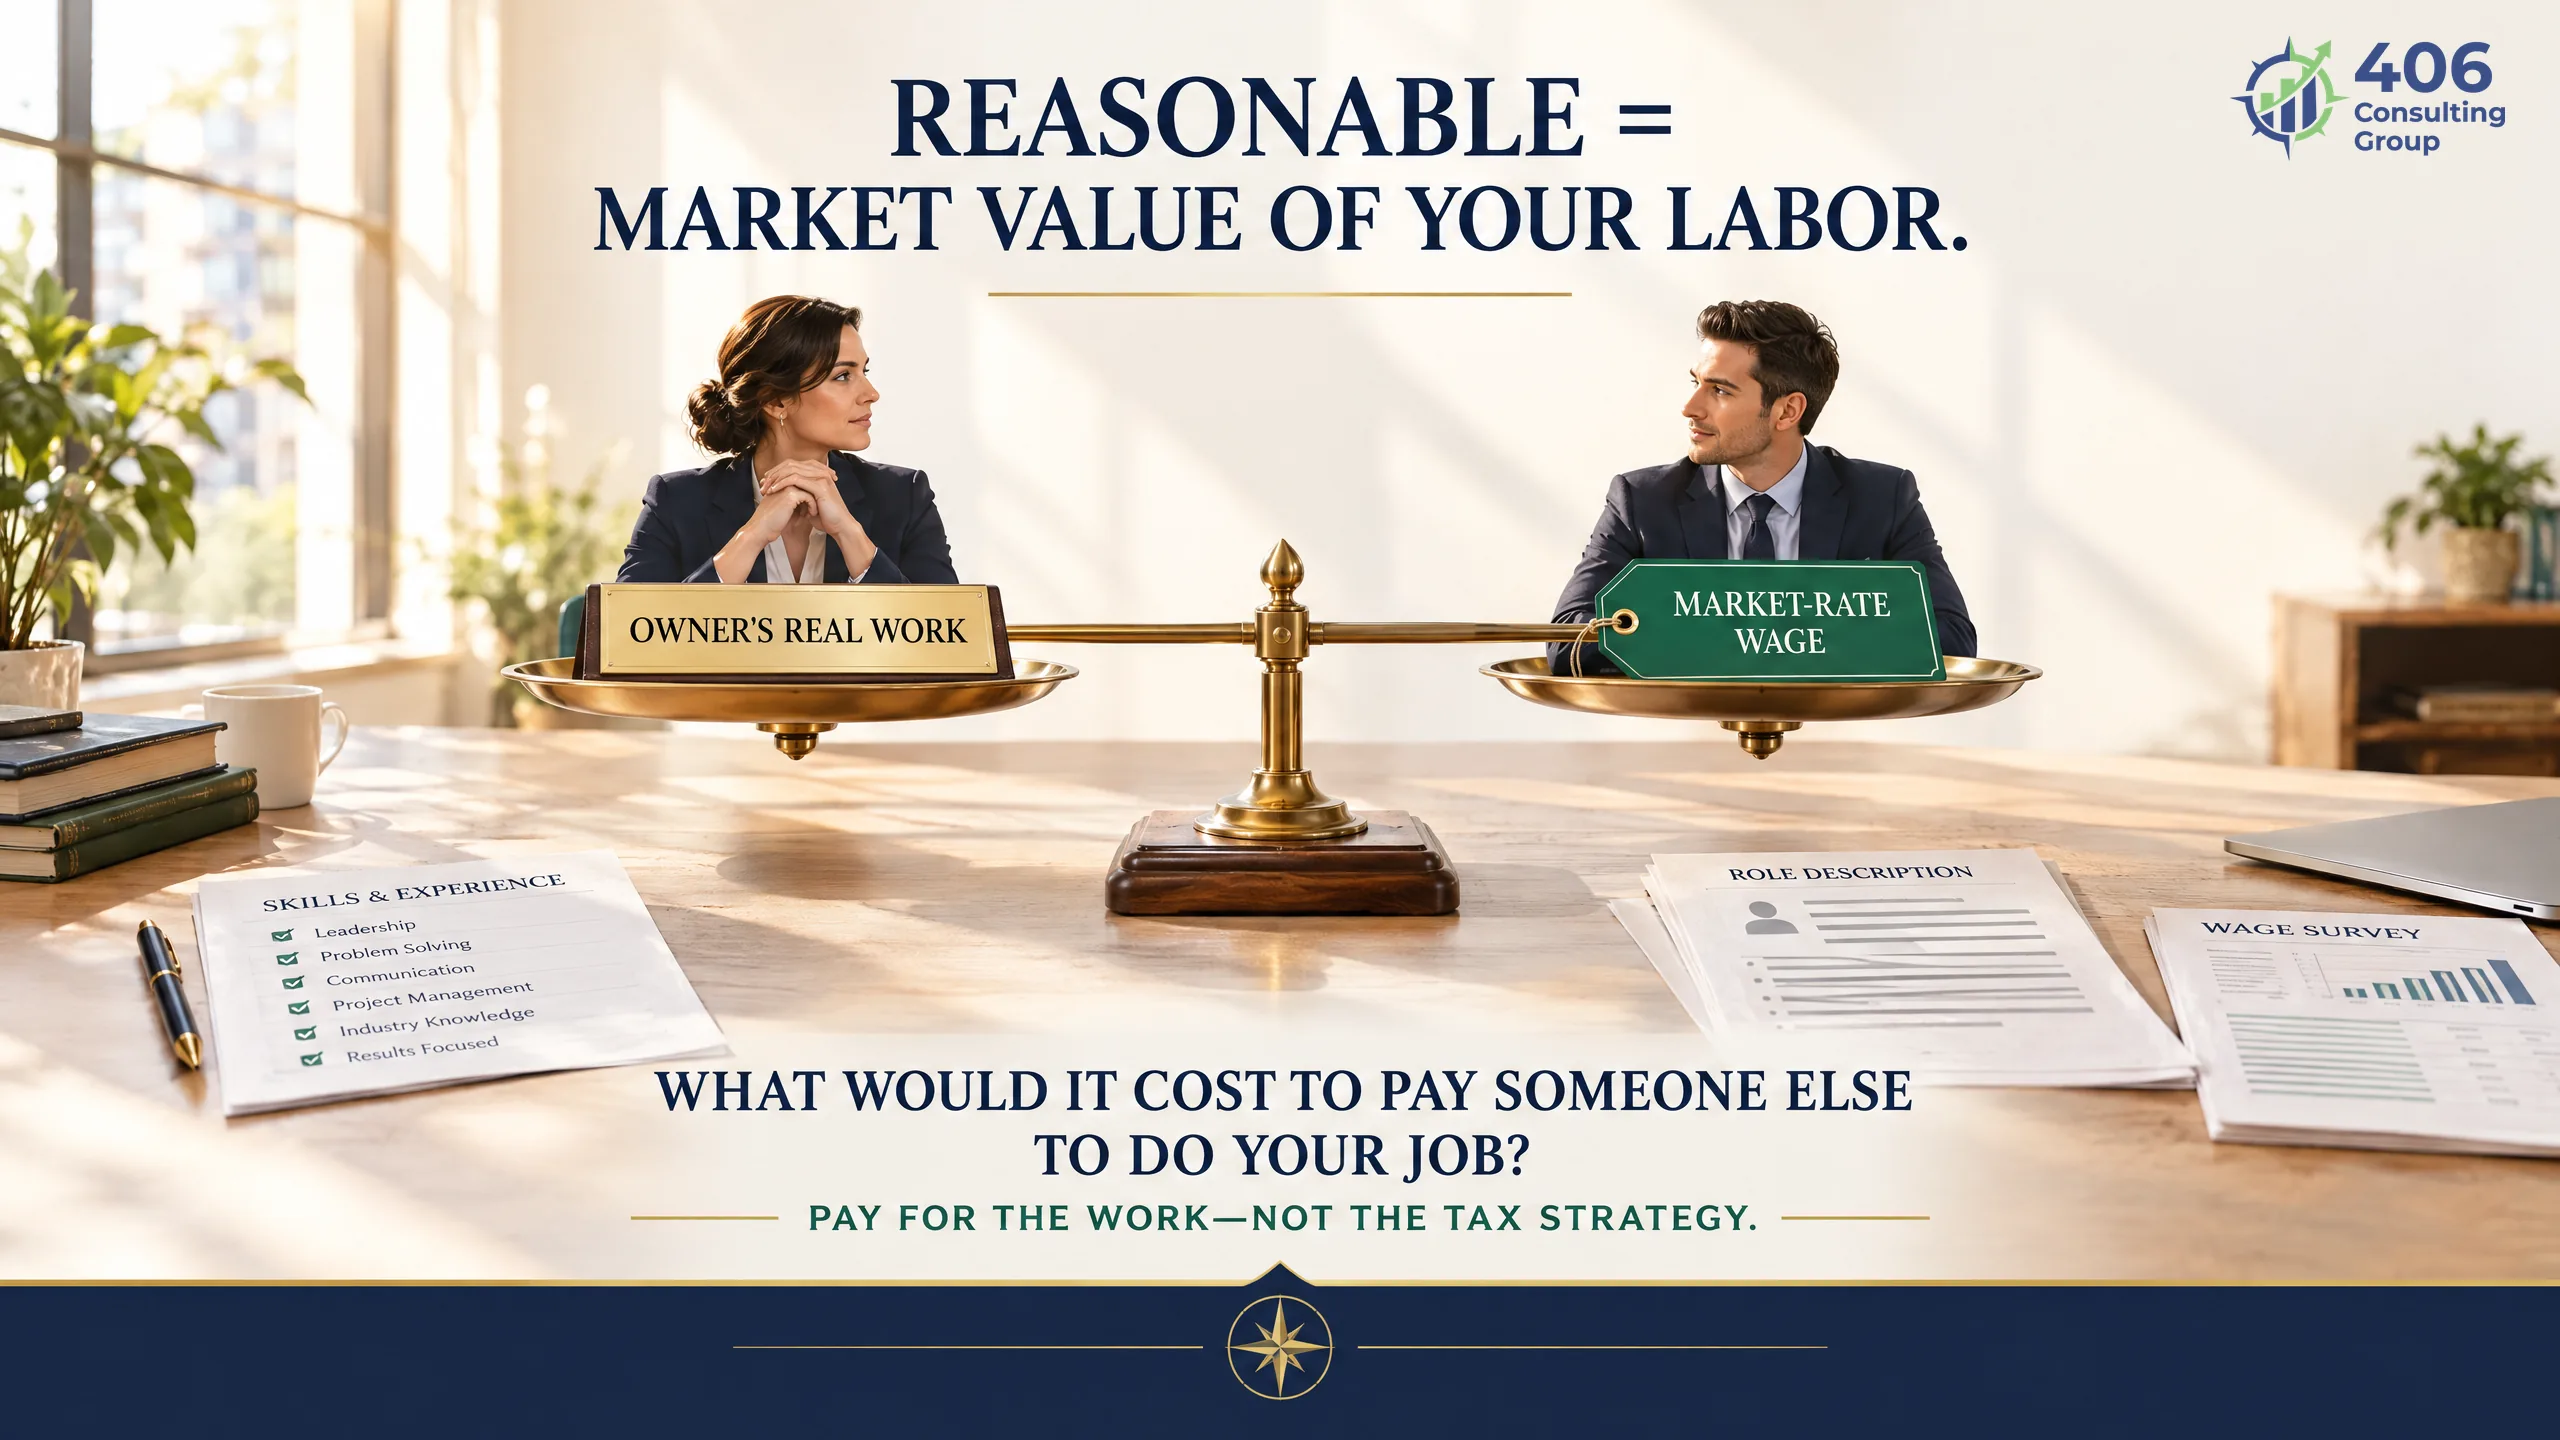
"Market value of your labor" is the idea. The IRS turns it into a set of factors.
The Factors That Decide It
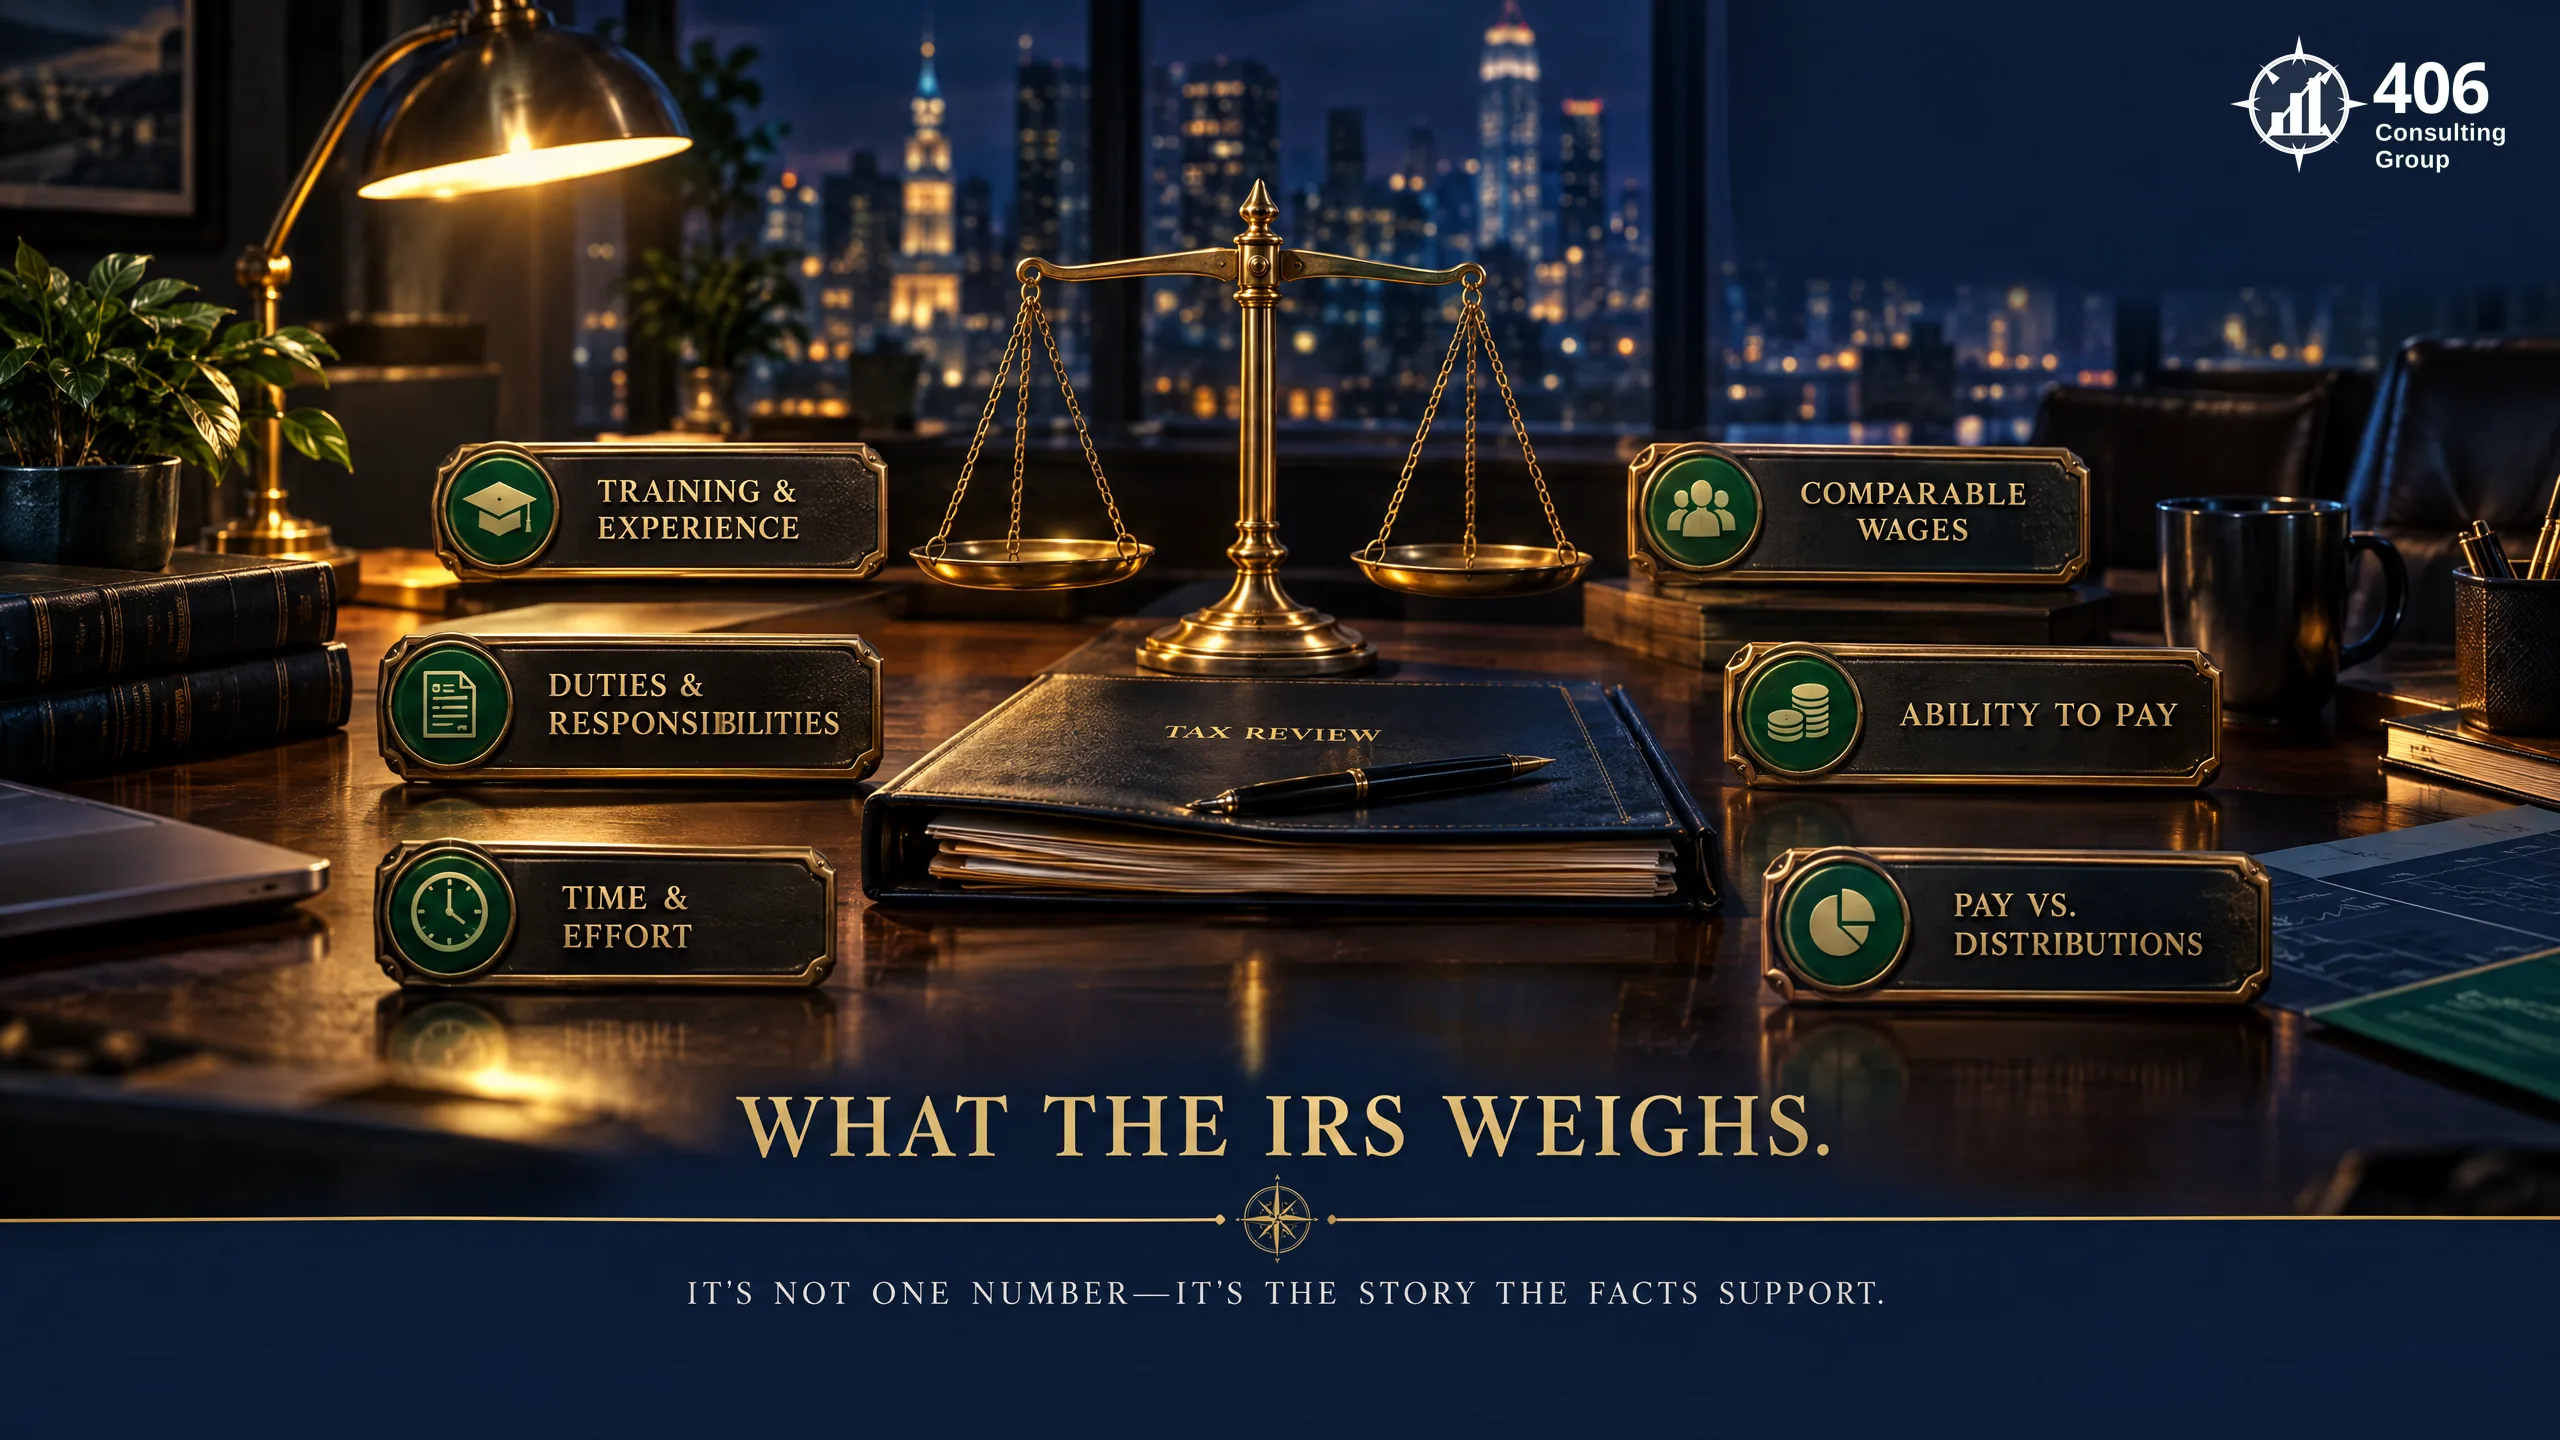
There's no single formula, but the IRS and the courts weigh a consistent set of factors when they judge whether a salary is reasonable. Knowing them tells you what to base your number on — and what to be ready to defend:
Training & experience
Your qualifications, licenses, and years in the trade — a licensed master plumber commands more than a helper.
Duties & responsibilities
What you actually do and how much the business rides on it — the more critical the role, the higher the pay.
Time & effort devoted
Full-time owner-operator vs. a few hours a week. Hours matter.
Comparable wages
What businesses like yours pay for the same work — real market data, by role and region.
What the business can pay
Compensation has to fit what the company reasonably earns and could afford for the role.
Pay vs. distributions
A tiny salary sitting next to large distributions is the pattern that draws scrutiny.
Those factors sound abstract until you turn them into a method. Here's how to actually build the number.
How to Set Your Number
There are a few defensible approaches, but they share a backbone: start from real market wage data for the work you do, then adjust for your specific situation. The gold-standard source is government wage data (the Bureau of Labor Statistics publishes median wages by occupation and region), which is exactly why a serious reasonable-comp analysis leans on it rather than on a gut feel. From there, the cleanest way to handle the fact that most owners do severaljobs is the "many hats" method.
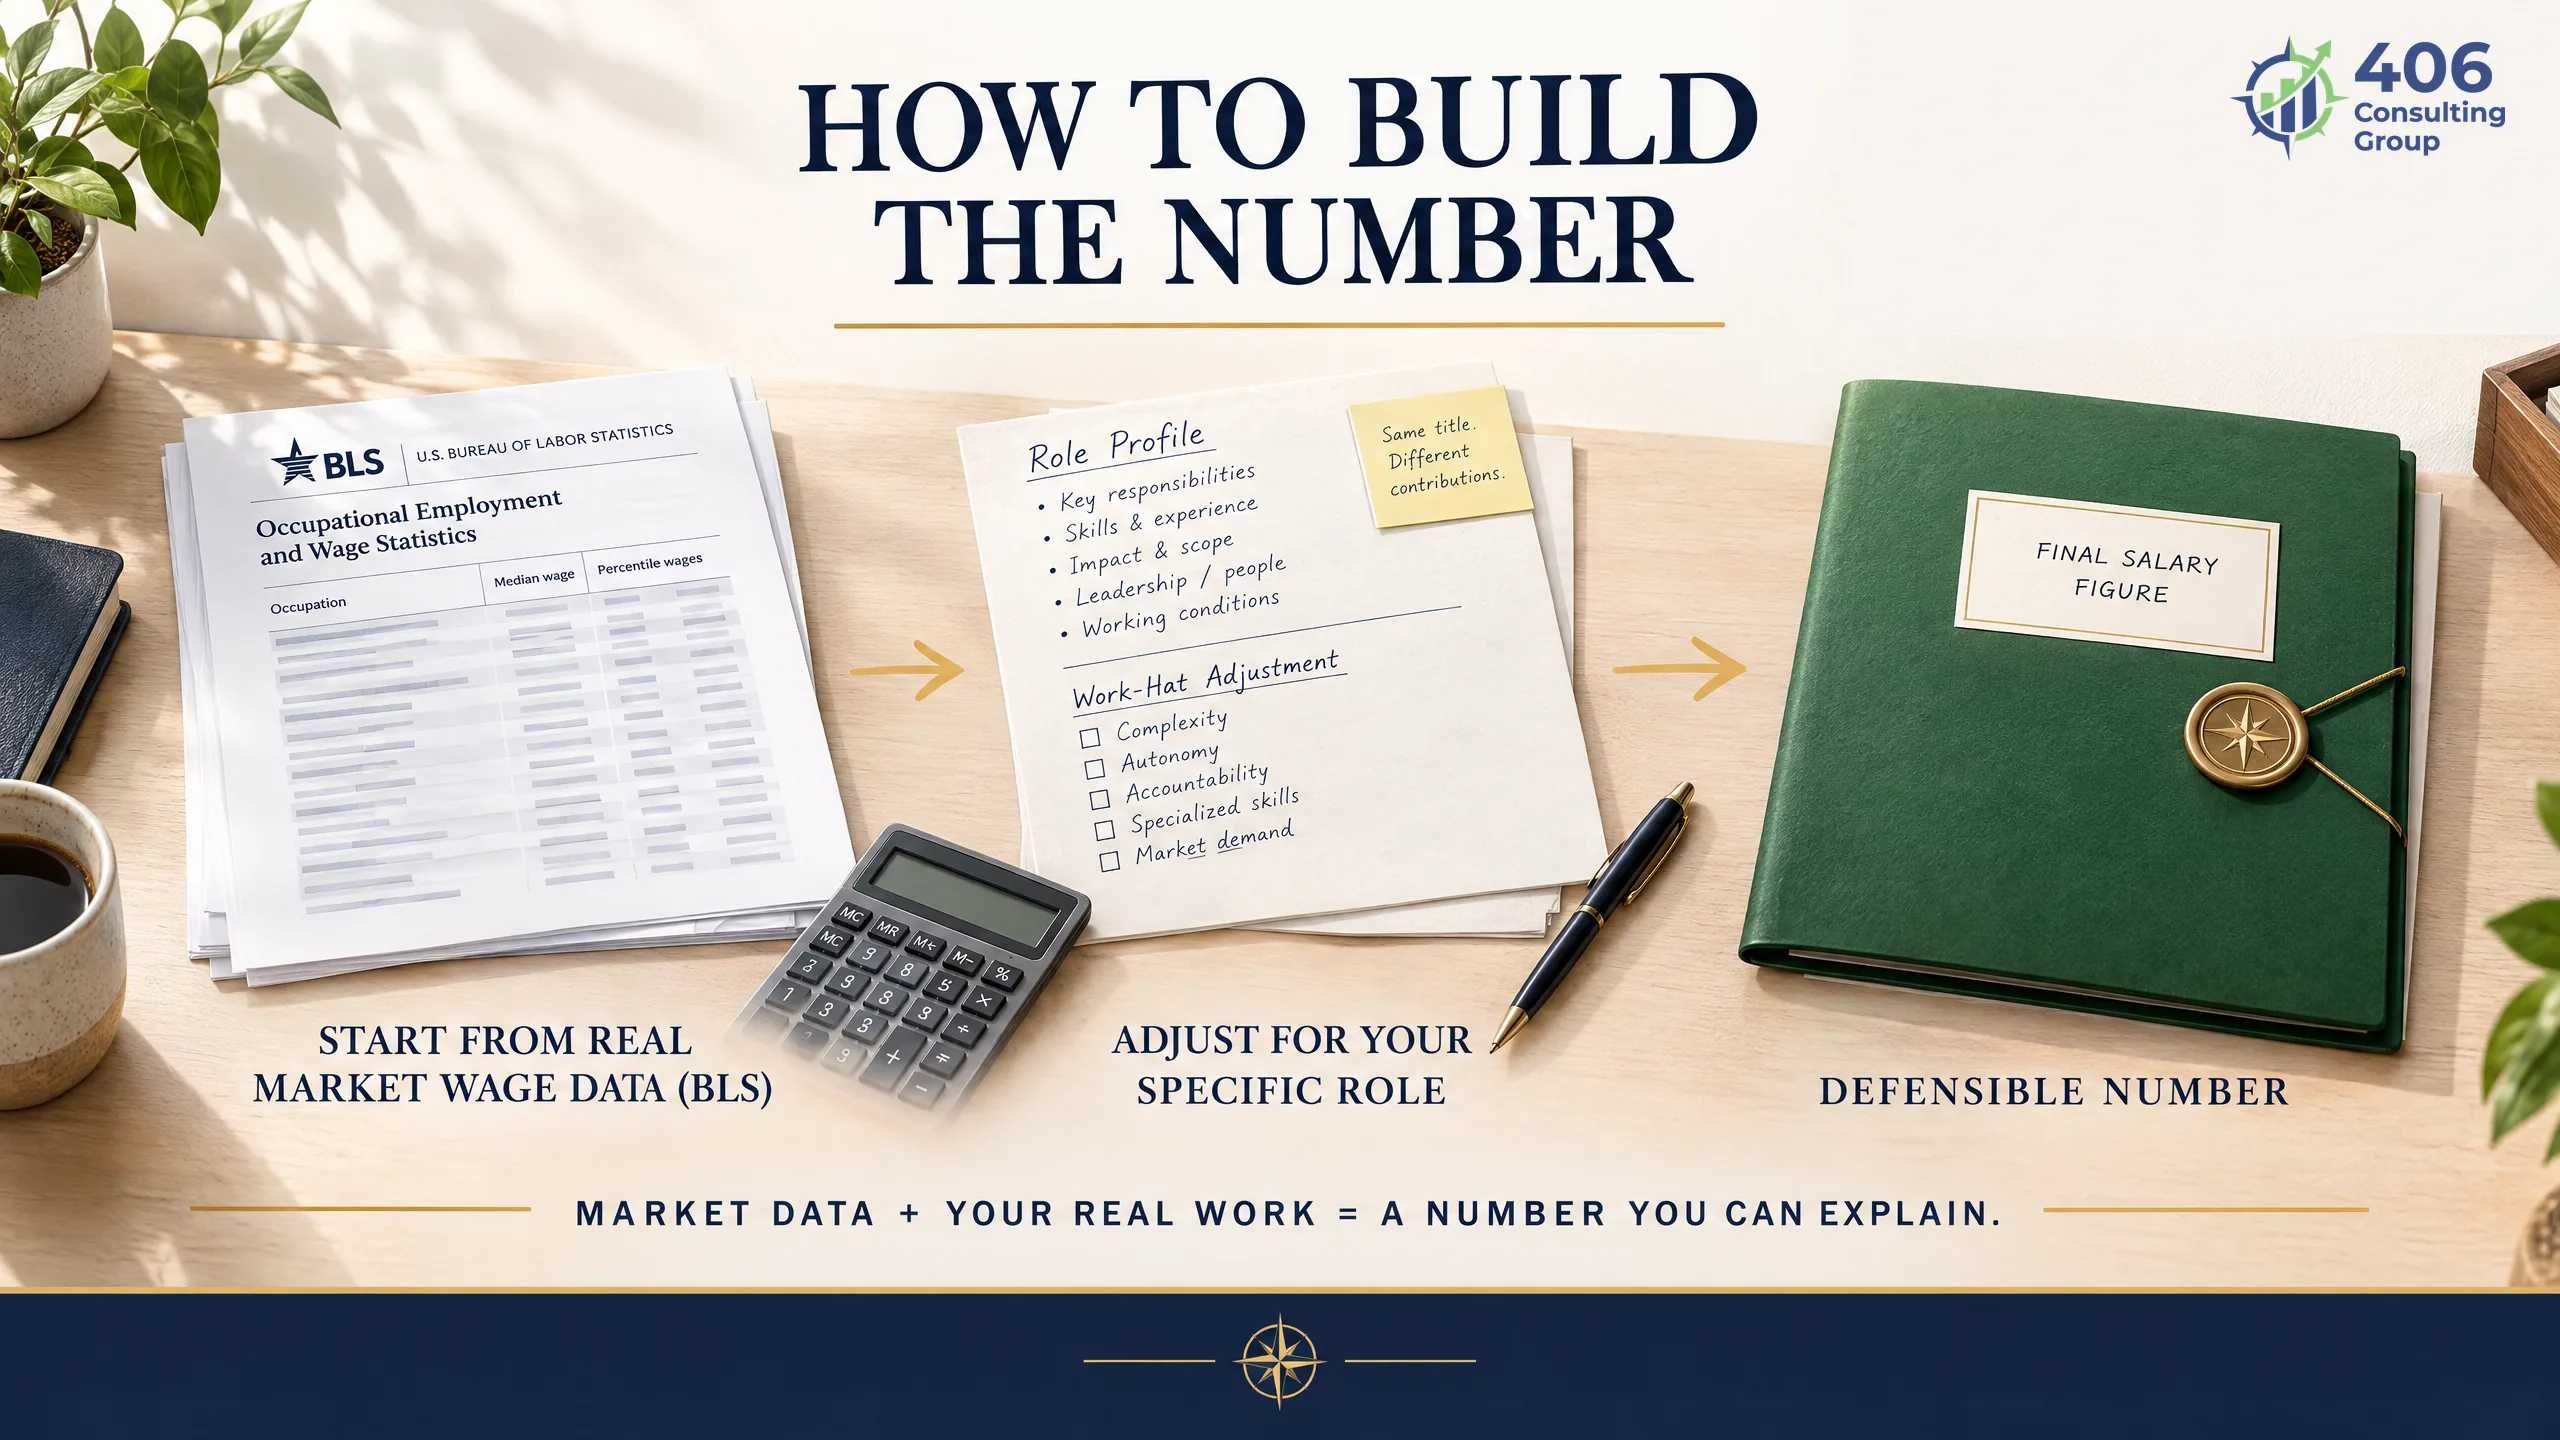
Let's run it for Sam, so you can see how a real number gets built.
The "Many Hats" Method, With Real Numbers
Sam doesn't do one job — he wears four hats. The method: estimate the share of his time in each role, find the market wage for each, and blend them. Here's Sam's year:
Hat Sam wears
% time
Market wage
Plumber / field technician
50%
$62,000
Operations / crew manager
20%
$85,000
Sales / estimating
20%
$70,000
Admin / bookkeeping
10%
$45,000
Blended reasonable salary
~$66,500
The math: (50% × $62K) + (20% × $85K) + (20% × $70K) + (10% × $45K) = $66,500. Notice it landed right near the $70,000 salary Sam used in the first article — that's not a coincidence, it's the point: the many-hats method producesa number you can stand behind, instead of reverse-engineering one you hope survives. It also captures something a flat percentage never could — that Sam's management and sales time is worth more per hour than his wrench time.
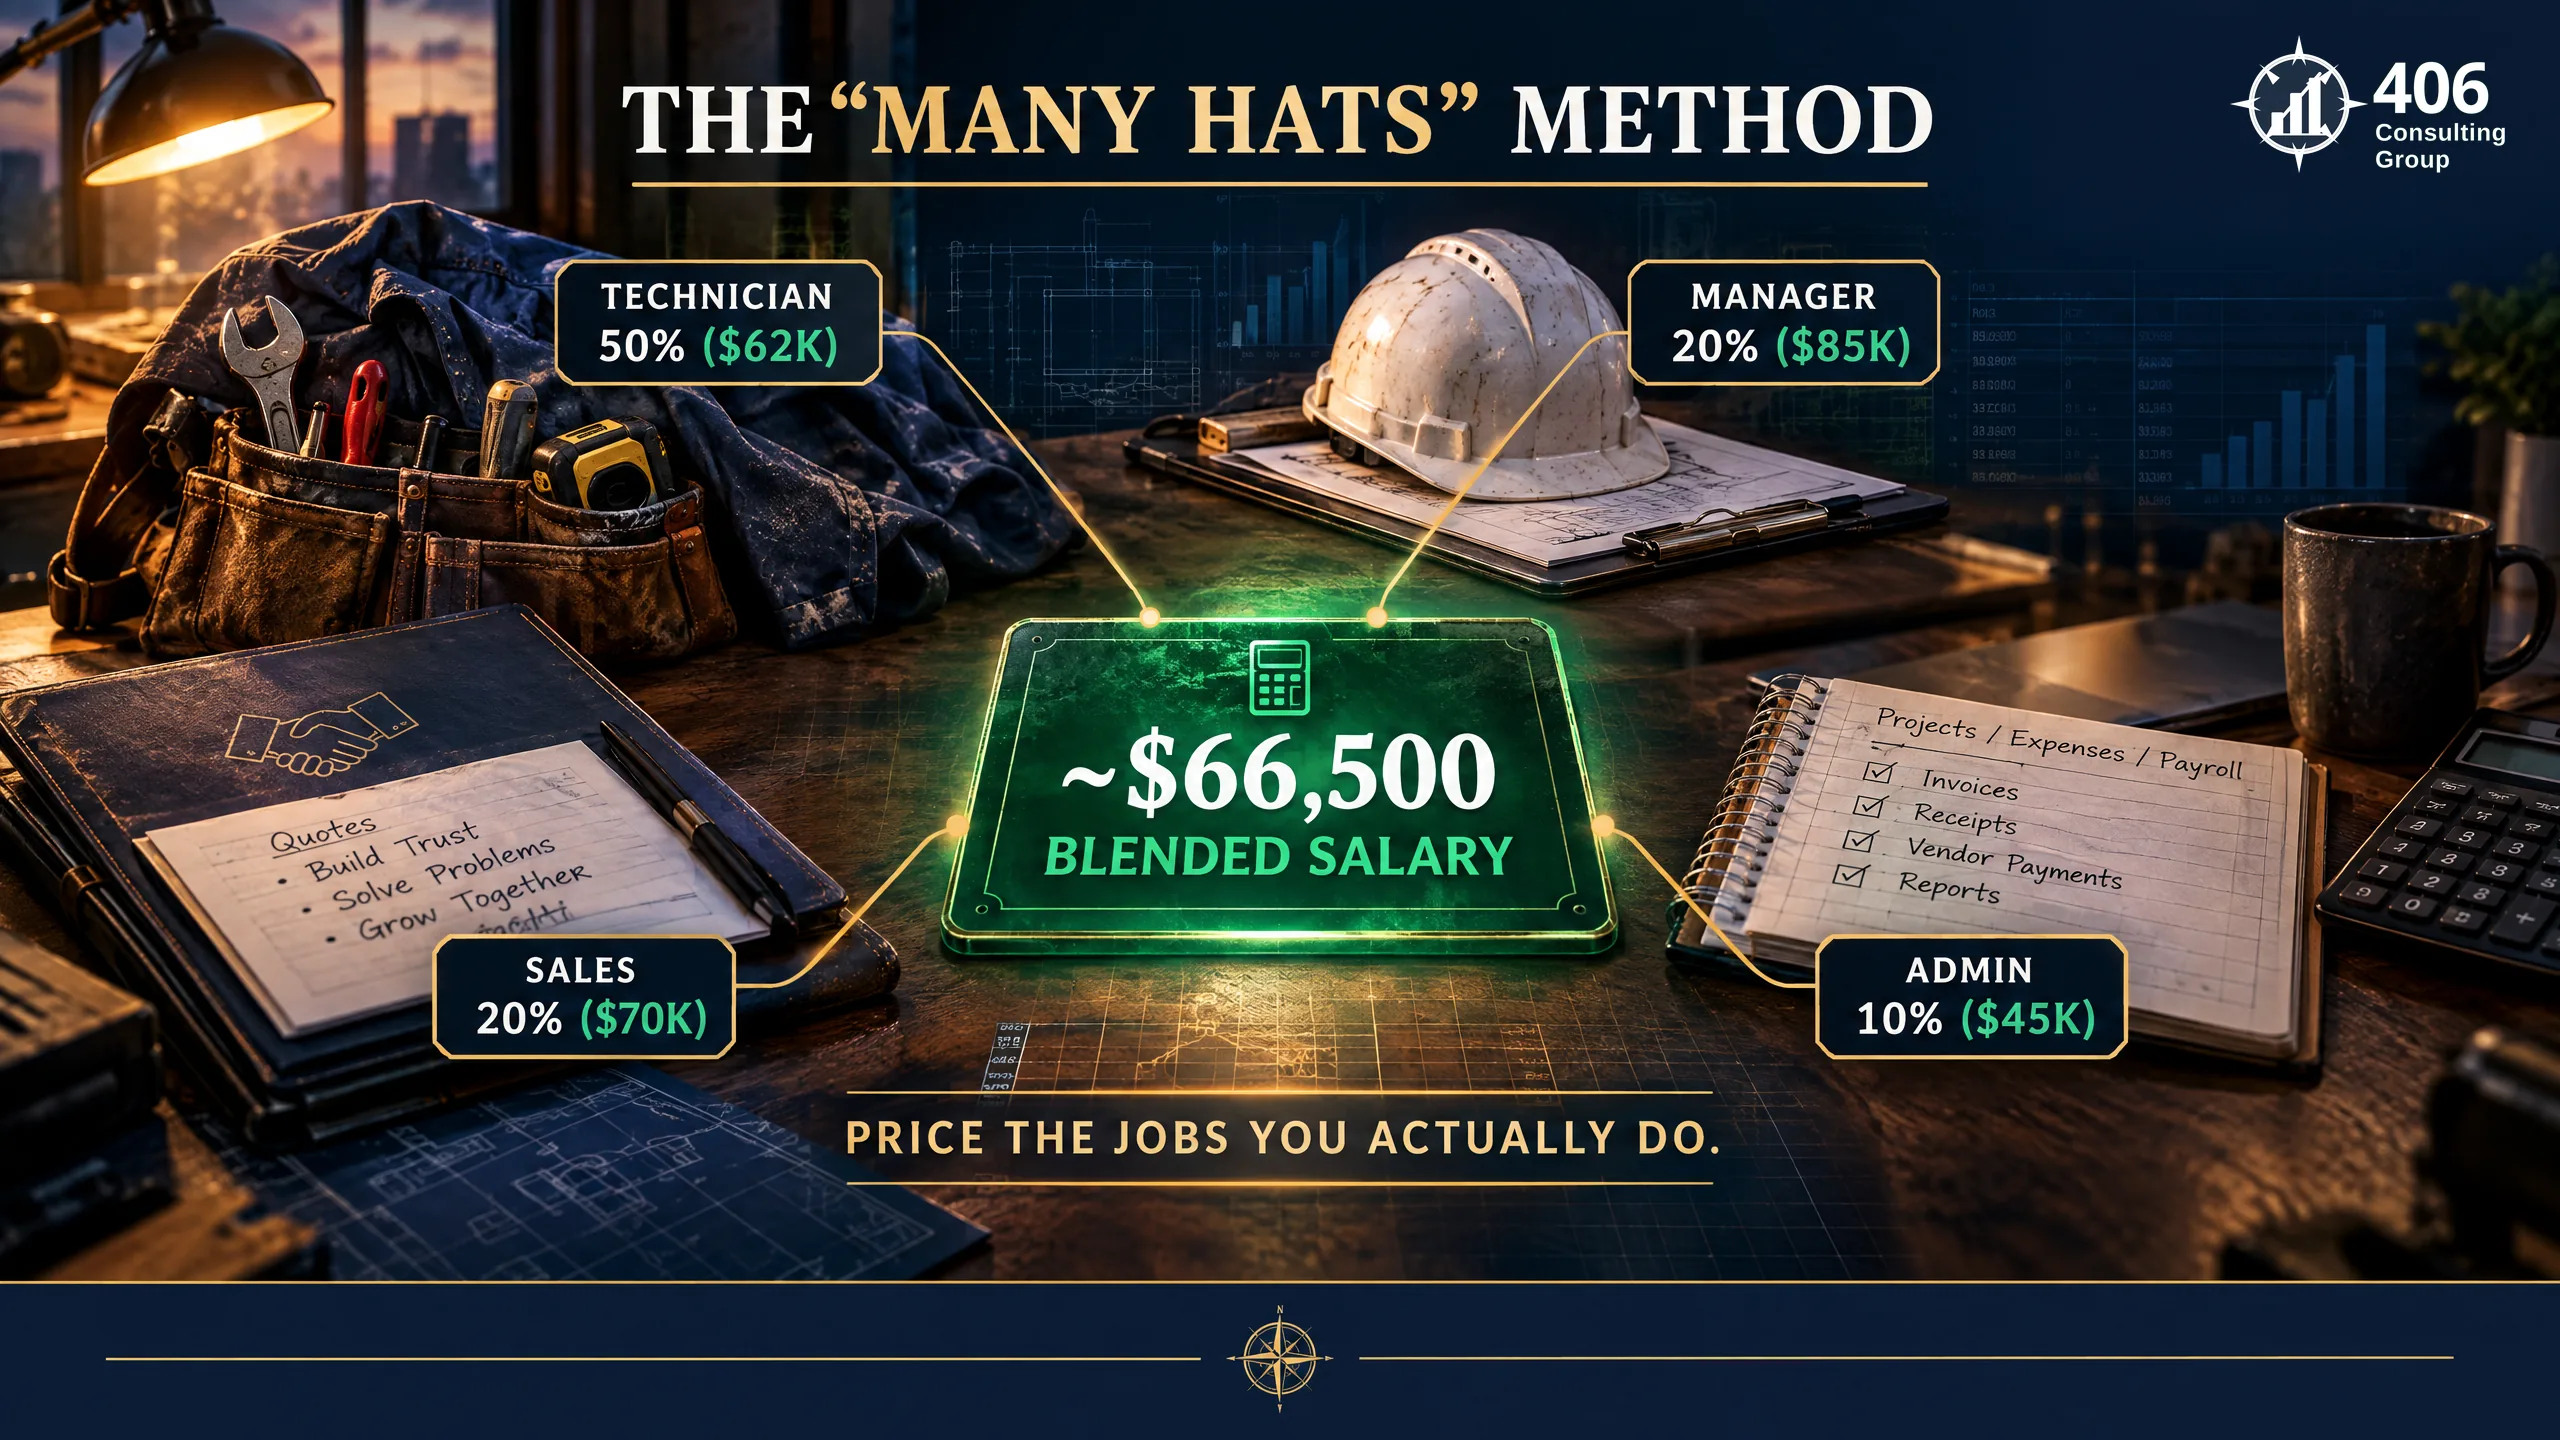
Our S-Corp reasonable-salary calculator does exactly this with live BLS wage data for your occupation and state. Which is a good moment to bury some myths that skip the method entirely.
The Myths That Get Owners Audited
The internet is full of tidy shortcuts for the salary number. Most are wrong, and some are actively dangerous:
Myth: "The 60/40 rule"
There is no IRS rule that says 60% salary / 40% distributions (or any fixed split). It's a made-up rule of thumb — your number depends on your actual roles and market, not a ratio.
Myth: "Just pay yourself $0"
An owner actively working in the business who takes no salary is the clearest audit target there is. Zero is not a strategy; it's an invitation.
Myth: "Match whatever I paid last year"
Your role changes as the business grows. A number that was reasonable at $80K of profit may not be at $250K — revisit it annually.
Myth: "Pick a round number that feels safe"
A guess with no data behind it is indefensible if questioned. 'It felt about right' is not a rationale the IRS accepts.
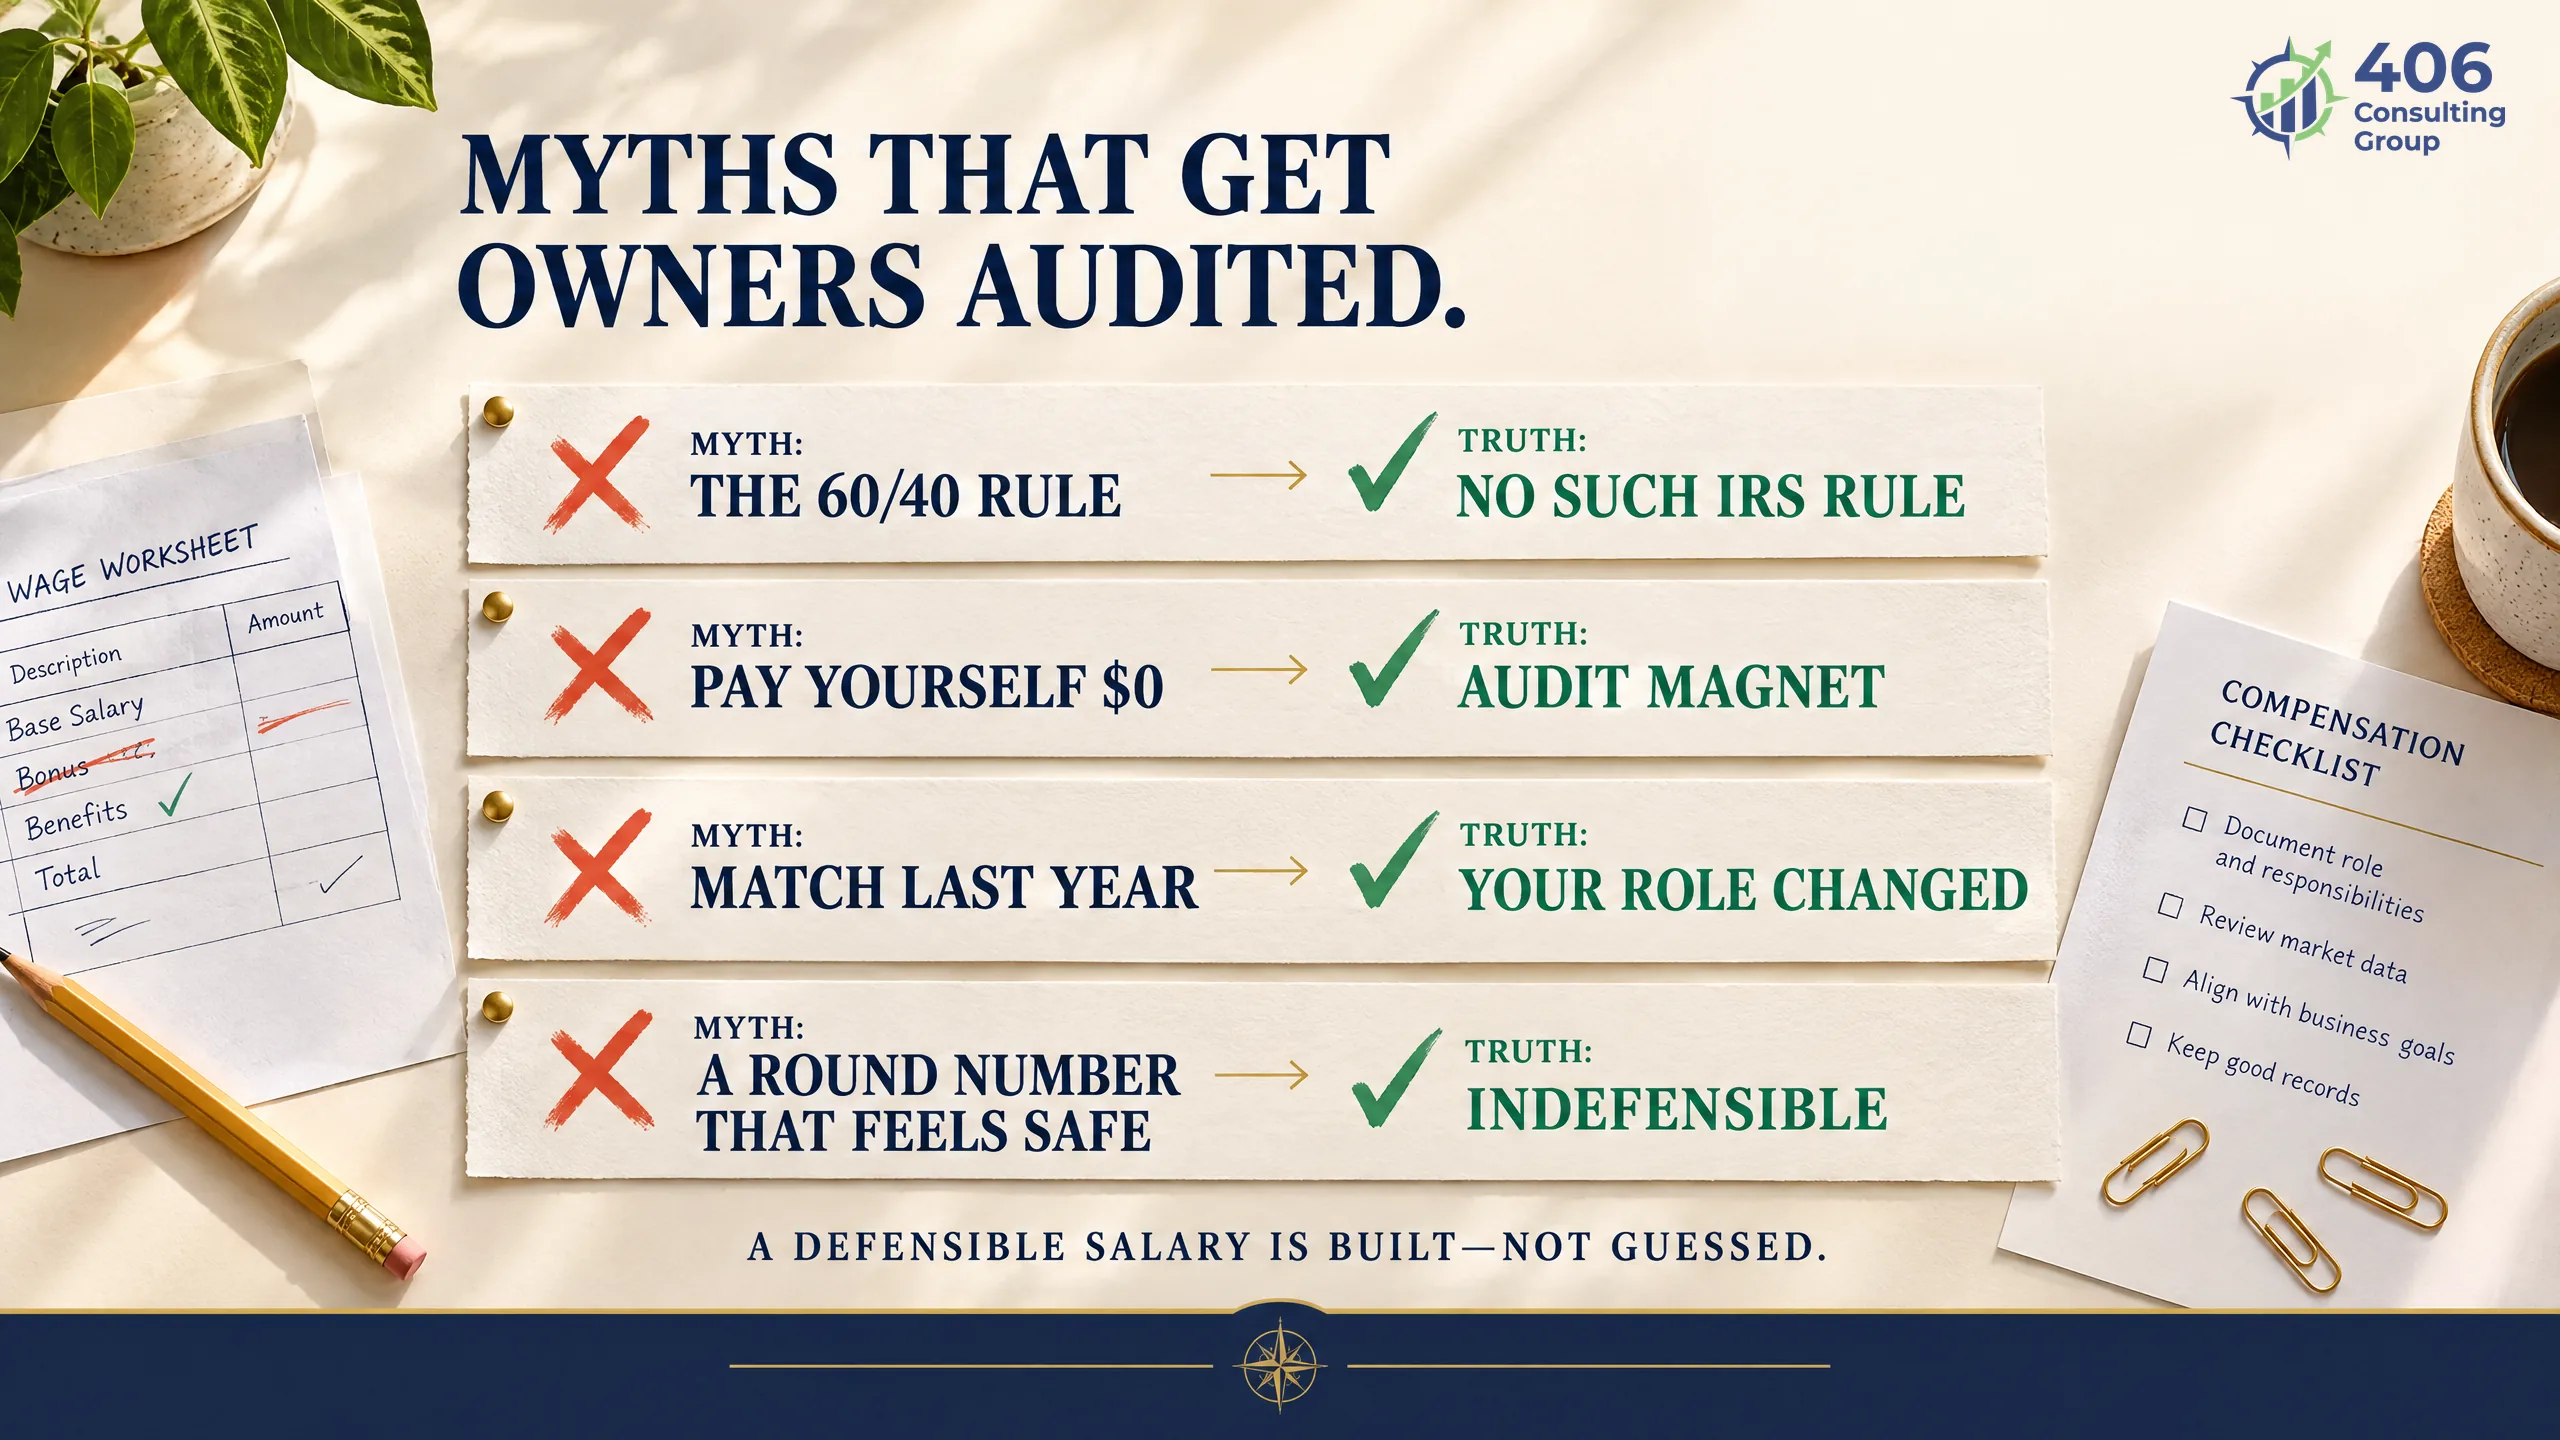
Why does all this matter so much? Because the downside is not theoretical.
What Happens If You Get It Wrong
If the IRS decides your salary was unreasonably low, it can reclassify your distributions as wages — and then the bill arrives. You owe the back payroll taxes on the reclassified amount (both the employer and employee shares of Social Security and Medicare), plus penalties and interest. Worse, once an auditor finds one problem, they tend to keep looking. The savings you reached for by lowballing the salary can be wiped out several times over — the classic case of a small tax dodge turning into a large, avoidable cost.
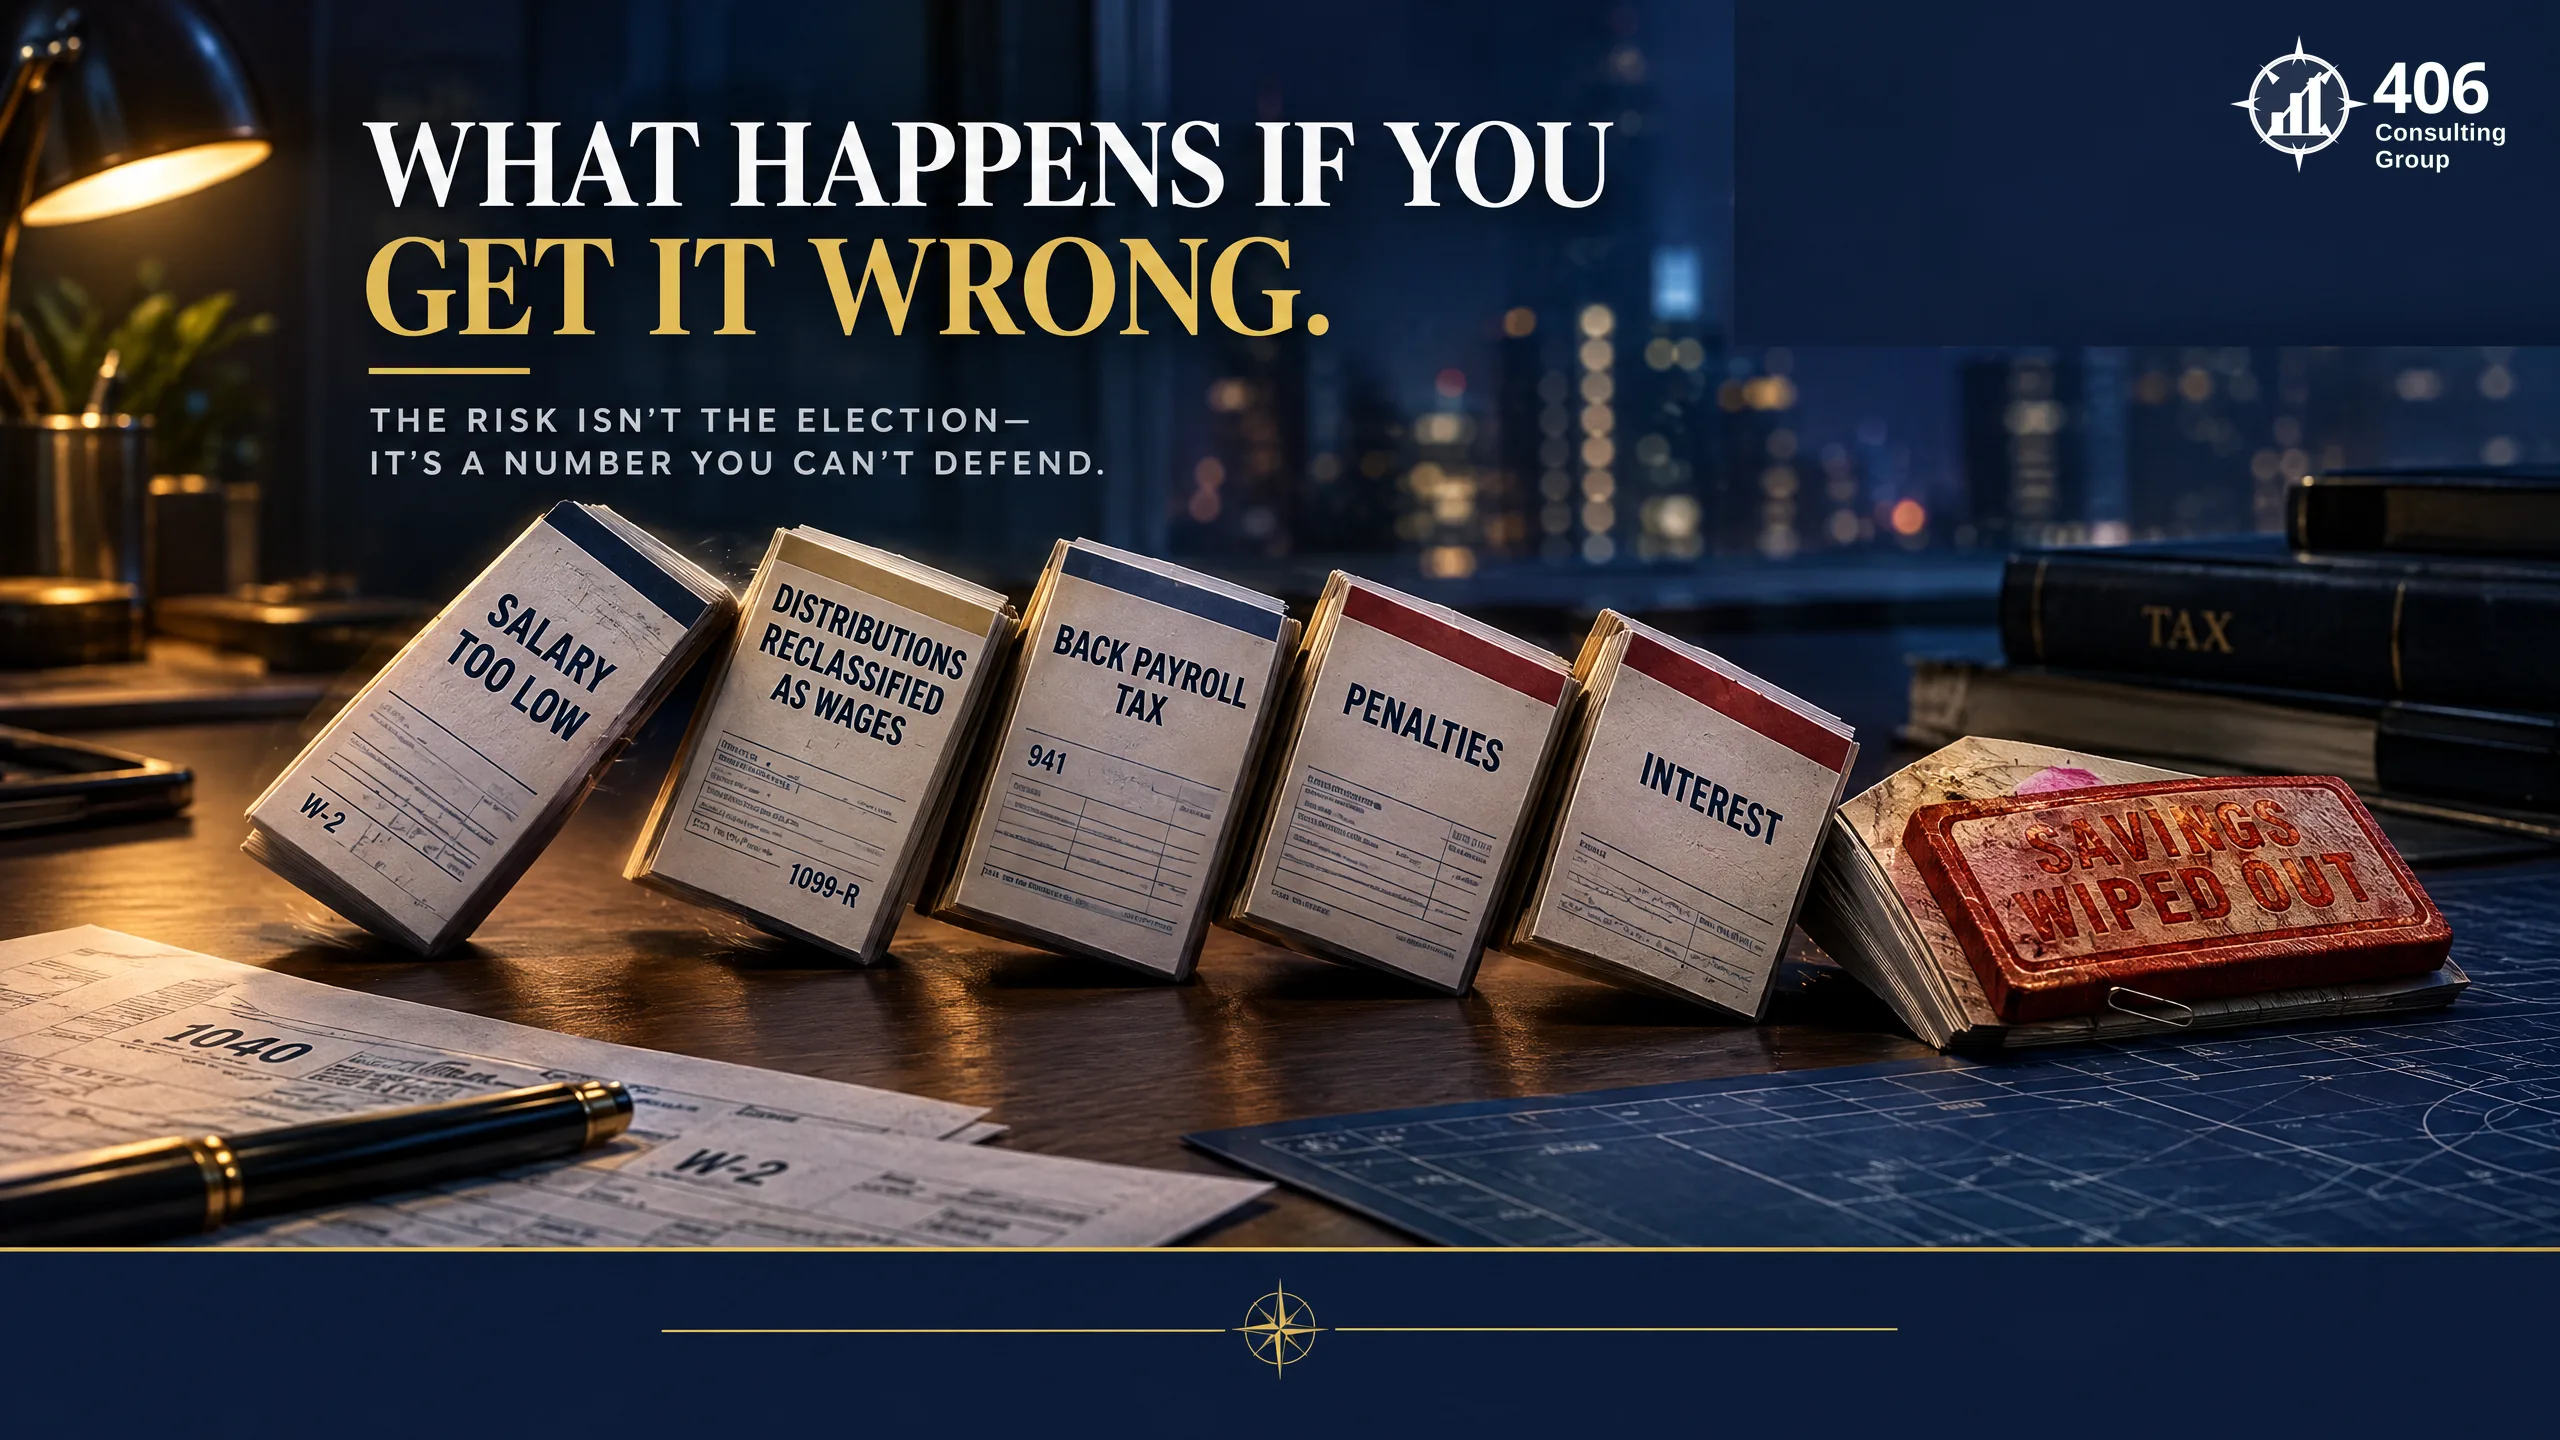
Lowballing the salary to save a few thousand can cost you far more in back taxes, penalties, and interest. The cheap number is often the expensive one.
The good news: a defensible number is only defensible if you can show your work — so show it.
Document It So It Holds Up
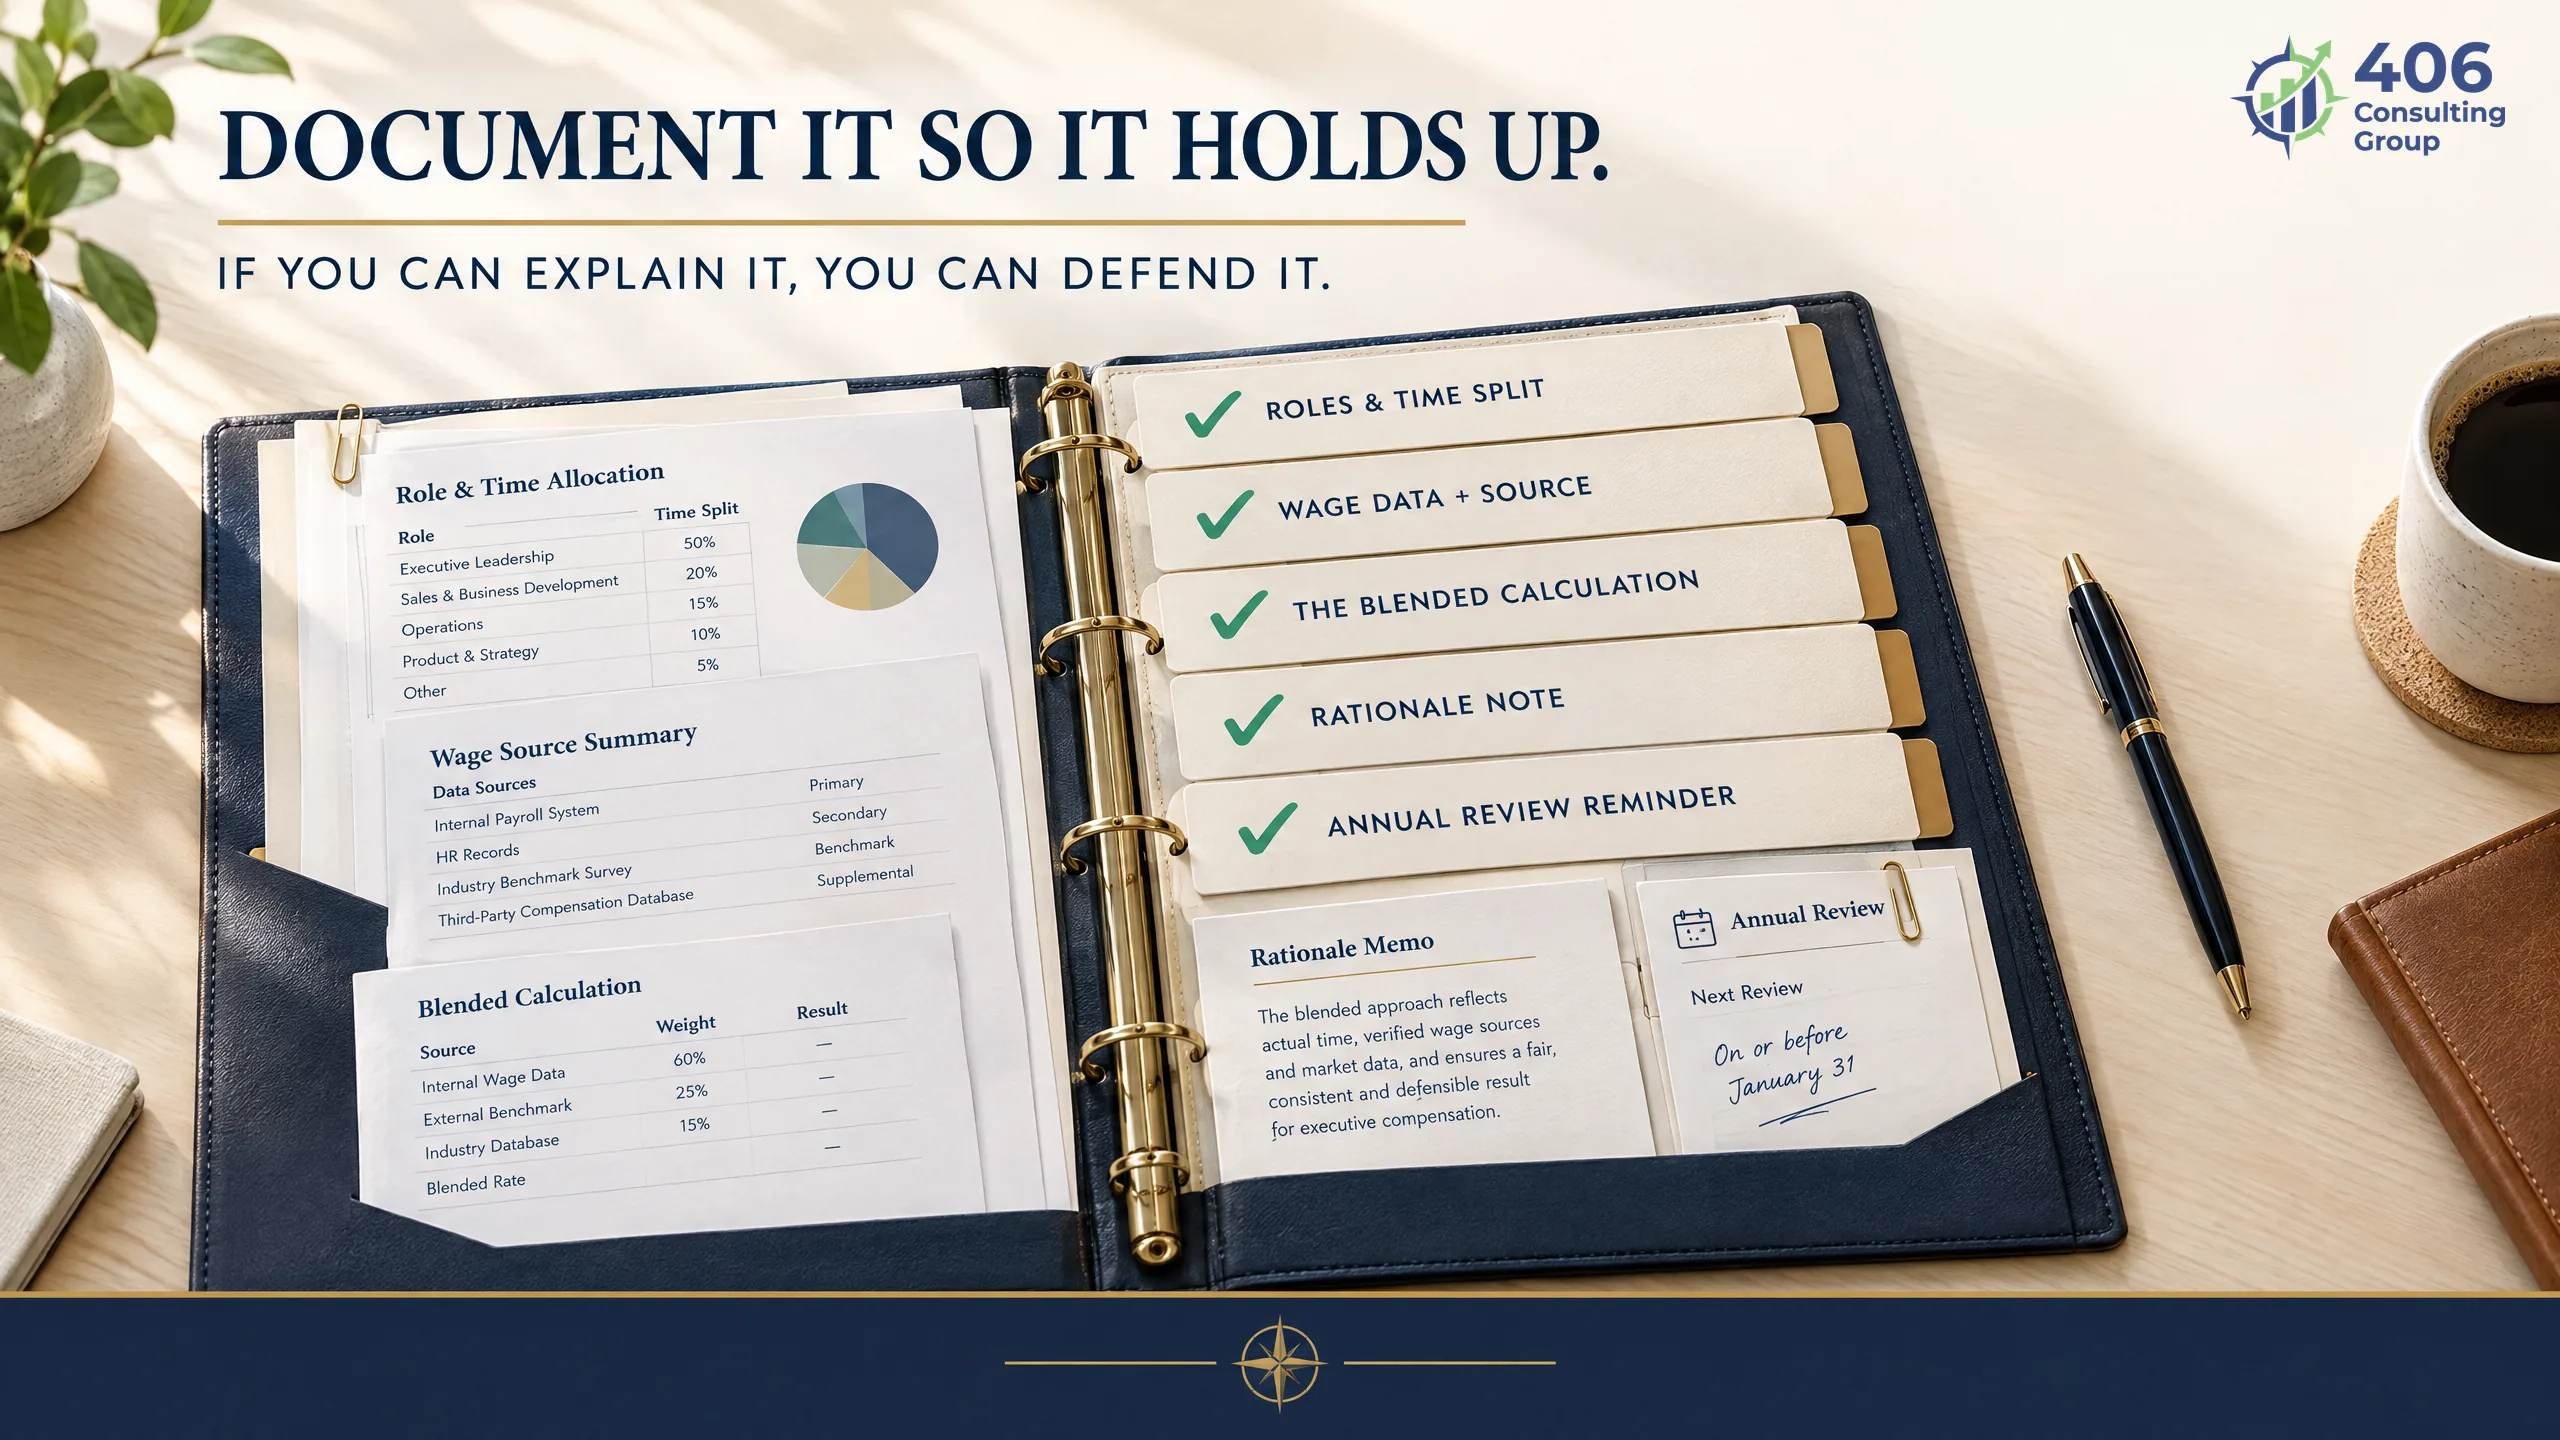
A reasonable salary you can't explain is a reasonable salary you can't defend. The fix is simple and cheap: keep a short file, made at the timeyou set the number, that shows how you got there. If you're ever questioned, that file turns an argument into a formality.
Keep this on file
- ✓The roles you fill and the share of time in each (your 'many hats' breakdown).
- ✓The market wage data you used for each role, with the source and date.
- ✓The blended salary calculation that produced your number.
- ✓A short note on why it fits your business — hours, duties, what the company can pay.
- ✓A calendar reminder to revisit it each year as your role and profit change.
Method plus documentation is the whole defense. Here's the fastest way to get both.
Get Your Number Right
You don't have to guess, and you definitely shouldn't. Start with the calculator to build a defensible, market-based number from real wage data — then, if you want it set, documented, and backed by the payroll to match, that's exactly what we do.
Build a salary you can defend.
Use the free reasonable-salary calculator to get your number from live BLS wage data — then let us set it, document the rationale, and run the S-corp payroll behind it, so the savings stick and the audit risk doesn't.
Still deciding whether to elect at all? Start with Should You Elect S-Corp? The Real Math. Already elected and wondering about timing? See The S-Corp Election Deadline.
FAQ: S-Corp Reasonable Salary
What is a reasonable salary for an S-corp owner?
A reasonable salary is reasonable pay for the work you actually do in the business — essentially what you'd have to pay someone else to do your job at market rates. The IRS requires an owner who works in the business to take this salary through payroll before taking tax-favored distributions. It's based on your specific role: your training and experience, your duties, the time you devote, and comparable wages for that work in your area. It is not a percentage of profit, last year's number, or the least you can get away with — it's the market value of your labor, ideally built from real wage data.
Is there a 60/40 rule for S-corp salary?
No. There is no IRS rule that says pay yourself 60% as salary and 40% as distributions, or any other fixed ratio. The '60/40 rule' is an internet myth. Your reasonable salary depends on the actual work you do and its market value, not on a percentage of profit or distributions. Two owners with the same profit can have very different reasonable salaries because they do different work. Relying on a made-up ratio instead of a real analysis is exactly the kind of shortcut that doesn't hold up if the IRS asks how you arrived at your number.
How do I calculate my reasonable salary?
The cleanest method is the 'many hats' approach: list the roles you actually fill (for example, technician, manager, sales, admin), estimate the share of your time in each, find the market wage for each role using real data like the Bureau of Labor Statistics, and blend them weighted by time. For a contractor who spends 50% of his time on field work, 20% managing, 20% on sales, and 10% on admin, the blended figure comes out around $66,500 — and it's defensible because every piece traces back to real wage data. Our S-Corp reasonable-salary calculator runs this automatically using live BLS data for your occupation and state.
What happens if my S-corp salary is too low?
If the IRS decides your salary was unreasonably low, it can reclassify some or all of your distributions as wages. You then owe the back payroll taxes on that amount — both the employer and employee shares of Social Security and Medicare — plus penalties and interest. An unreasonably low owner salary is a well-known audit trigger, and once an audit starts, examiners tend to keep looking. In practice, the savings you tried to grab by lowballing the salary can be wiped out several times over, which is why a defensible, documented number matters so much.
How often should I review my reasonable salary?
At least once a year, and any time your role in the business changes significantly. Your reasonable salary should reflect what you're actually doing today, not what you did three years ago — as a business grows, owners often shift from doing the work to running the company, and the mix of roles (and their market value) changes with it. Reviewing it annually, and keeping a short file that documents the analysis each year, keeps the number defensible and prevents an old figure from quietly becoming unreasonable.
Can 406 Consulting Group set and defend my reasonable salary?
Yes. We build your reasonable-salary number from real market wage data using the many-hats method, document the rationale so it holds up if questioned, and run the S-corp payroll behind it so the salary is actually paid correctly through the year. Because the whole S-corp strategy lives or dies on this number, having one firm set the salary, document it, and run the payroll together is how you capture the savings without creating audit risk. Start with the calculator to see your number, then talk to us to make it official.
Sam's Many Hats
How the salary gets built
Illustrative. Your number depends on your roles + market.
Get Your Number
Free, from real BLS data.
About the Author
Jason Anderson
Co-Founder, 406 Consulting Group
Big-firm-trained accountant who sets and defends reasonable-salary numbers for S-corp owners — built from real wage data, documented to hold up, and backed by the payroll to match. Delivered remotely.
Read the Full Story