
Should You Elect S-Corp?
The Real Math
The S-corp election is the most valuable tax move most profitable small businesses can make — and the most misunderstood. The actual math: how the savings work, the profit where it starts to pay, the reasonable-salary catch, and when NOT to do it.
Meet Sam. Sam runs a contracting business as an LLC and nets about $150,000a year. Sam's been hearing the same thing at every job site and every backyard barbecue: "You need to be an S-corp — you're leaving money on the table." Sam has no idea if that's true, how much money, or what an "S-corp" even is. If that's you too, you're in the right place. The S-corp election is genuinely the single most valuable tax move most profitable small businesses can make — and it's also the most misunderstood, oversold, and botched. So let's do the actual math.
By the end of this you'll know exactly what the election does, roughly what it would save you, the profit level where it starts to pay, the one rule that trips everyone up, and when you should not do it. Plain English, real numbers.
By Jason Anderson — Co-Founder, 406 Consulting Group. Big-firm-trained accountant who has run this exact math for hundreds of owners — and handles the election and the payroll that has to come with it. Illustrative figures below; your numbers depend on your specifics.
Quick Answer: Should You Elect S-Corp?
- →The election lets you split profit into a salary and distributions — and distributions escape the ~15.3% self-employment tax.
- →It typically starts paying once profit consistently clears roughly $80,000–$100,000; below that, the costs usually win.
- →The catch: you must first pay yourself a "reasonable salary" — you can't zero it out, and the IRS watches this.
- →Real savings = gross savings minus payroll admin, an extra tax return, and any state costs.
- →Run your numbers with the S-Corp calculator before you decide — the answer depends on your profit and your salary.
Table of Contents
The Move That Saves the Most — and Confuses the Most
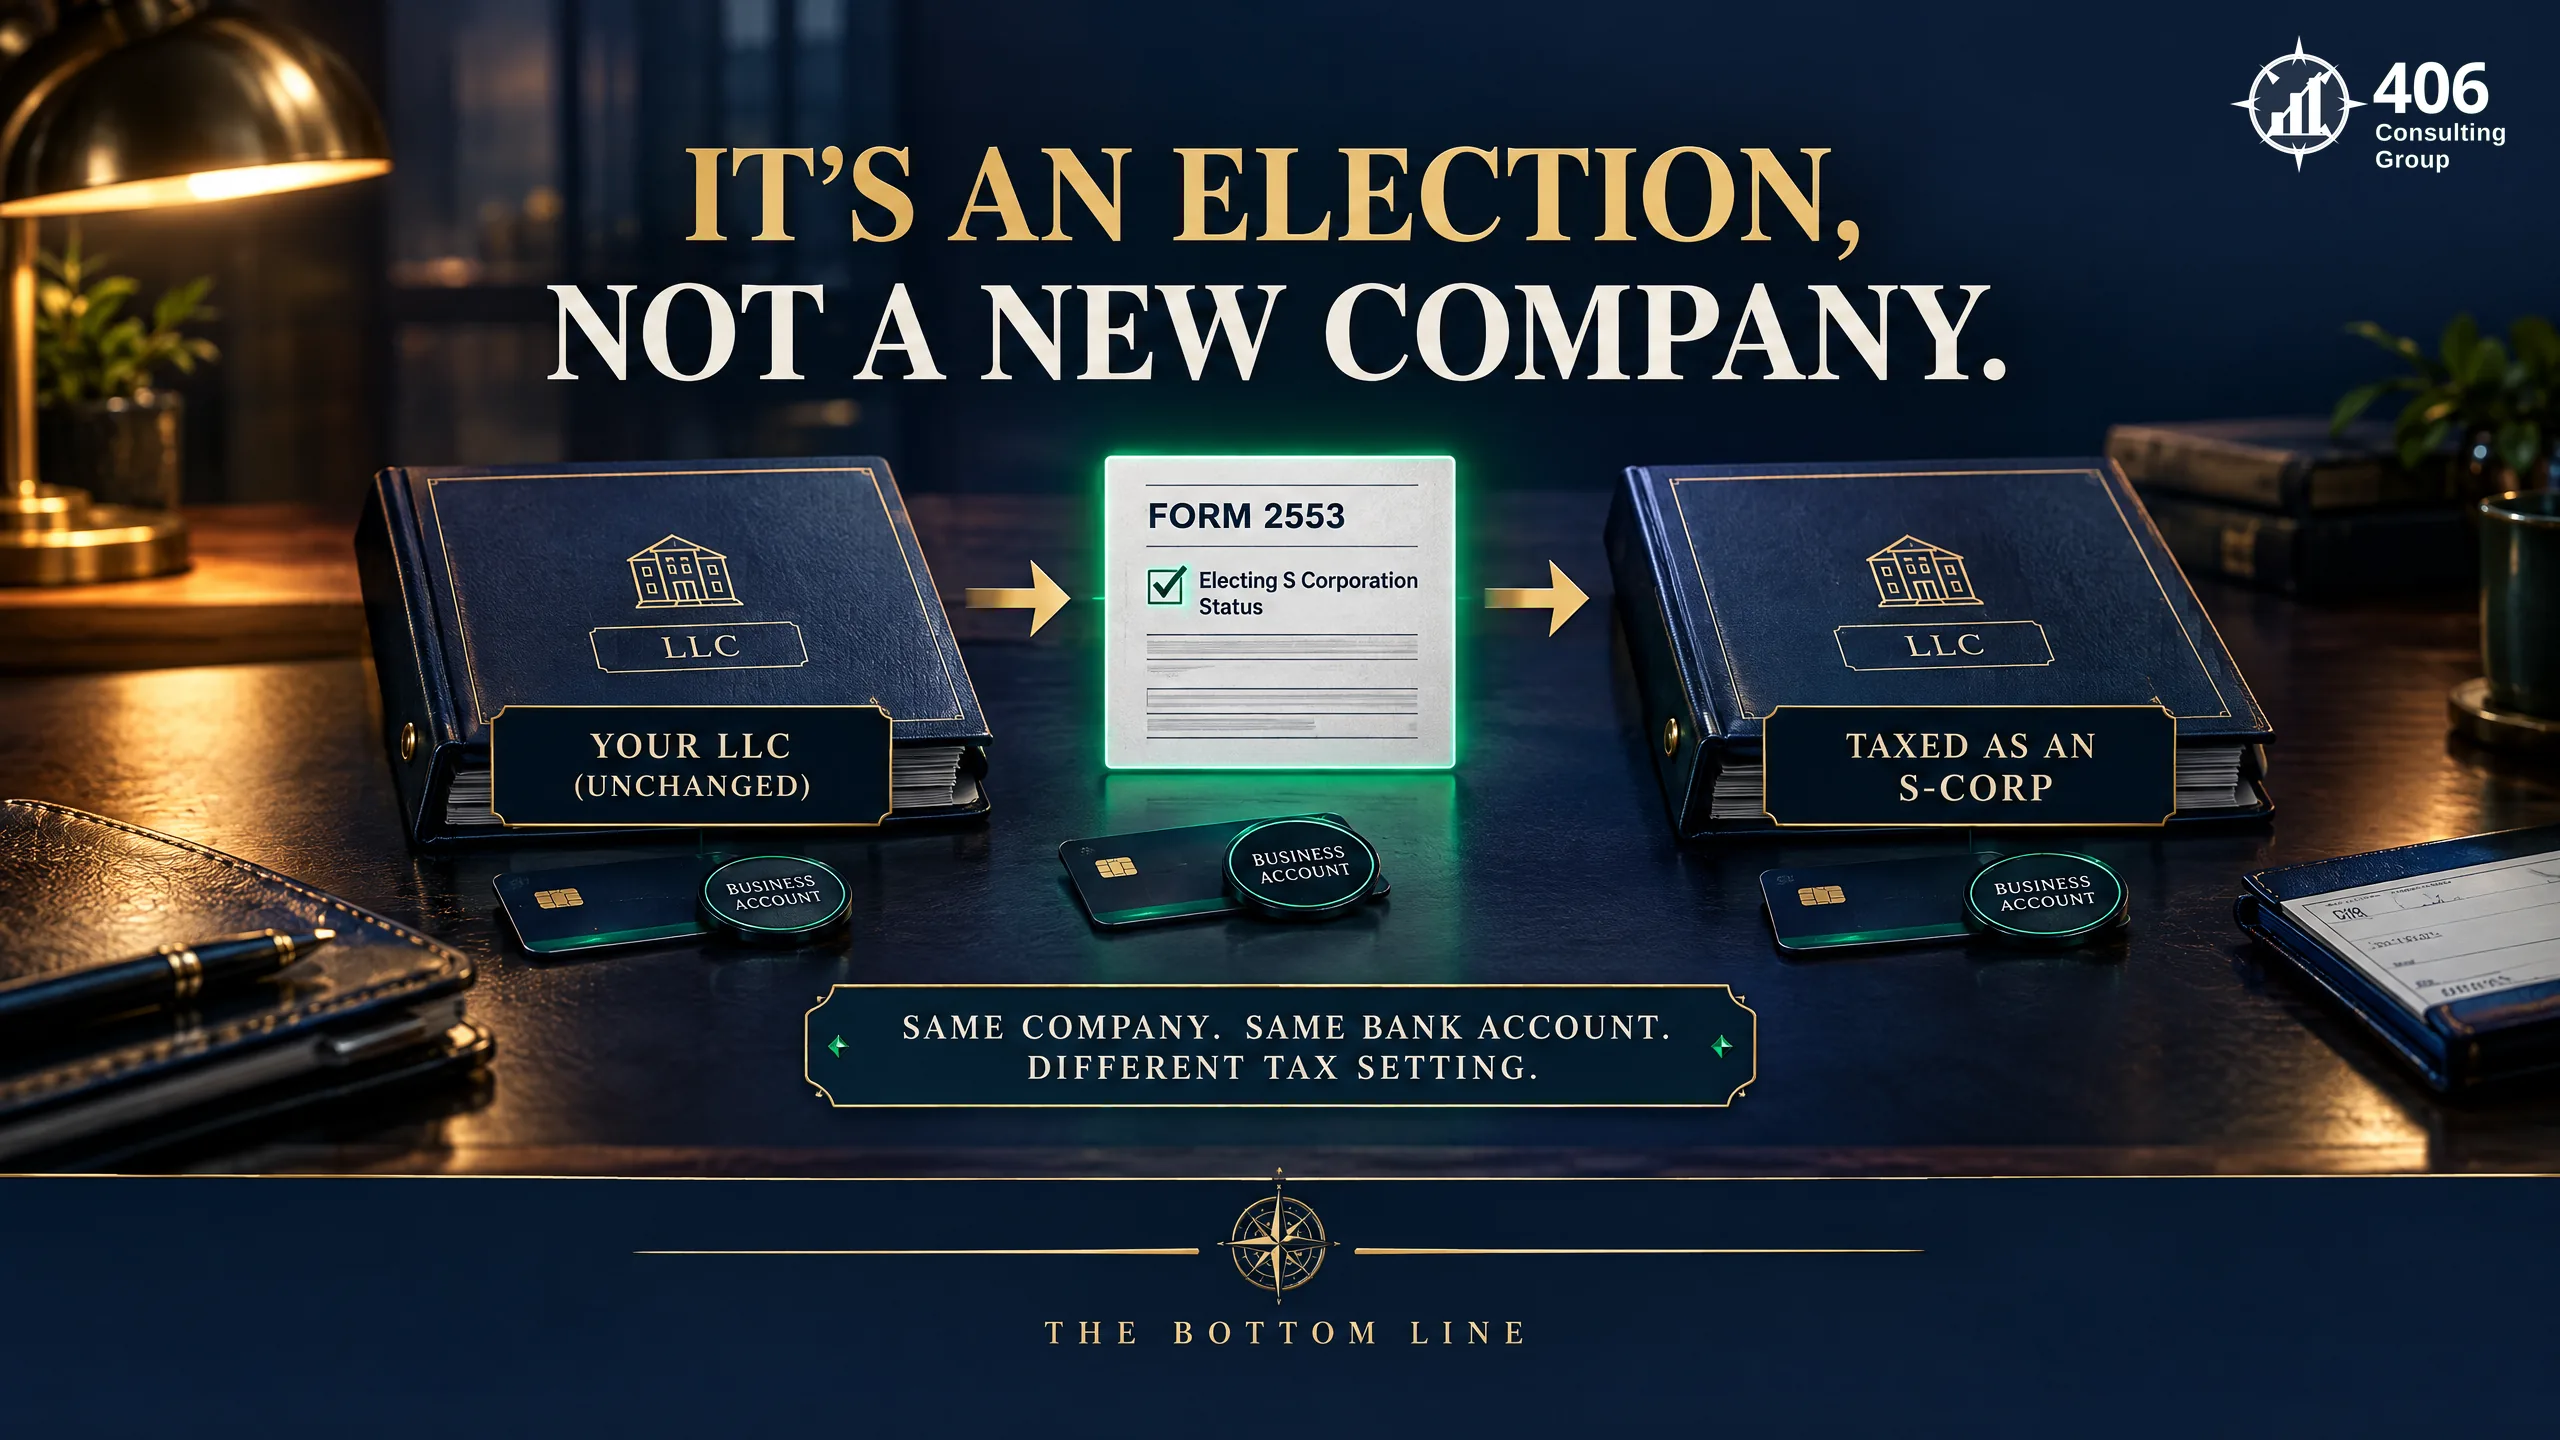
First, clear up the biggest confusion: an "S-corp" is not a type of company you go form. It's a tax election — a box you check with the IRS that changes how your existing business is taxed. Sam keeps his LLC exactly as it is; he just files one form asking the IRS to tax it as an S-corp. Nothing about the business, the bank account, or the contracts has to change on the outside. What changes is how the profit is taxed— and that's where the money is.
You don't "become an S-corp." You keep your LLC and elect to be taxed as one. It's a tax setting, not a new company.
To see why that setting matters, you have to understand the tax it's designed to dodge.
How the Savings Actually Work
As a default LLC, Sam pays self-employment (SE) tax — about 15.3% (Social Security + Medicare) — on essentially all of his profit, on top of regular income tax. On $150,000, that SE tax is roughly $21,000. Ouch. That's the tax the S-corp election goes after.
Here's the mechanism. As an S-corp, Sam splits his $150,000 into two buckets: a reasonable salary he pays himself through payroll, and the rest taken as distributions. The salary still gets hit with the 15.3% (that's payroll tax) — but the distributions don't pay SE or payroll tax at all. Say Sam pays himself a $70,000 salary and takes $80,000 as distributions:
Sam's $150,000 — default LLC vs. S-corp
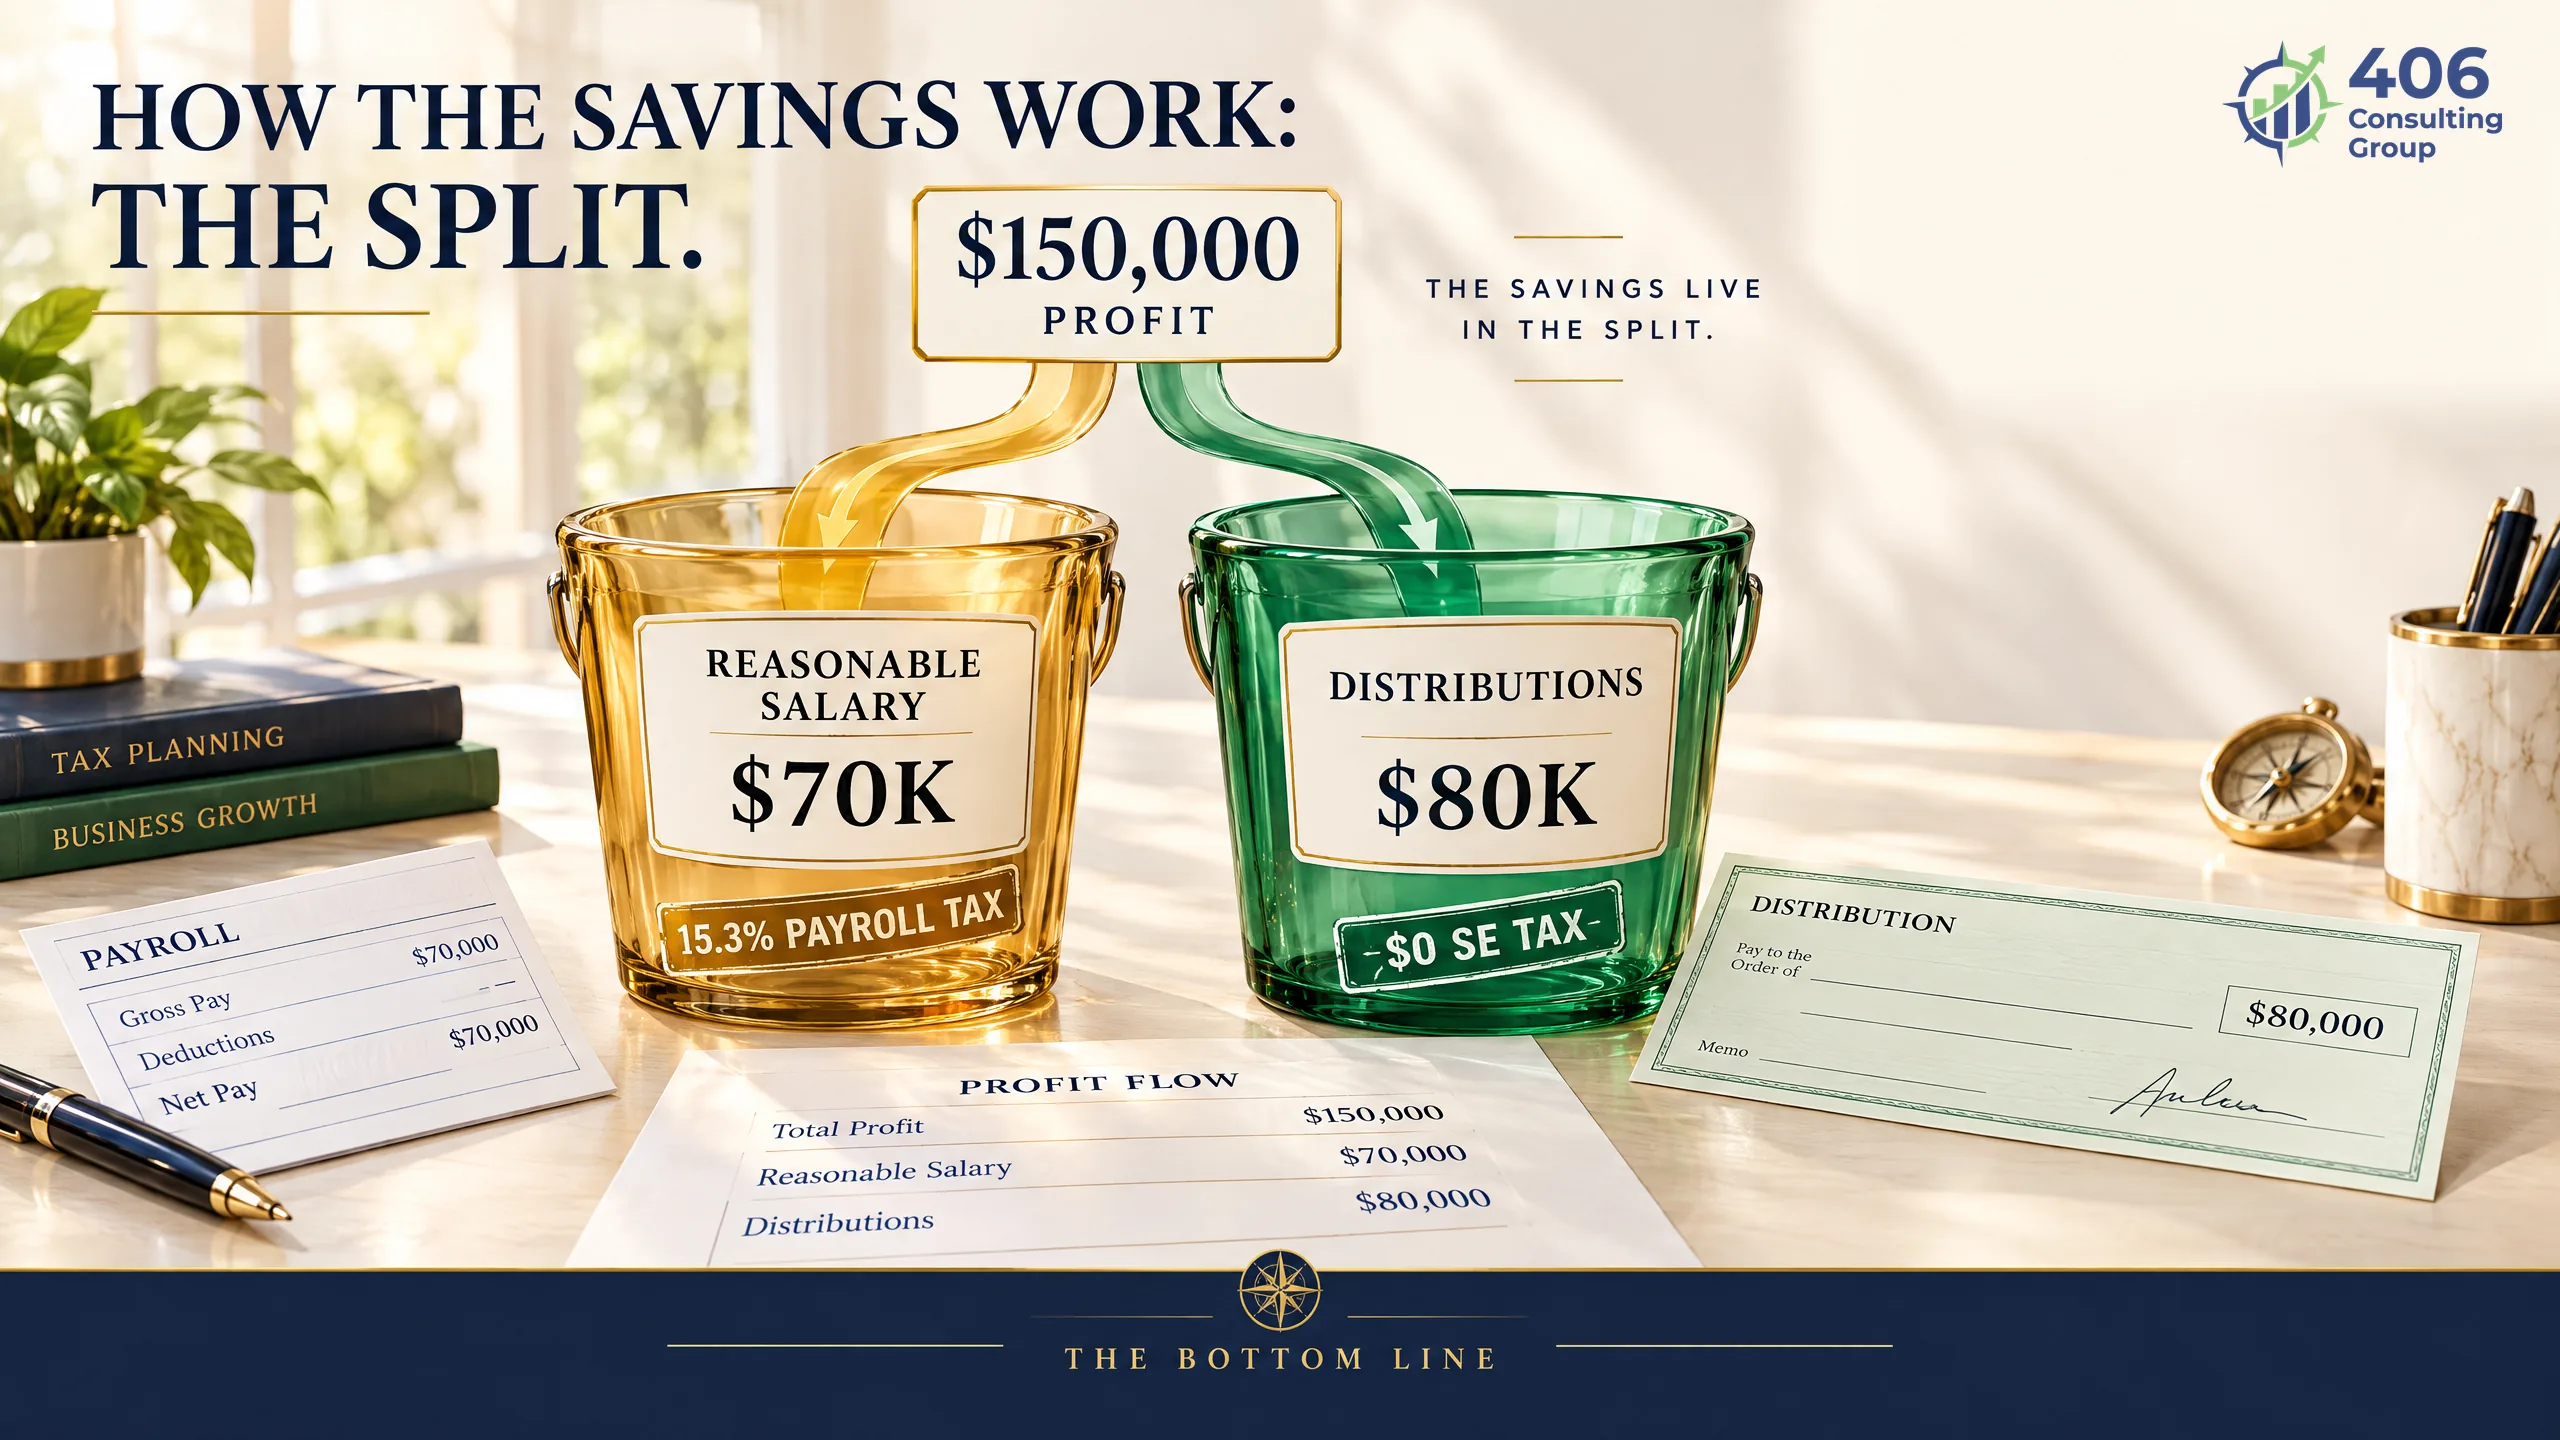
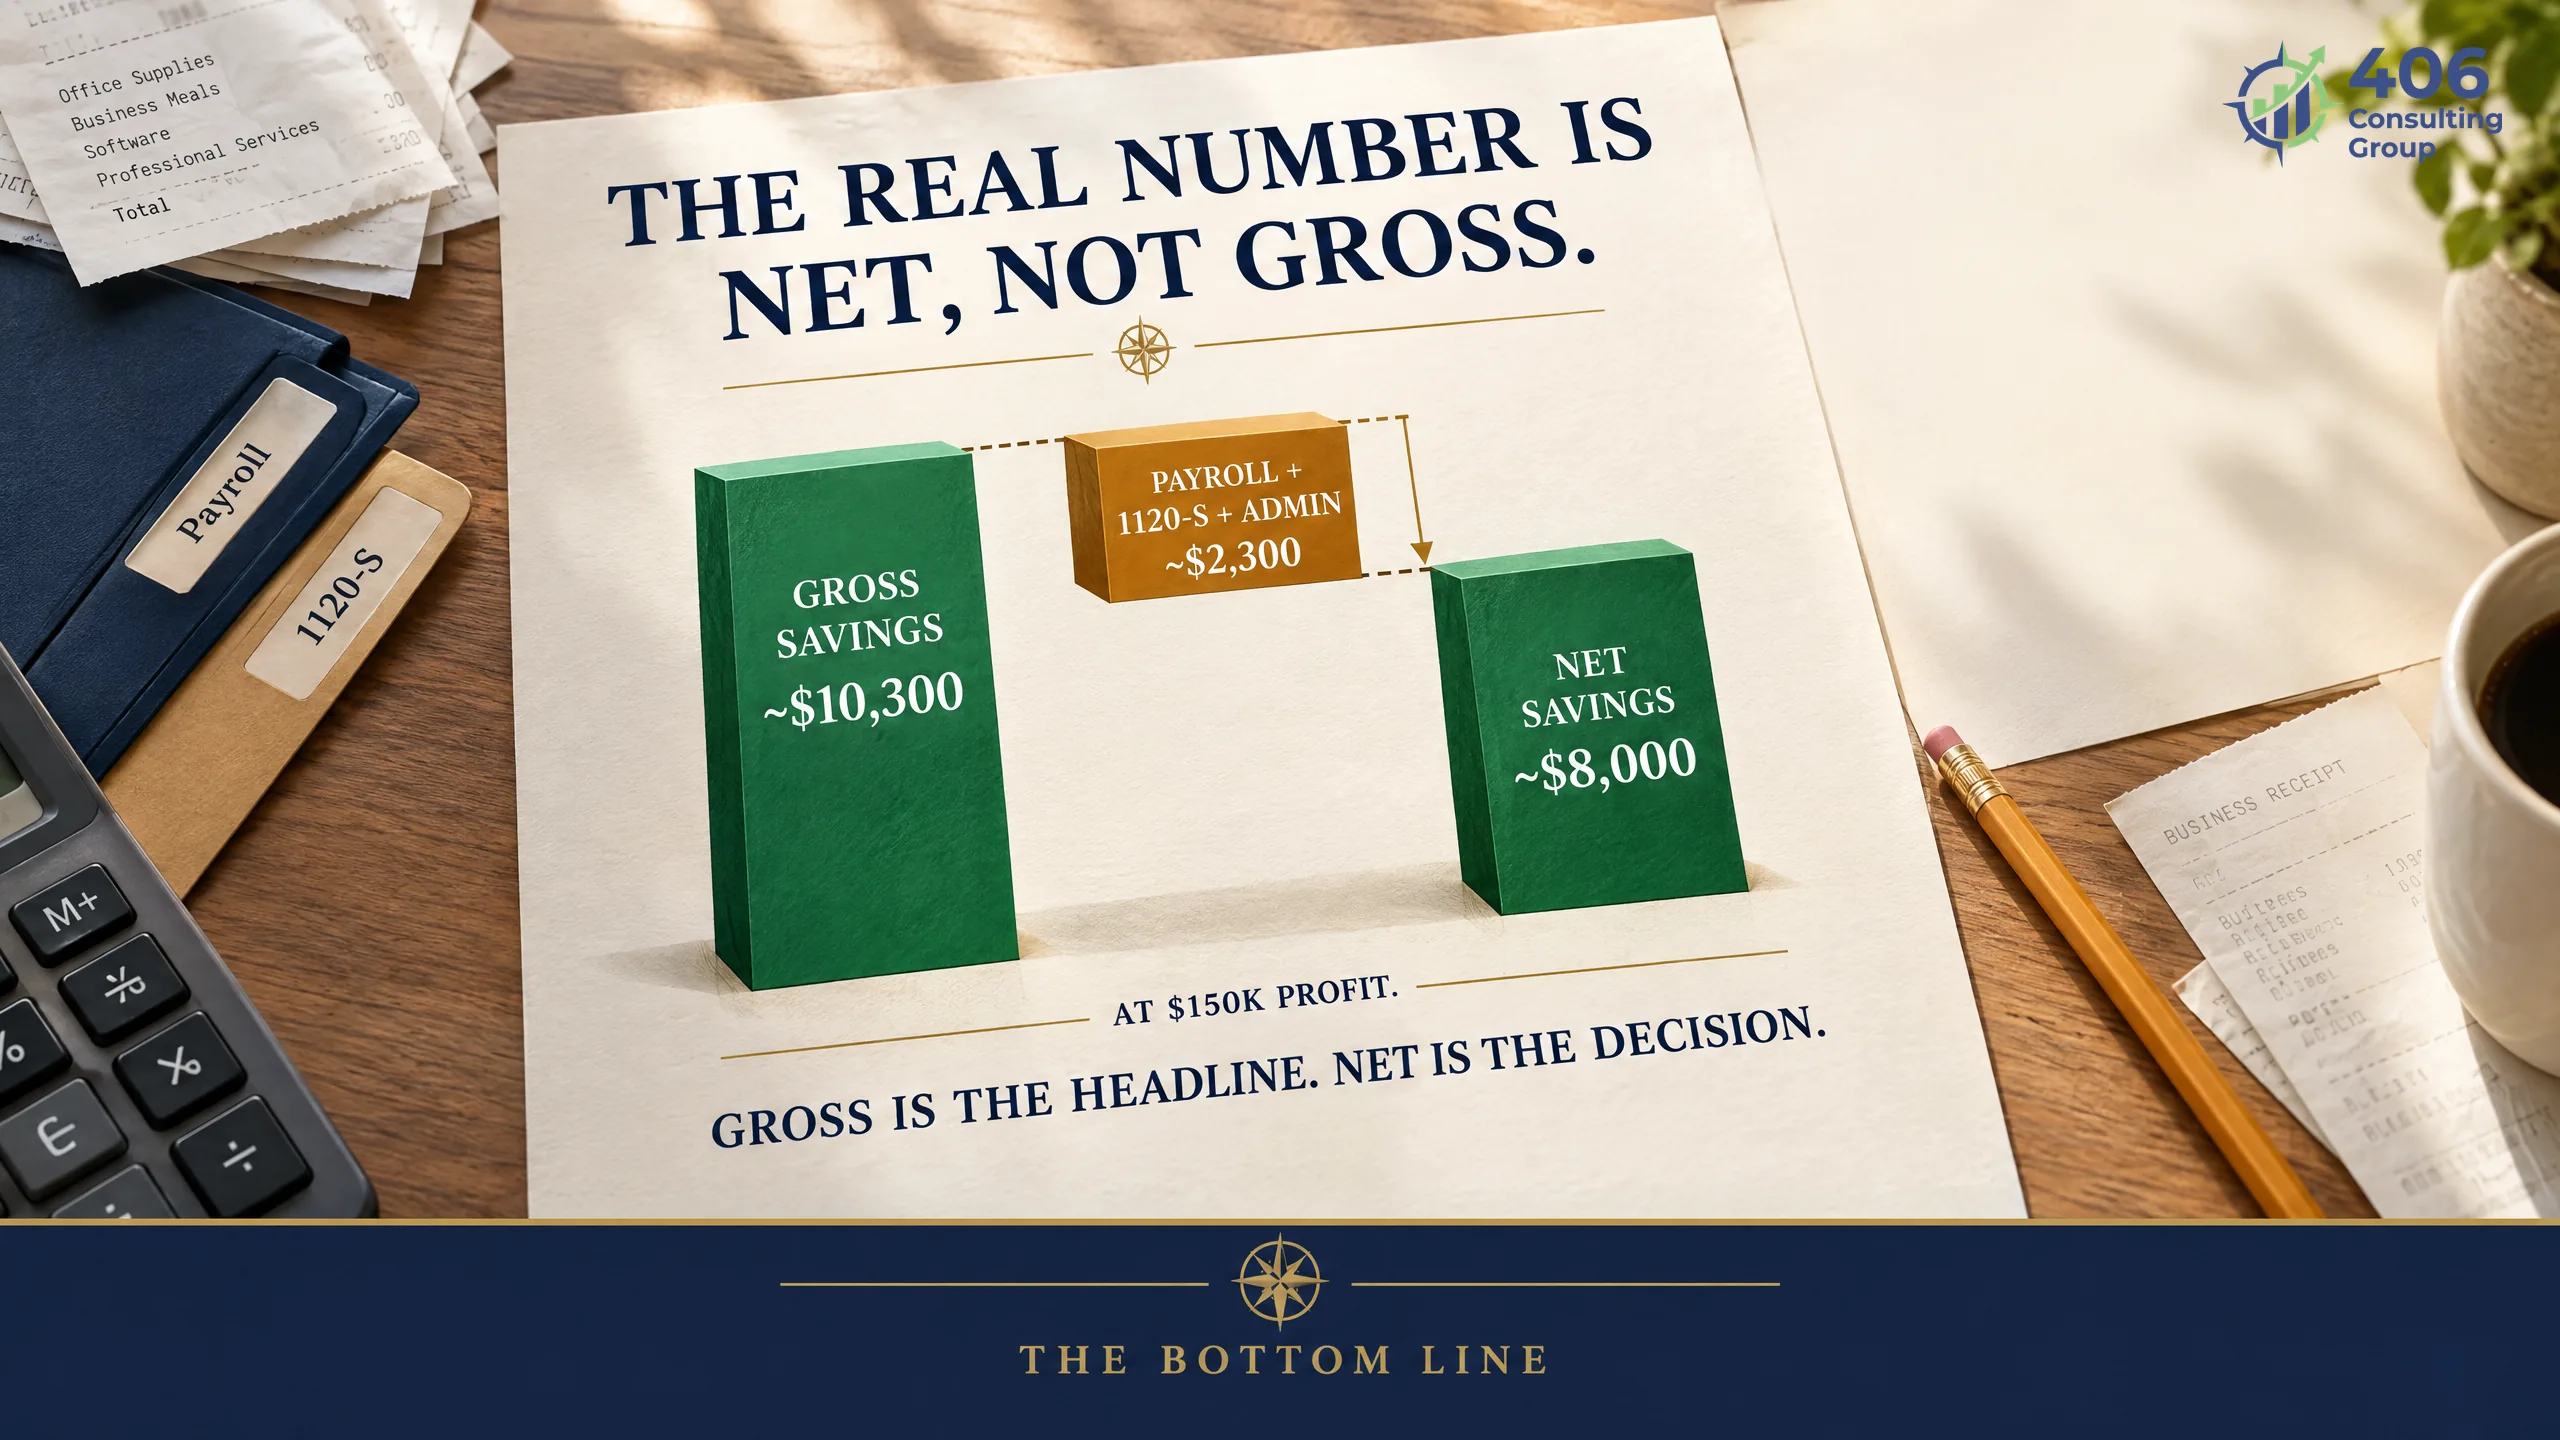
That $10,300 is the prize everyone's talking about — the SE tax that simply never gets charged on the distribution bucket. But notice what made it work: the split. Which raises the obvious question — does this work at any profit level?
The Breakeven: When It's Worth It
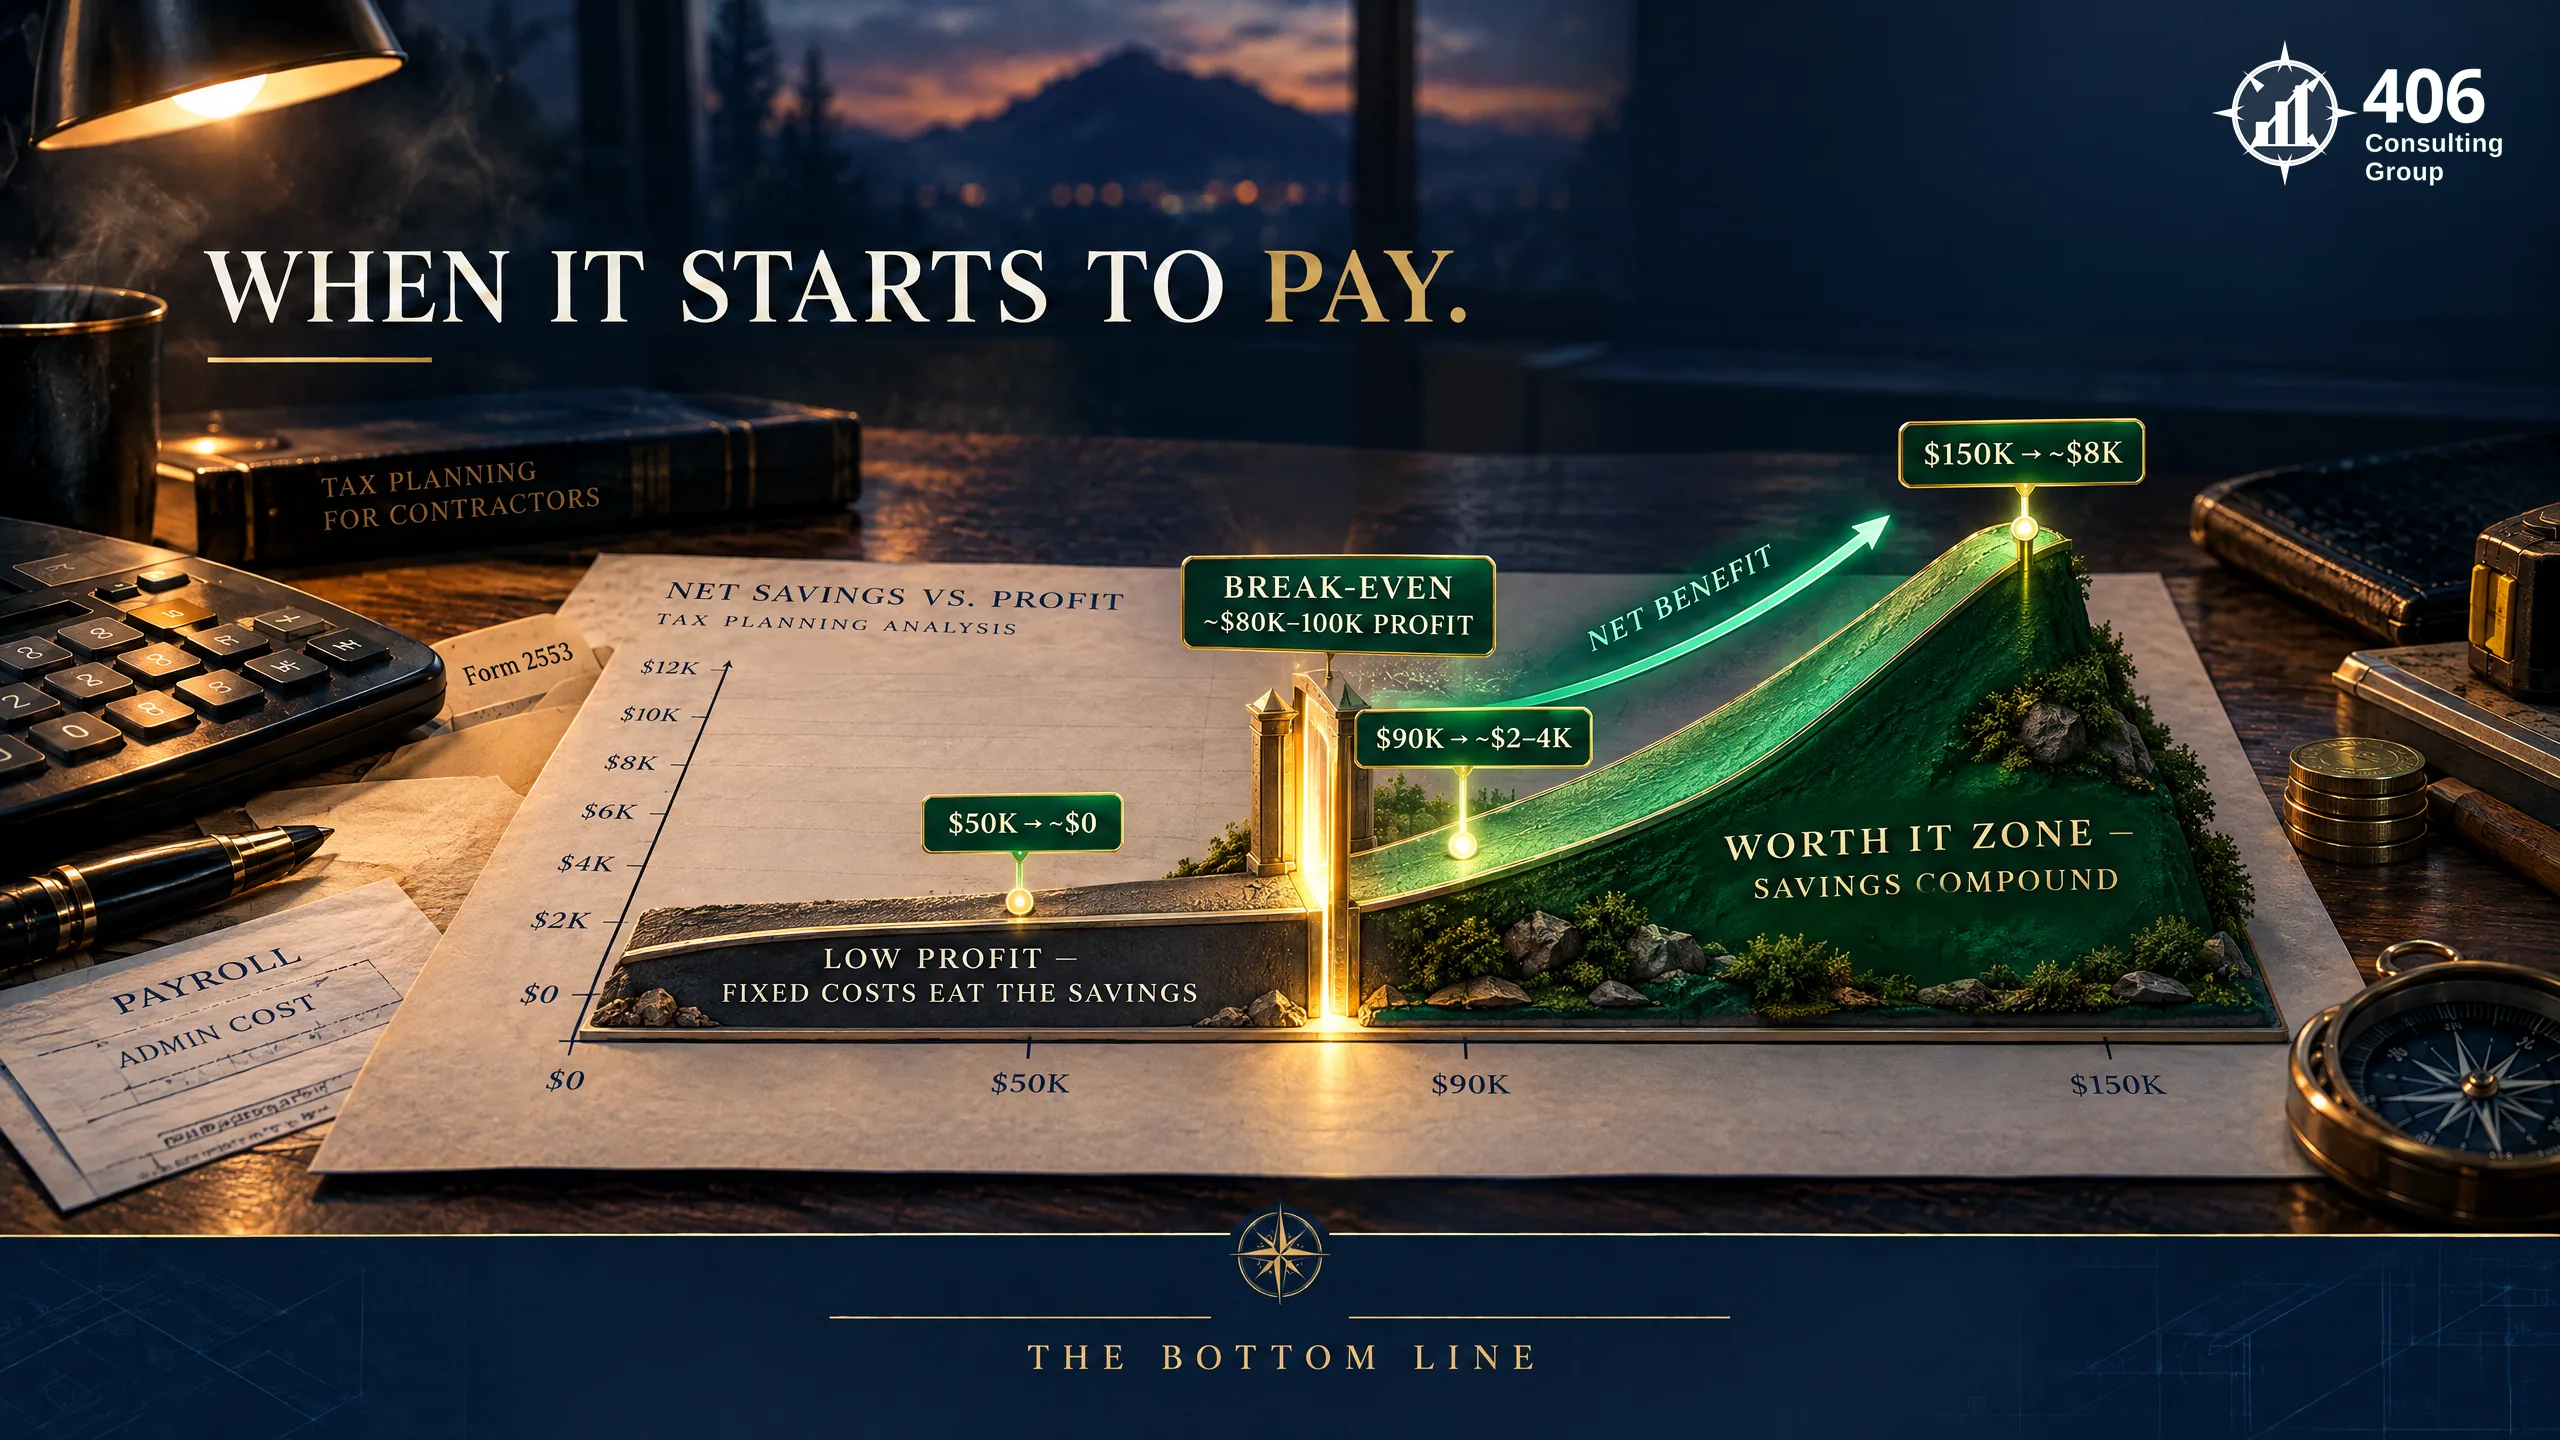
No. The savings come entirely from the distribution bucket — the profit aboveyour reasonable salary. If your salary has to eat most of your profit, there's little left to shield, and the S-corp's extra costs eat the rest. That's why there's a rough floor. Here's how it plays out at three profit levels (using a sensible salary at each):
$50K profit
~$0
costs likely eat the savings — not worth it yet
$90K profit
~$2–4K
the low end where it starts to pay
$150K profit
~$8K
clearly worth it (net of costs)
The rule of thumb: the election usually starts making sense once profit consistently clears roughly $80,000–$100,000, and the case gets stronger from there. One nuance at the top end: Social Security tax only applies up to an annual wage-base limit, so once your salary approaches that ceiling the savings on additional distributions shrink to just the Medicare portion — still real, but smaller than the headline 15.3%. Your exact number depends on your profit and your salary, which is what the calculator is for.
Everything above hinges on one word we've used a lot: reasonable. That's where owners get themselves in trouble.
The Catch: "Reasonable Salary"
You might be thinking: if distributions escape the tax, why not pay myself a $10,000 salary and take $140,000 as distributions? Because the IRS thought of that. The law requires an S-corp owner who works in the business to take a reasonable salary — reasonable pay for the work you actually do — beforetaking distributions. Lowball it and you're waving a red flag: unreasonably low owner salaries are a known audit trigger, and if the IRS reclassifies your distributions as wages, you owe the back payroll tax plus penalties and interest. The savings you reached for become a bill.
The whole strategy lives or dies on the salary number. Too high and you overpay tax; too low and you invite an audit. "Reasonable" is the entire game.
What's reasonable? Roughly, what you'd have to pay someone else to do your job — based on your duties, hours, experience, and local wage data for your role. It's a defensible estimate, not a guess. Our S-Corp reasonable-salary calculator builds one from real wage data, and we go deeper in our entity guides.
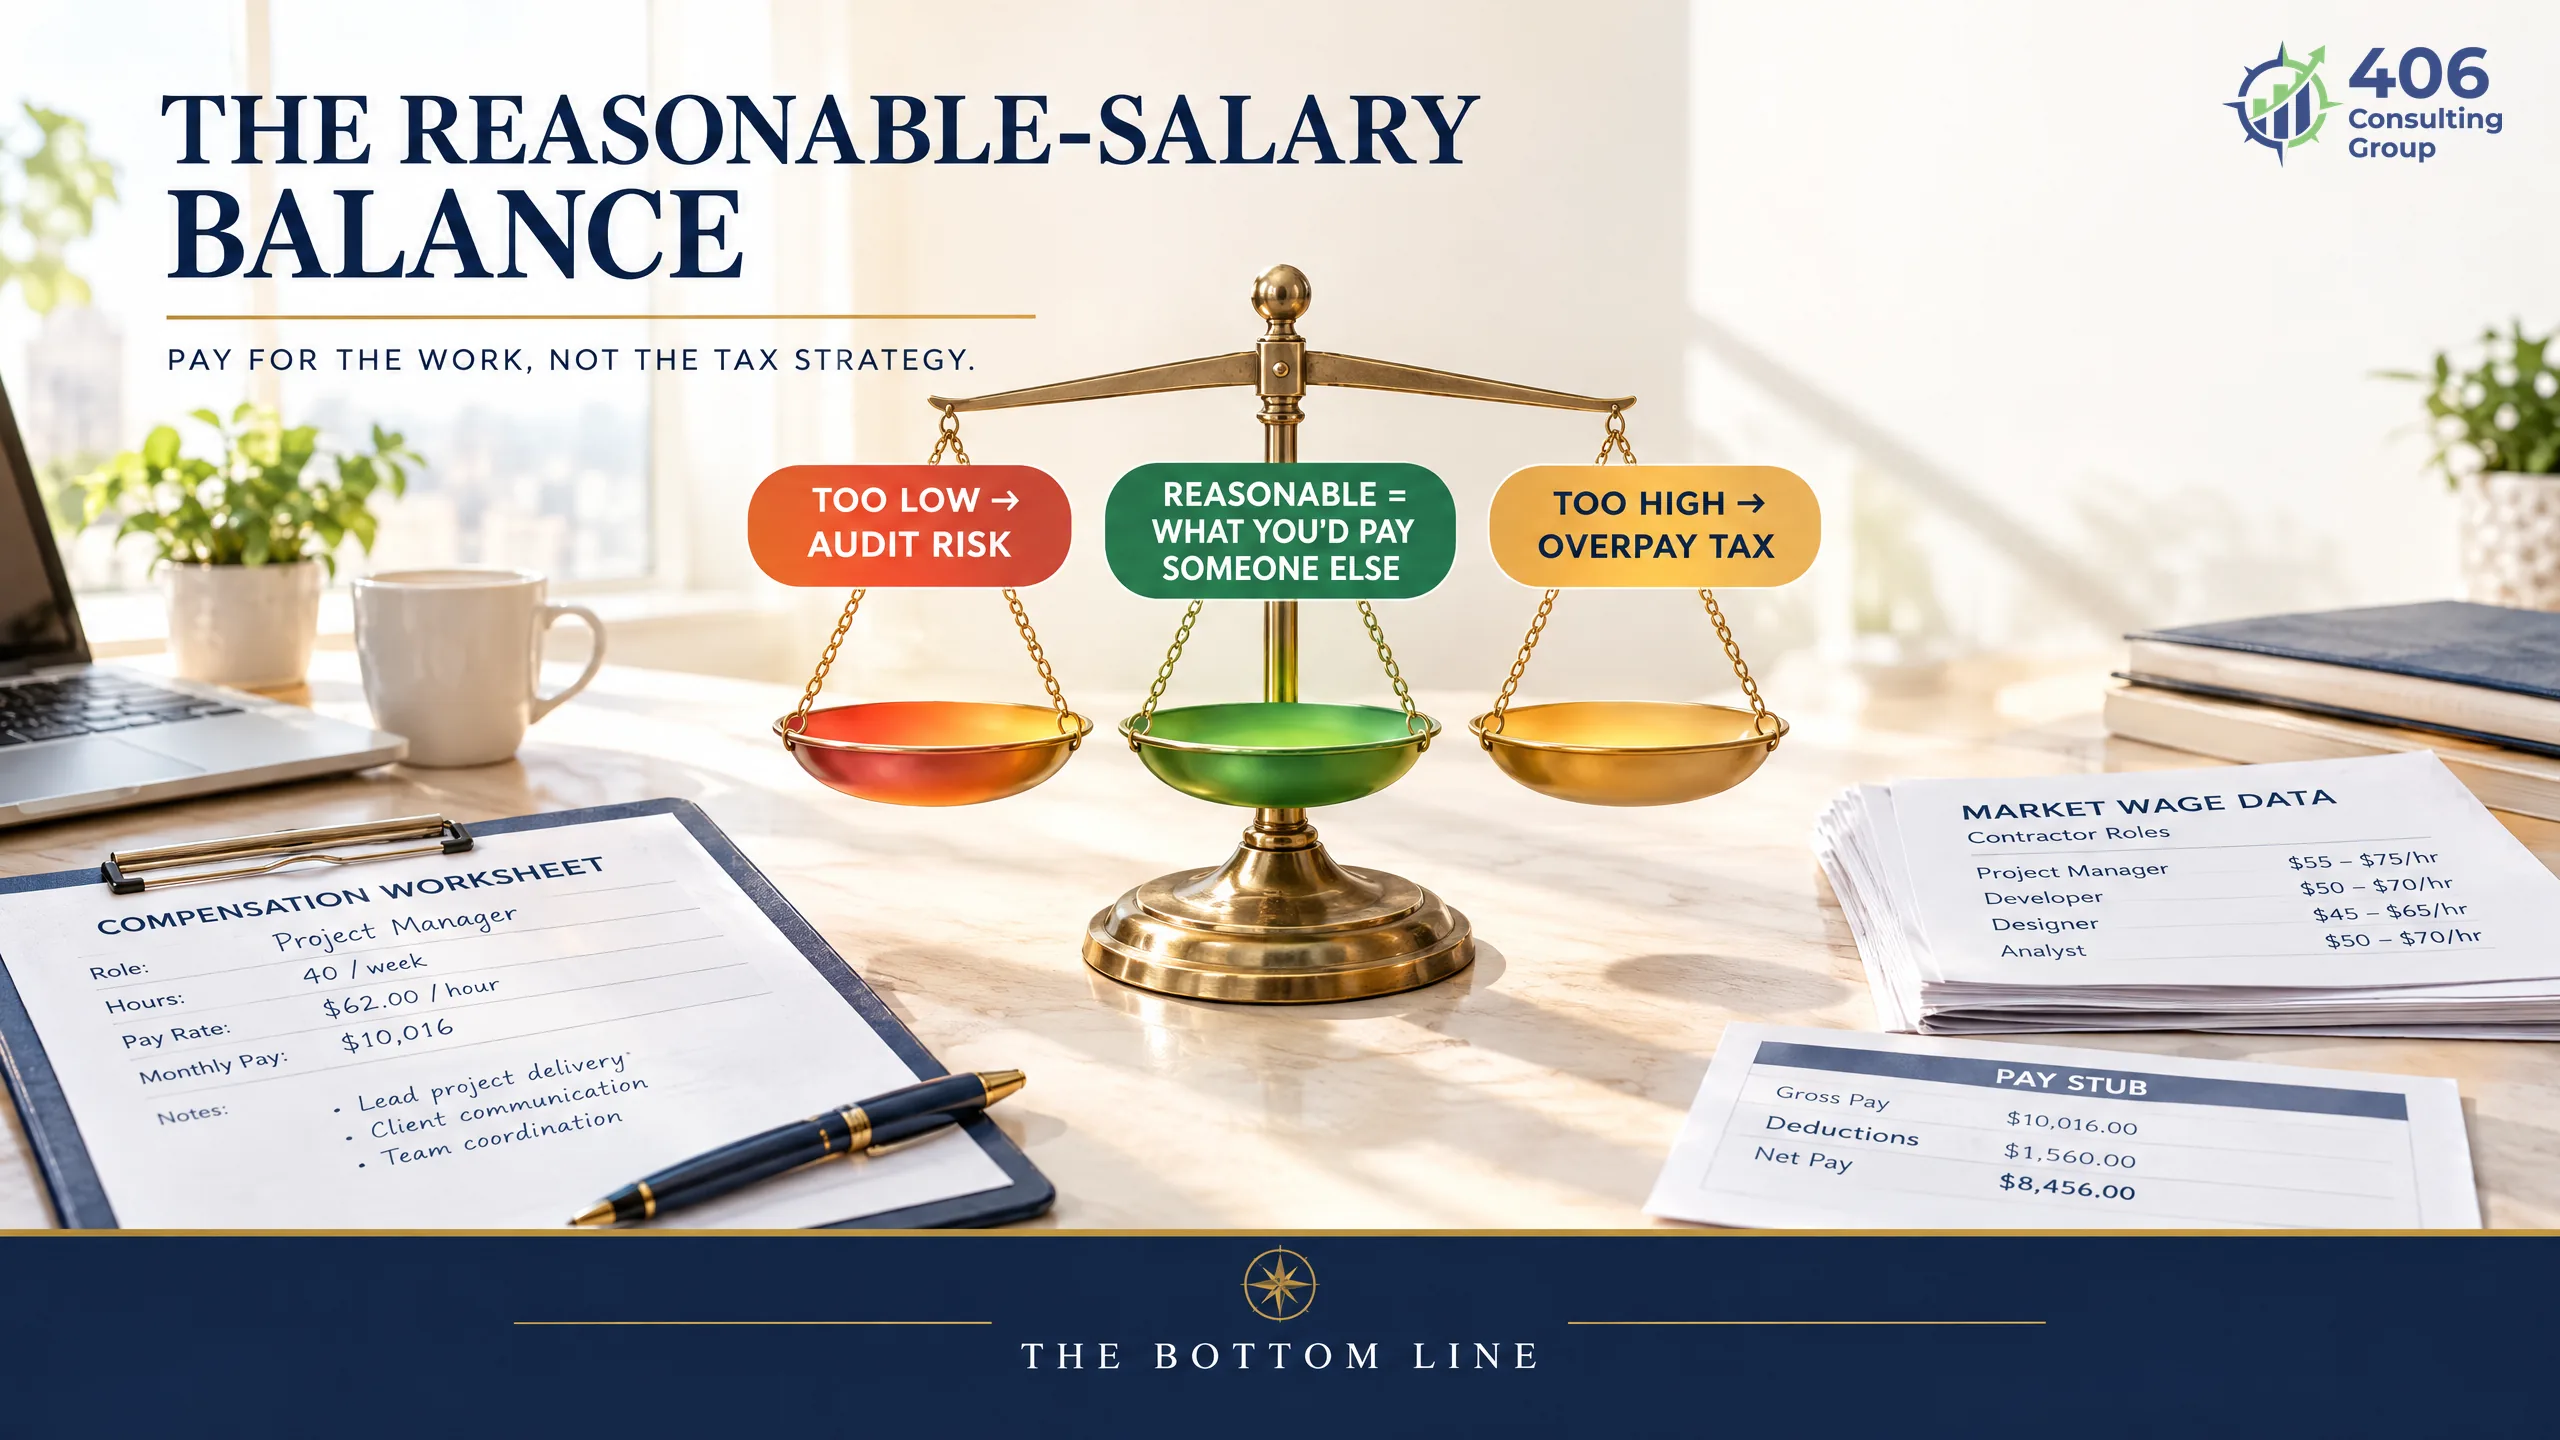
Get the salary right and the savings are real — but "savings" isn't the whole picture until you subtract what the election costs to run.
The State Wrinkles
The federal savings are the main event, but states treat S-corps differently, and it matters. Some charge the S-corp its own tax — California, for example, levies a 1.5% tax on S-corp income (with an $800 minimum); others impose franchise or entity-level taxes that a plain LLC might avoid (North Carolina's franchise tax, Georgia's Net Worth Tax, Illinois's replacement tax). On the other side, electing S-corp is often what lets you use your state's PTE electionto work around the federal SALT cap — a separate, sometimes larger, saving. The point isn't to memorize all of it; it's that the right answer is state-specific, so the general rule of thumb needs a local check.
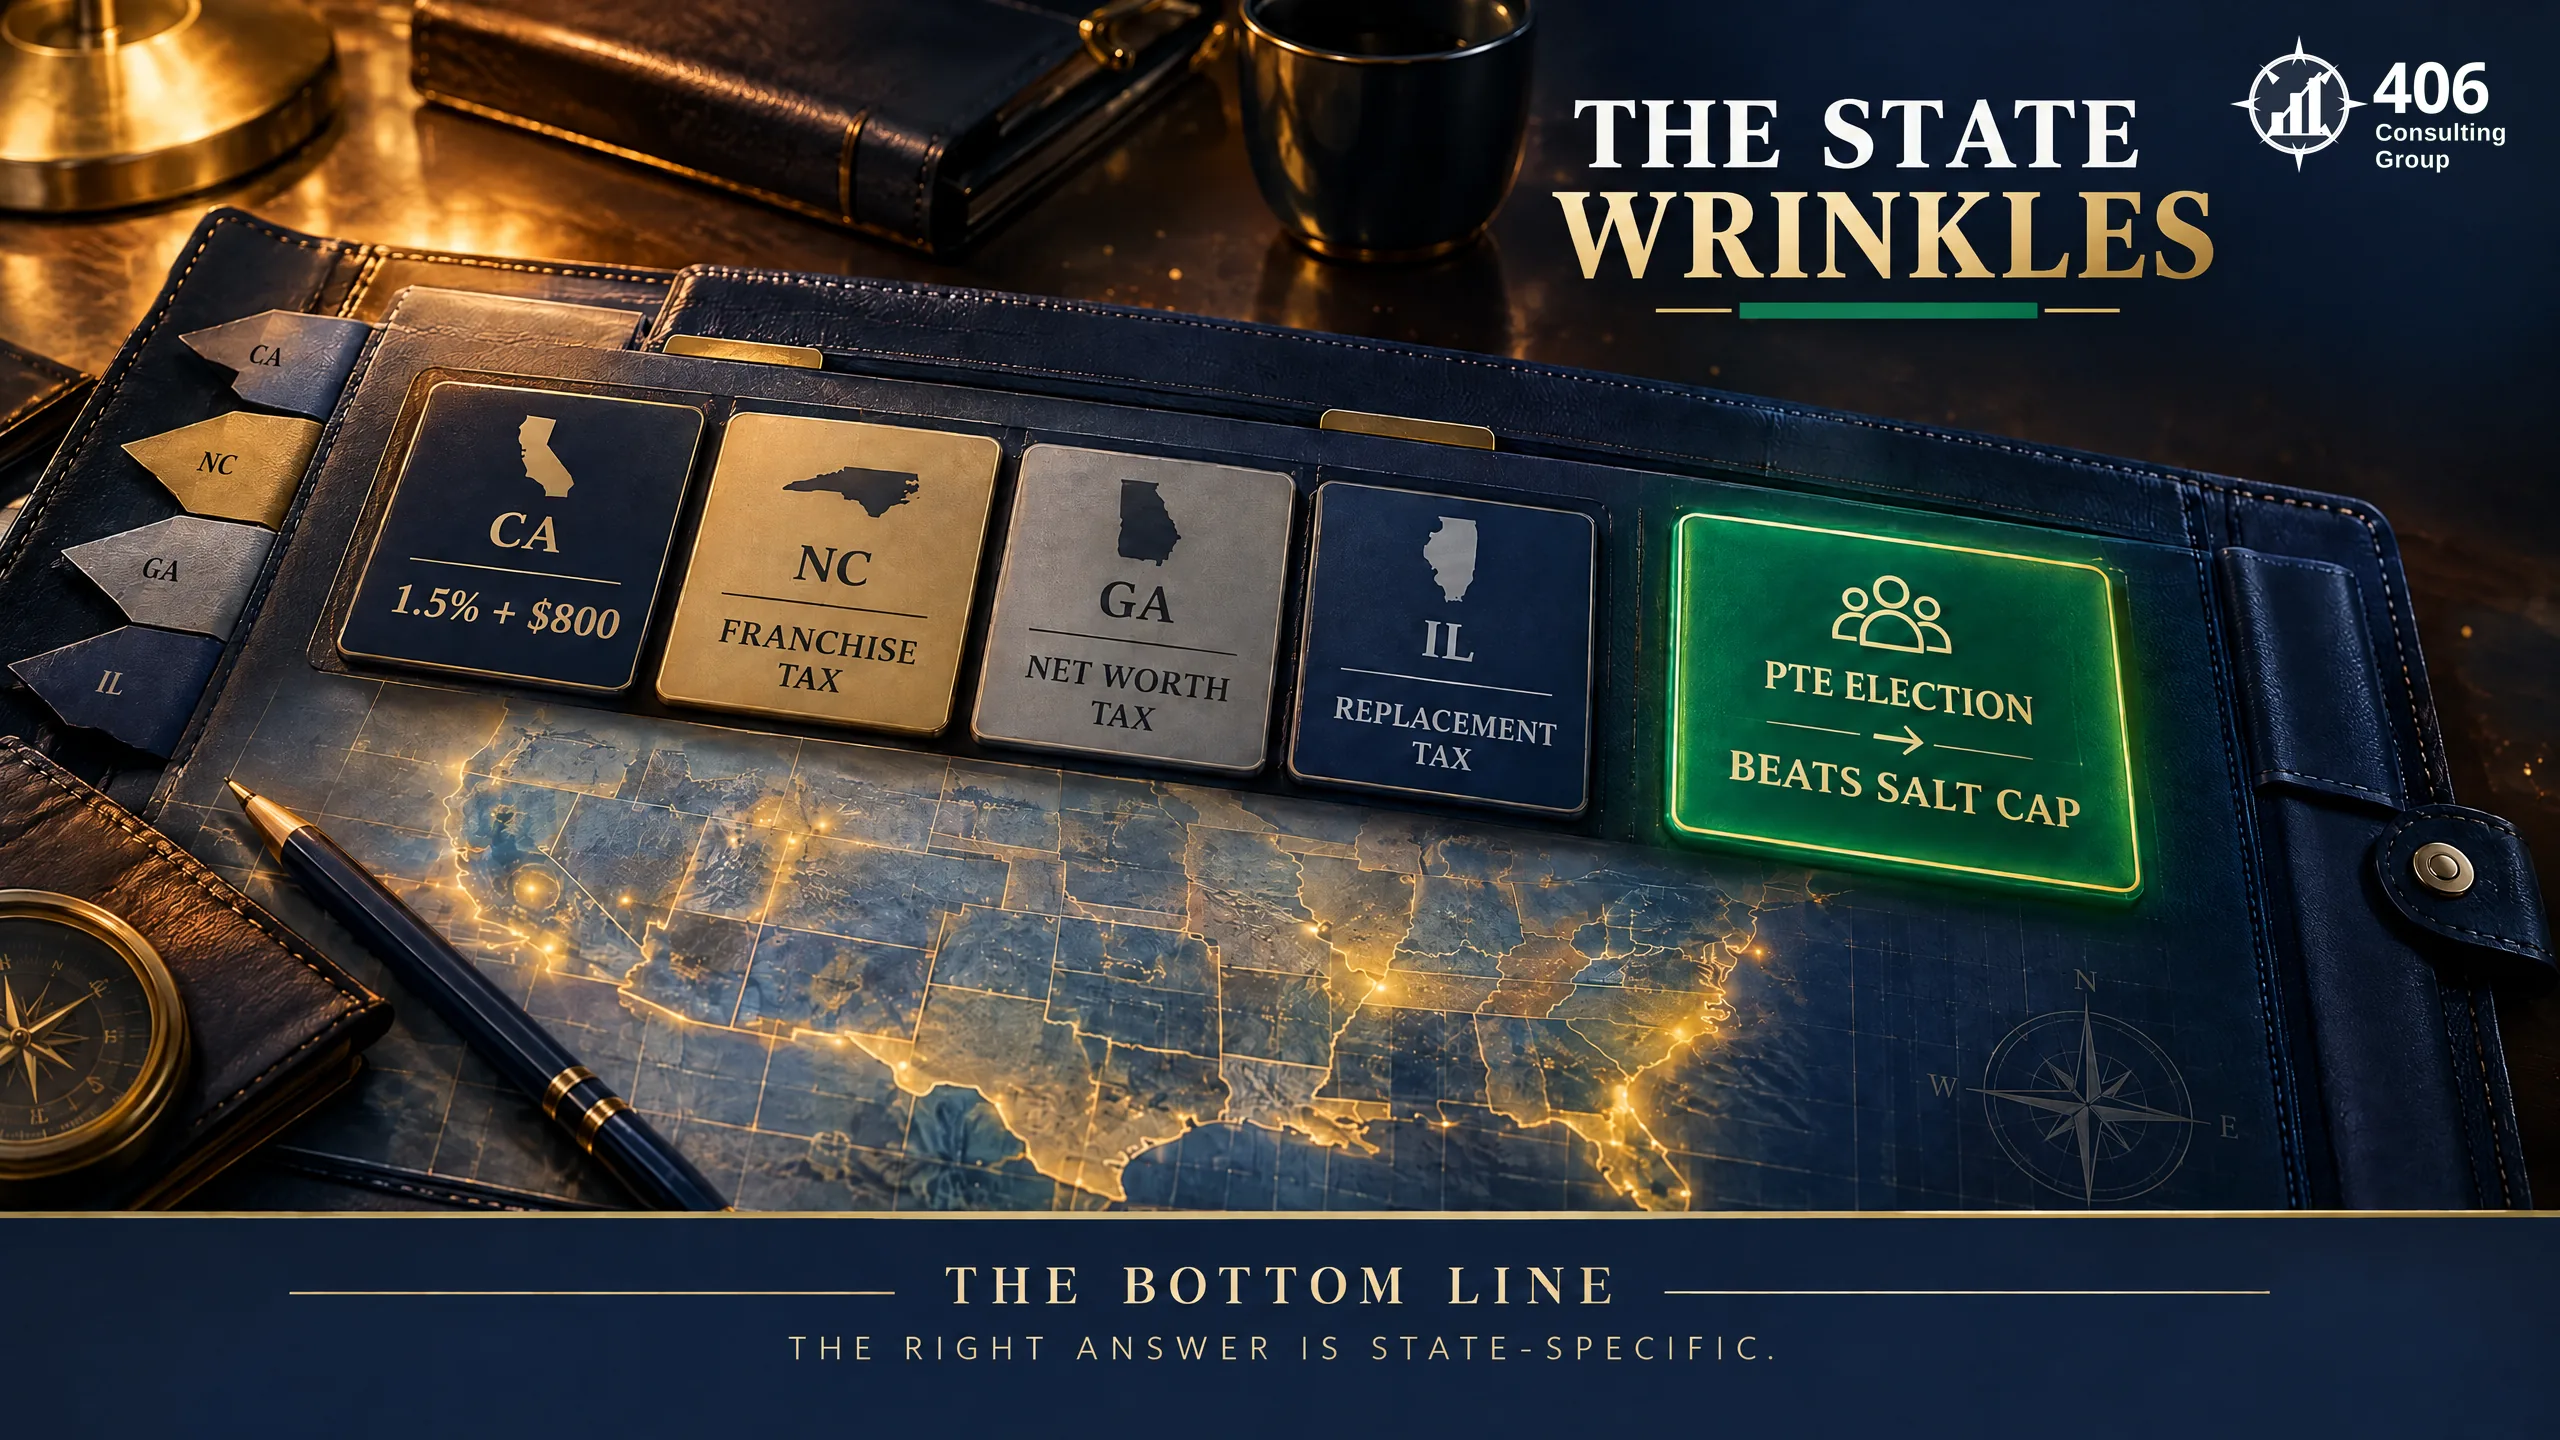
Our city tax guides — like Atlanta and Charlotte— work these state pieces in detail. Put it all together and sometimes the answer is simply: not yet, or not you.
When NOT to Elect
A good advisor tells you when the answer is no. Skip the election — at least for now — if:
Your profit is still low
Under roughly $80K, the payroll and return costs usually swallow the savings. Wait until you've grown into it.
You reinvest everything
If you plow all the profit back in and take little out, there are few distributions to shield — so little to save.
You plan to raise venture capital
Investors typically want a C-corp (often Delaware). An S-corp's ownership limits get in the way of a raise.
You don't qualify
S-corps cap out at 100 shareholders, allow only certain U.S. owners, and permit one class of stock. Some businesses simply can't elect.
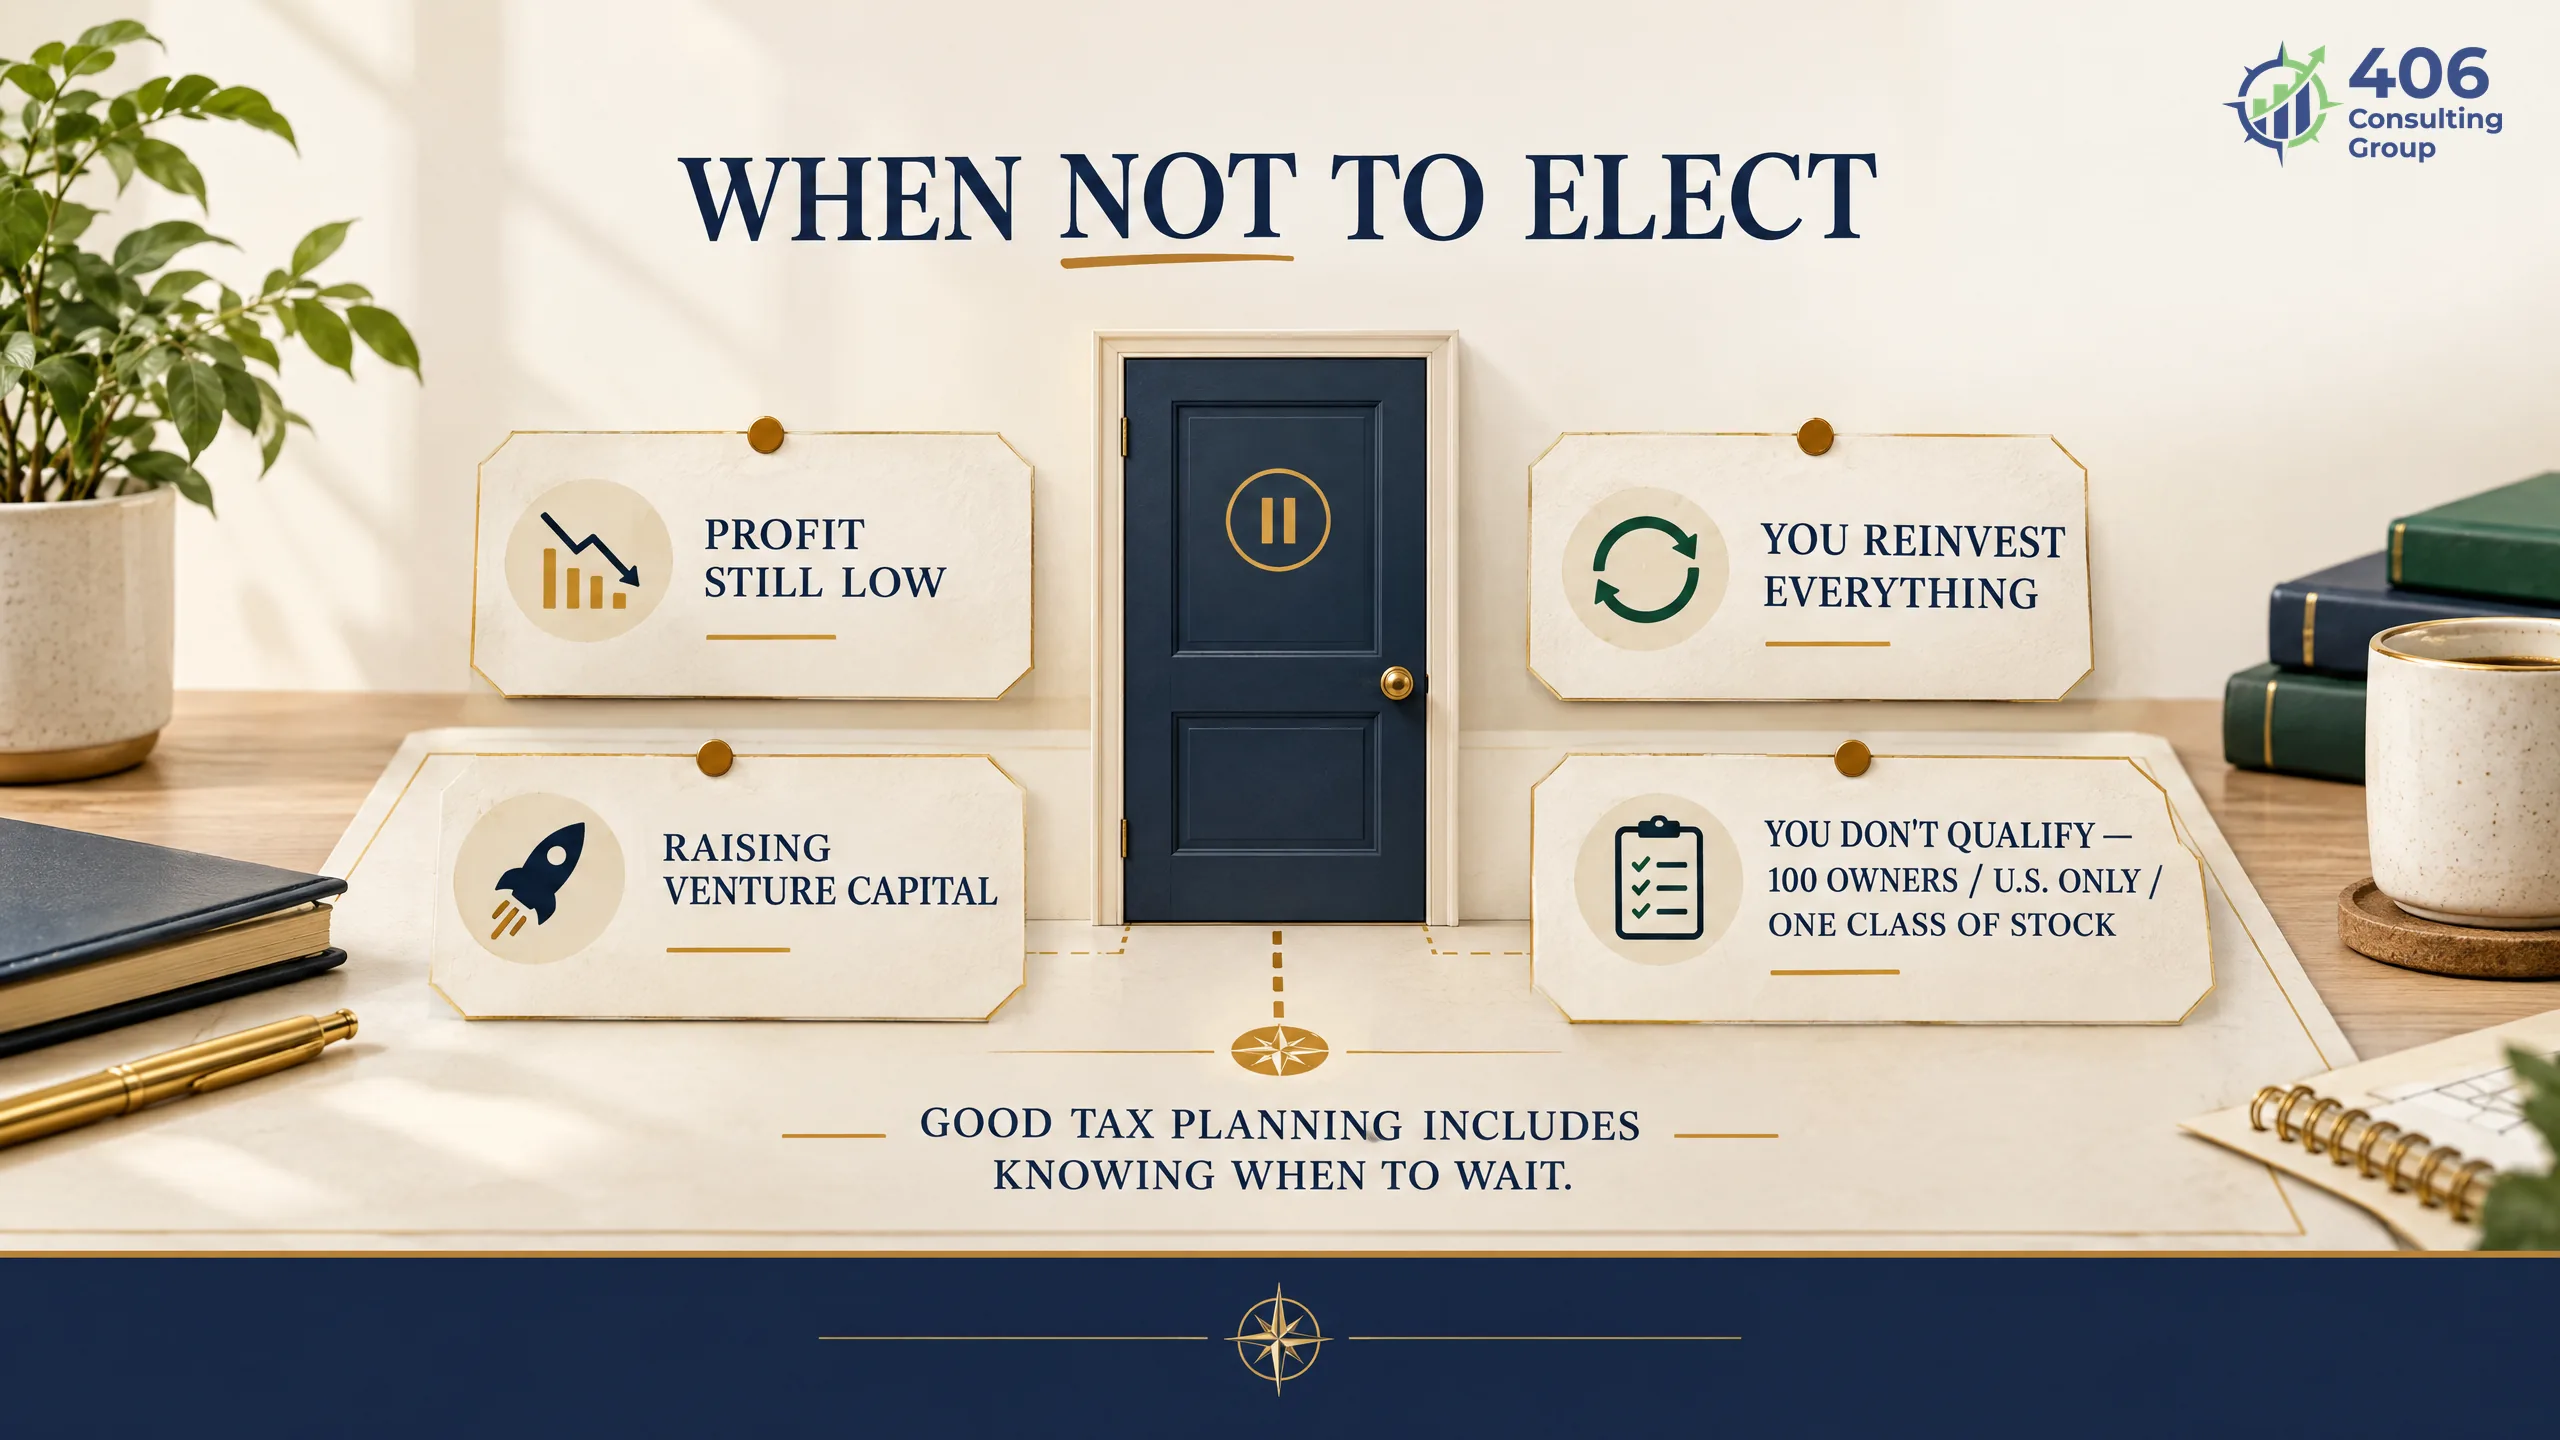
If none of those apply and your profit clears the bar, the election is usually a straightforward win. So how do you actually pull the trigger?
How to Actually Do It
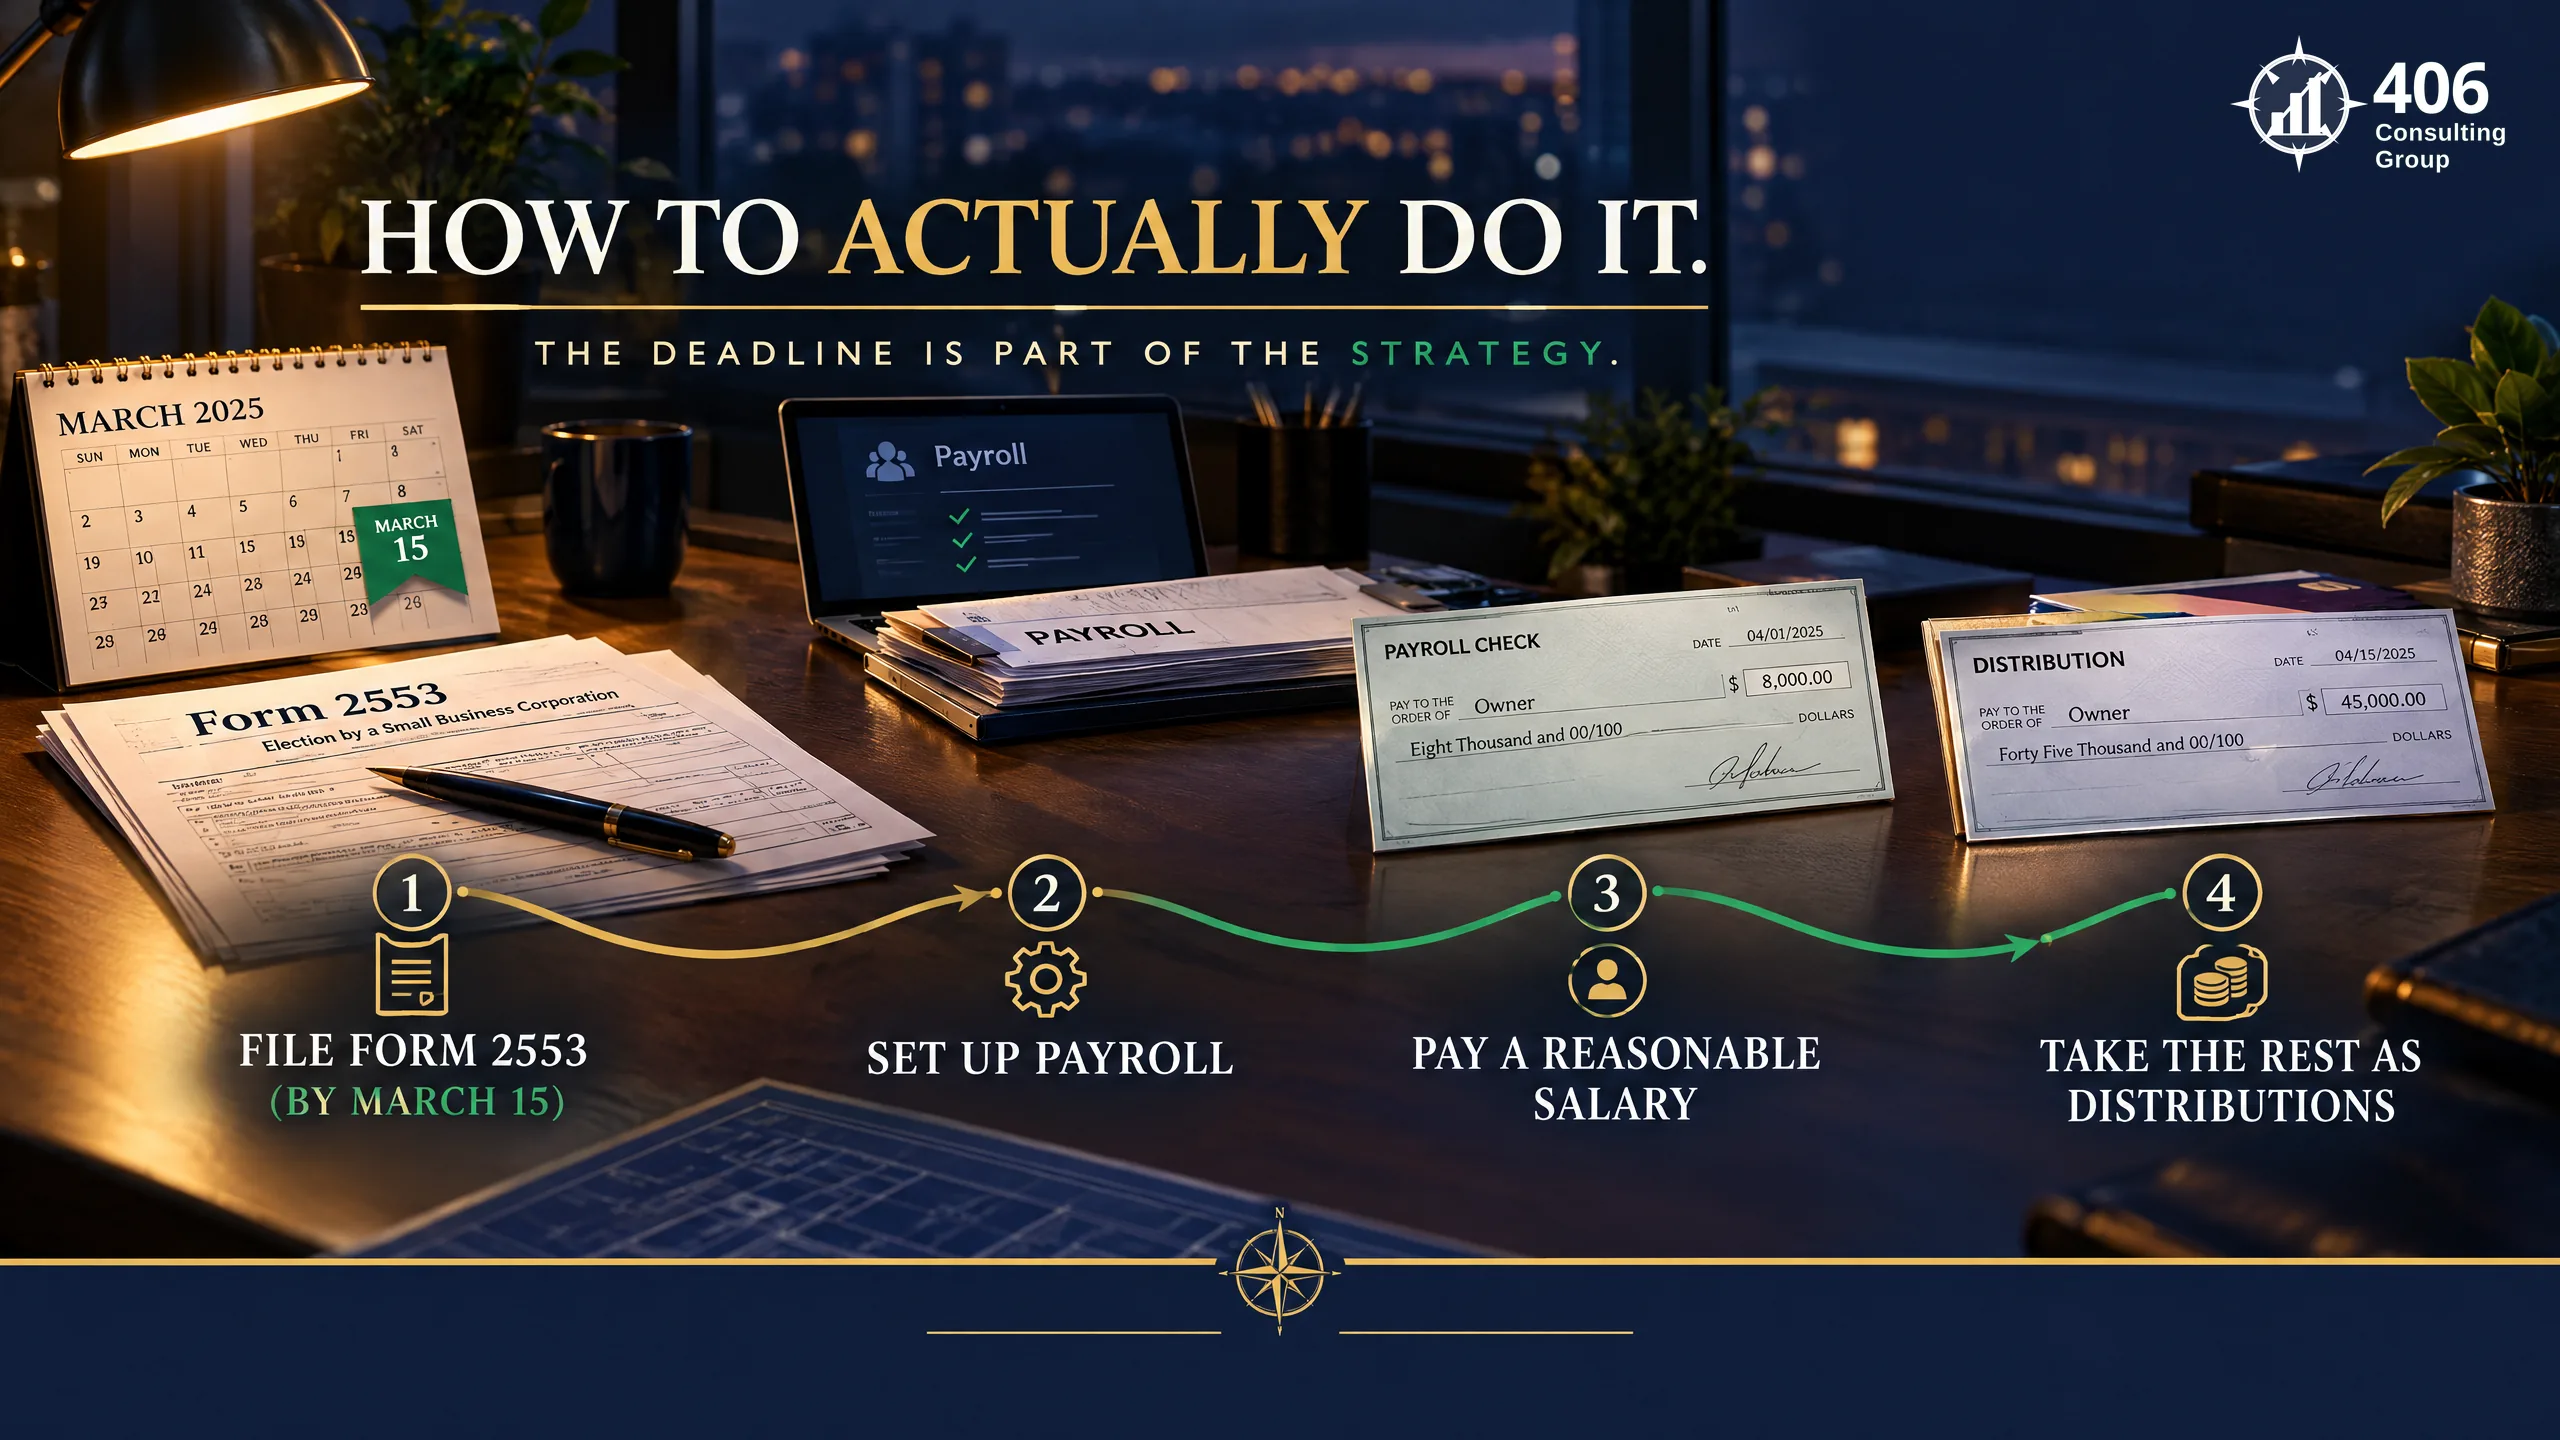
Mechanically, it's one form and a deadline. You file IRS Form 2553 to make the election, and timing is strict: to have it apply for the current tax year, you generally must file within about two months and fifteen days of the start of that year — March 15 for a calendar-year business. Miss it and there's often late-election reliefavailable if you qualify, but that's a "don't rely on it" backstop, not a plan. Once elected, you set up payroll, pay yourself the reasonable salary, and take the rest as distributions — and you keep the books clean enough to prove it.
The deadline mechanics get their own deep dive in The S-Corp Election Deadline. But before any of that — run your numbers.
Run Your Own Numbers
Sam's $150,000 and $8,000 of savings are his numbers. Yours depend on your profit, a defensible salary for your role, and your state. Don't guess and don't take the barbecue advice — get the actual figure, then decide.
See what the election would save you.
Use the free S-Corp calculator to build an IRS-defensible reasonable salary from real wage data and see your savings — then, if it makes sense, we'll handle the election and the payroll that has to come with it, done right.
The election is a great tool used at the right time, on the right numbers, with the salary done right. Get those three things lined up and it's one of the cleanest tax wins a profitable owner ever gets.
FAQ: The S-Corp Election
At what income is an S-corp worth it?
As a rule of thumb, the S-corp election usually starts making sense once your business profit consistently clears roughly $80,000 to $100,000, and the case strengthens as profit grows. The savings come only from the profit above your reasonable salary — the part you can take as distributions, which escape the ~15.3% self-employment tax — so below that range there's little left to shield after a reasonable salary, and the added costs (payroll, a separate 1120-S return, admin) tend to eat what savings remain. It's not a hard line, though: your profit, a defensible salary for your role, and your state all move it. Run your specific numbers before deciding.
How much does an S-corp actually save?
It depends on how much profit sits above your reasonable salary. That distribution bucket escapes the self-employment/payroll tax a default LLC pays on its profit. For an owner netting $150,000 who pays a $70,000 salary, the gross saving works out to about $10,300 — and after the roughly $1,500–$3,000 a year it costs to run an S-corp (payroll service, the extra tax return, cleaner books), net savings land around $8,000. At higher incomes the Social Security wage-base cap shrinks the marginal saving on distributions to the Medicare portion, so the exact figure really is specific to you. A calculator that models your salary and profit is the way to get your real number.
What is a reasonable salary for an S-corp owner?
A reasonable salary is reasonable pay for the work you actually do in the business — roughly what you'd have to pay someone else to do your job, based on your duties, hours, experience, and local wage data for your role. The IRS requires an owner who works in the business to take this salary through payroll before taking distributions, and an unreasonably low salary is a known audit trigger. If distributions get reclassified as wages, you owe the back payroll tax plus penalties and interest. The goal is a defensible number — not the lowest you can imagine — which is exactly what our S-Corp reasonable-salary calculator is built to produce from real wage data.
Is an S-corp a type of company or a tax election?
It's a tax election, not a type of company. You don't go form an 'S-corp' — you keep your existing business (commonly an LLC) and file IRS Form 2553 asking the IRS to tax it as an S-corp. On the outside nothing has to change: same LLC, same bank account, same contracts. What changes is how the profit is taxed — specifically, your ability to split it into a salary and distributions, with the distributions escaping self-employment tax. That's why the decision is about math and timing rather than paperwork for a brand-new entity.
When is the deadline to elect S-corp status?
To have the election apply for the current tax year, you generally must file Form 2553 within about two months and fifteen days of the start of that year — March 15 for a calendar-year business. If you miss it, late-election relief is often available when you qualify, but it's a backstop, not a plan. Because the deadline is firm and the setup (payroll, a reasonable salary, clean books) takes a little lead time, it's worth deciding well before March. We cover the timing and the traps in detail in our S-Corp Election Deadline article.
Can 406 Consulting Group set up my S-corp and run the payroll?
Yes. We run the reasonable-salary and savings math for your specific situation, make the election (Form 2553) at the right time, set up and run the payroll the S-corp requires, file the 1120-S return, and keep the books clean enough to defend the salary — all remotely, for clients across the country. Because the whole strategy lives or dies on getting the salary right and the payroll actually running, having one firm own the election, the payroll, and the books together is how you capture the savings without inviting a problem. Start with the calculator, then talk to us.
Sam's Numbers
Contractor netting $150K
Illustrative. Your number depends on profit + salary + state.
Run Your Numbers
Free S-Corp calculator.
About the Author
Jason Anderson
Co-Founder, 406 Consulting Group
Big-firm-trained accountant who has run the S-corp math for hundreds of owners — and handles the election, the reasonable-salary analysis, and the payroll that has to come with it. Delivered remotely.
Read the Full Story