
Accounting for Tampa Small Business:
Which Help You Need, and When
Accounting is really four functions — bookkeeping, tax, controller, and CFO. This is the map: which one your Tampa business needs, in what order, and how to choose a partner who connects them and reads your numbers like a lender.
Running a small business in Tampa means competing in the fastest-growing major metro in Florida — healthcare, financial services, a real tech scene, Port Tampa Bay logistics, tourism, and a construction boom feeding all of it, plus a steady influx of companies relocating from higher-tax states. Florida makes part of it easy with no personal income tax. But the businesses that make the most of Tampa treat their accounting not as a once-a-year chore but as the system that tells them what's working, funds their growth, and keeps them out of trouble with Florida's own rules — the corporate tax, the surtax, and the insurance reality among them.
This is the overview — the map. Rather than repeat our deep-dive articles, it answers the question owners actually ask first: which kind of accounting help do I need, in what order, and how do I choose the right partner? The detailed guides on bookkeeping, tax, CFO & controller work, and construction accounting go a level deeper on each.
By Carrie Anderson — Co-Founder, 406 Consulting Group. Former commercial banker who has reviewed hundreds of businesses' financials from the lender's side of the table — now helping Tampa owners build the accounting that supports real growth.
Quick Answer: Accounting for a Tampa Small Business
- →There are four functions: bookkeeping, tax, controller, and CFO/advisory — most owners only buy the first two and stall.
- →Buy them in sequence: reliable books first, proactive (federal-first) tax next, then control and strategy as you grow.
- →Florida has no personal income tax but its own rules — the 5.5% C-corp tax, sales-plus-surtax, and heavy insurance costs — that reward planning.
- →Choose a partner who connects the functions and reads financials the way a lender does — not four disconnected vendors.
- →The right partner can be remote — about 80% of our local clients already work that way.
Table of Contents
The Tampa Small-Business Landscape
Tampa's economy runs on healthcare, financial services, logistics, tourism, tech, and a construction boom serving all of it — and it moves fast. That means two things for a small business. First, the competition is real and often well-capitalized, so thin margins and sloppy numbers get punished. Second, because Tampa is a growing business and banking hub, a company with clean, credible financials can reach for growth capital that owners in smaller markets can only wish for. Your accounting is what decides which side of that line you're on.
In a fast, capital-rich metro, your books are more than a record — they're the application. Someone with lending authority will eventually read them, and what they see decides what you can build next.
So what does "good accounting" actually consist of? It breaks into four distinct functions.
The Four Functions Every Business Needs
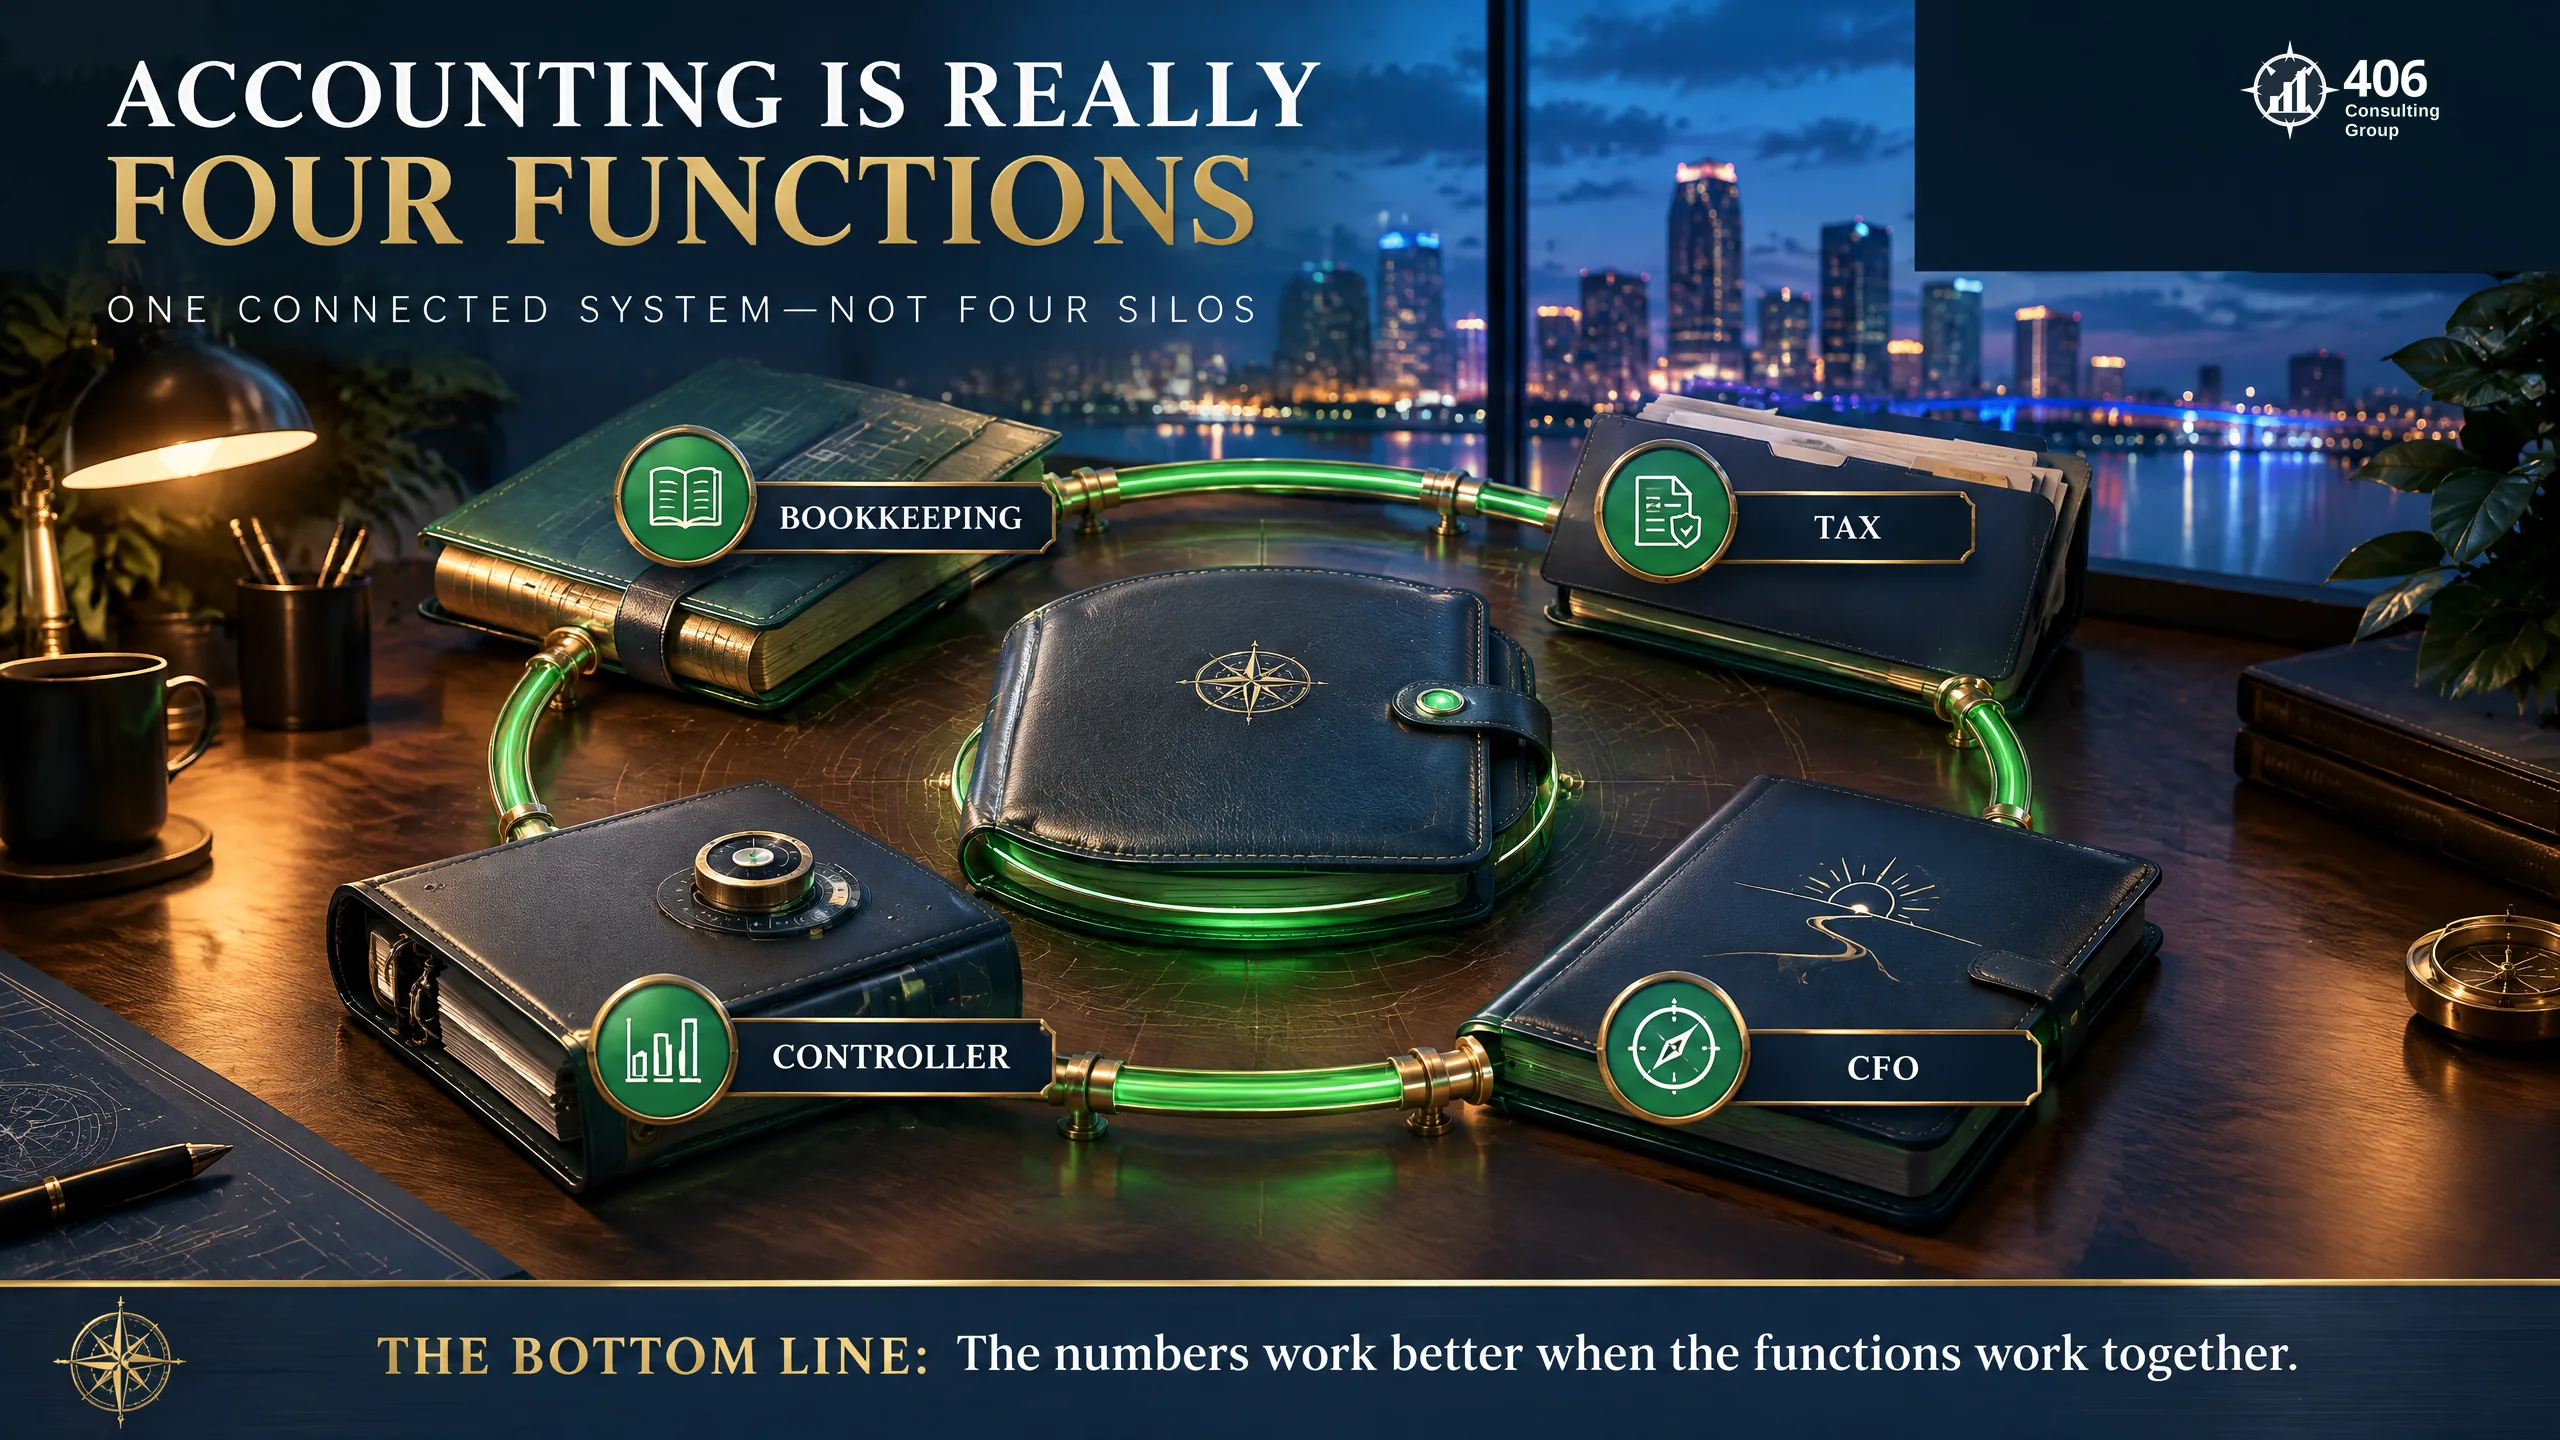
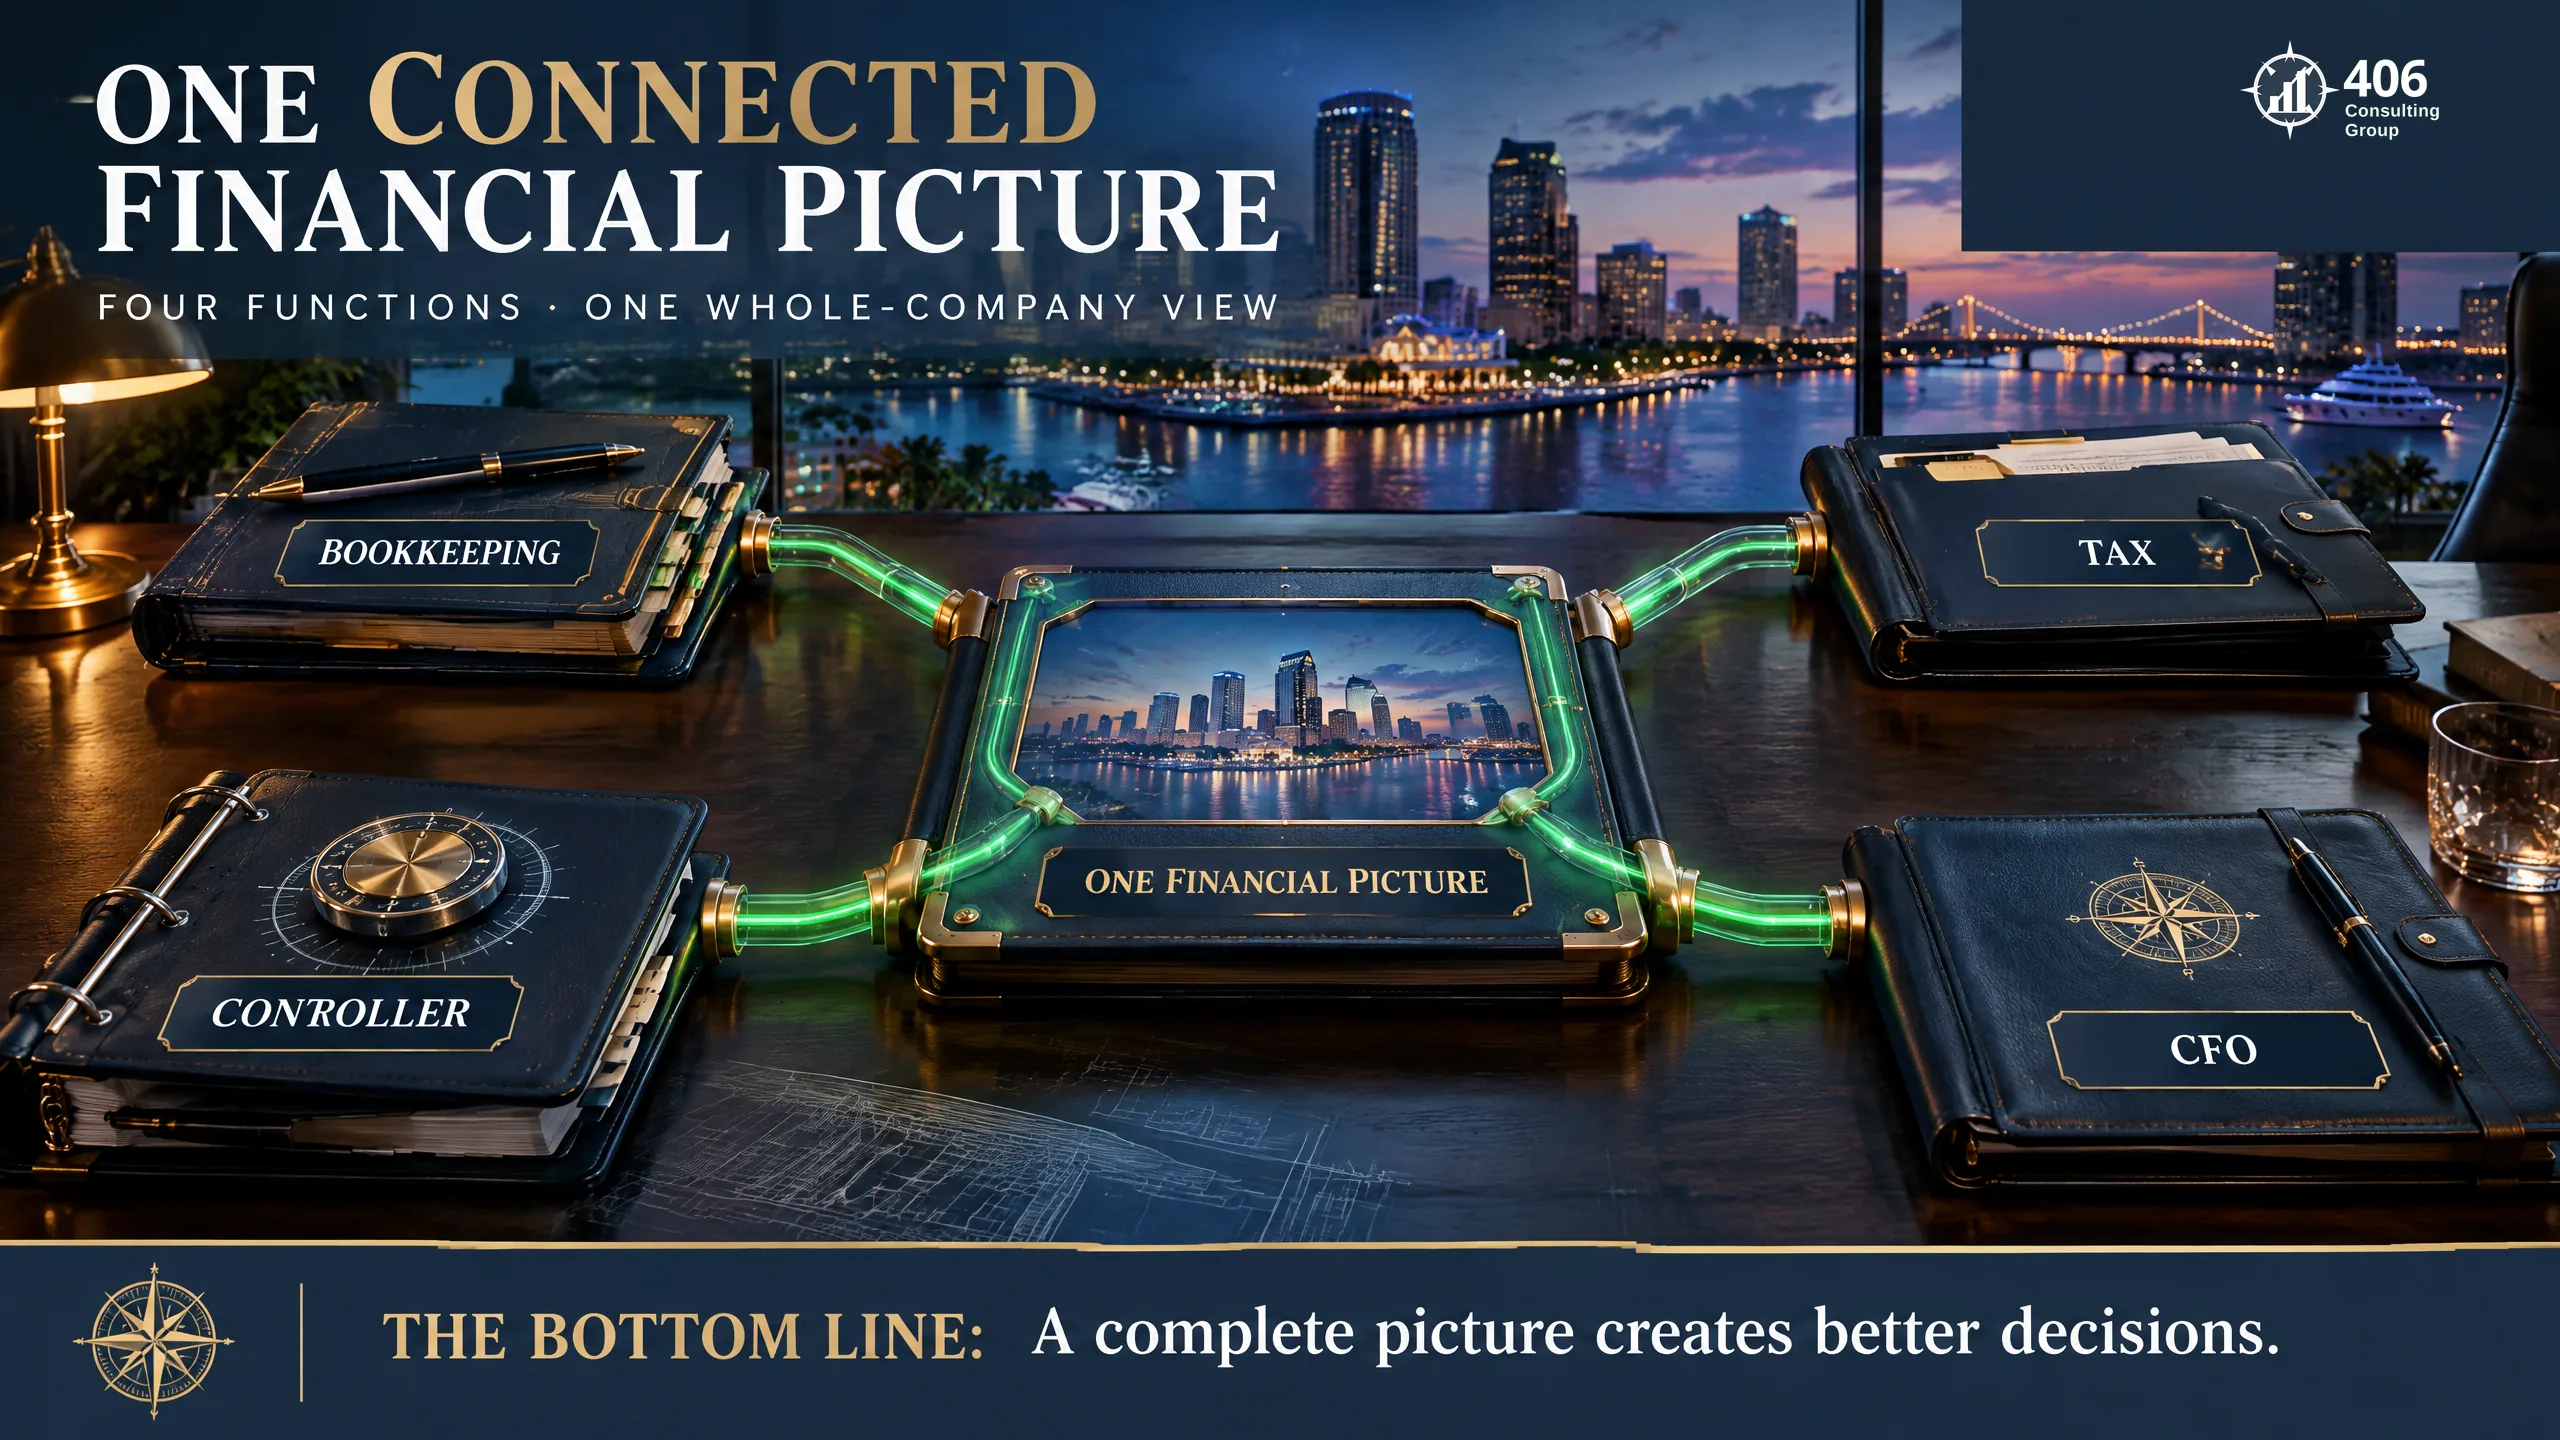
"Accounting" is really four jobs, and most owners only buy the first two — which is exactly why they plateau. Knowing the full set tells you what you're missing.
Bookkeeping
Records and reconciles every transaction — the clean foundation everything else stands on.
Tax
Proactive, federal-first planning — the S-corp election, depreciation, and Florida's C-corp and surtax rules.
Controller
Makes the numbers reliable and on time — a real monthly close and true job-level profit.
CFO / Advisory
Turns numbers into strategy — forecasting for seasons and storms, pricing, and capital planning.
You don't need all four on day one. You need them in the right order.
What You Need, and When
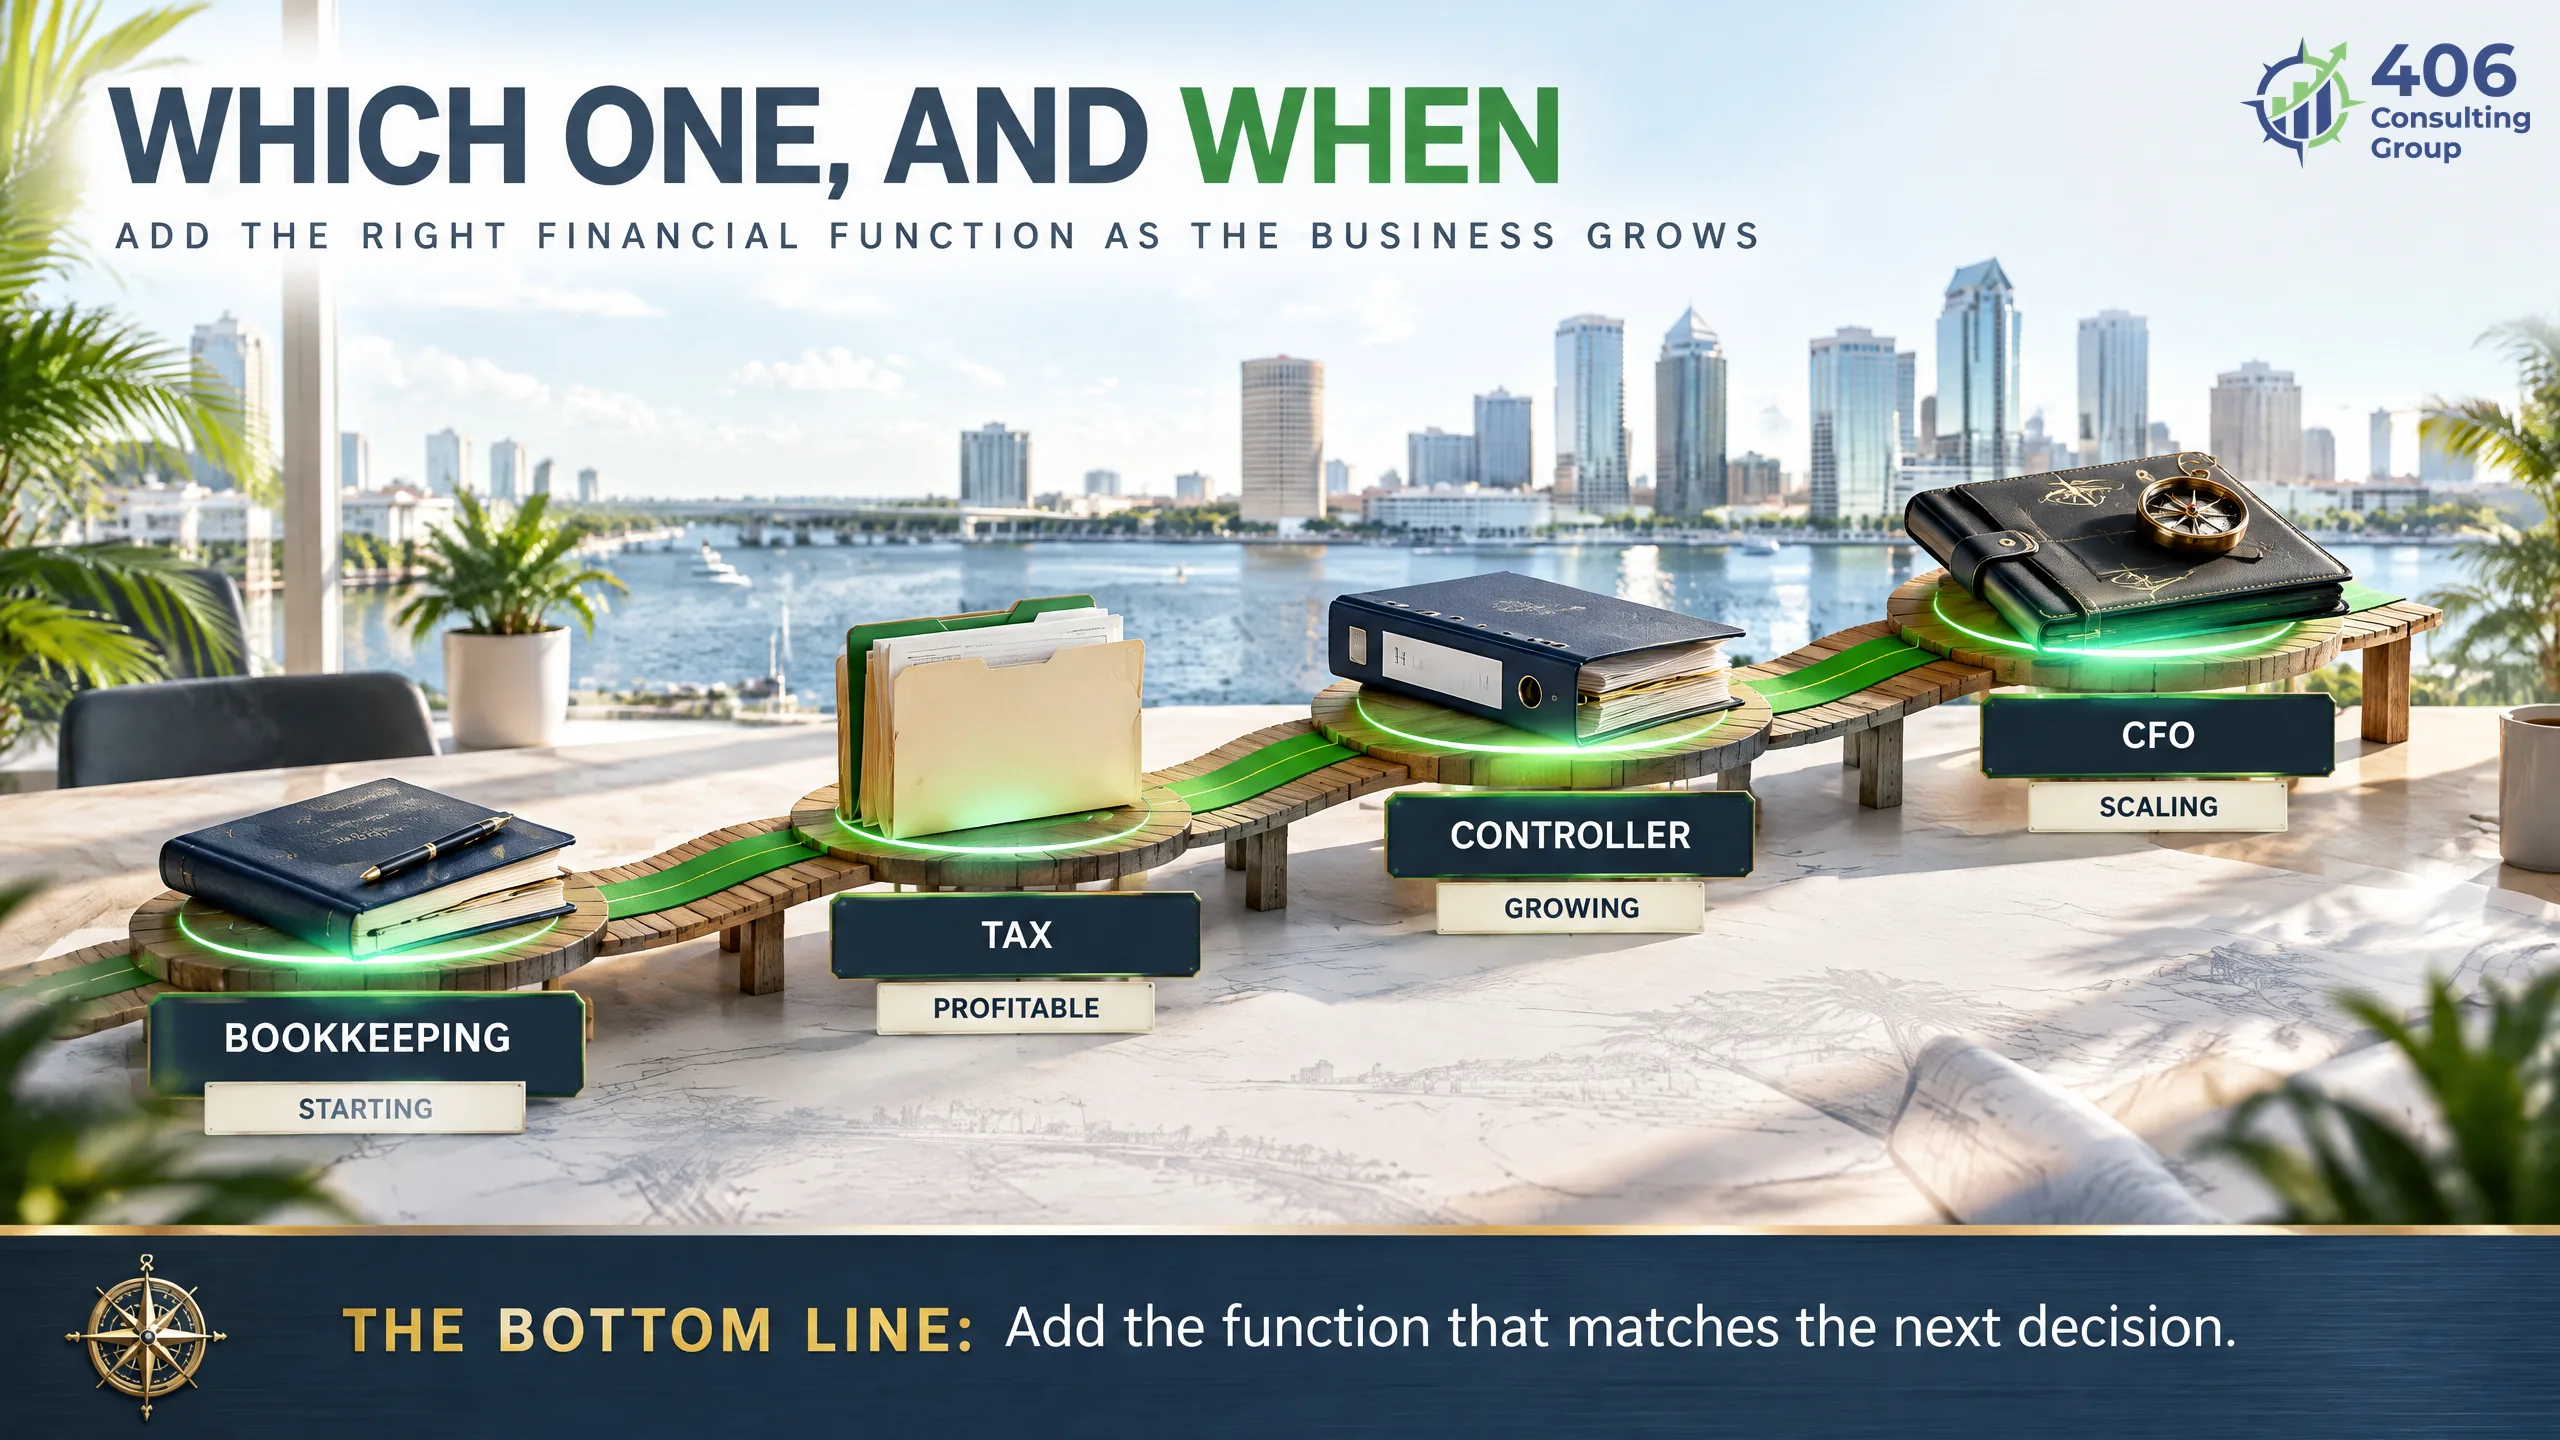
The mistake we see most is buying out of order — an owner hiring a "CFO" while the books are still a mess, or chasing tax strategies on numbers no one trusts. Strategy built on unreliable numbers is just expensive guessing. The sequence that works: get the bookkeeping reliable, layer in proactive tax planning so you stop overpaying federally, bring in controller discipline once decisions depend on timely numbers, and add CFOstrategy when you're forecasting, pricing, and reaching for capital.
Just starting / small
Reliable bookkeeping + a tax filer who won't miss the surtax or reemployment filings.
Profitable & growing
Proactive federal tax planning (the S-corp election) + a real monthly close.
Scaling / borrowing
Controller discipline + fractional CFO forecasting (for seasons and storms) and capital work.
Wherever you are on that path, Florida adds a few rules worth planning around.
The Florida Realities to Plan For
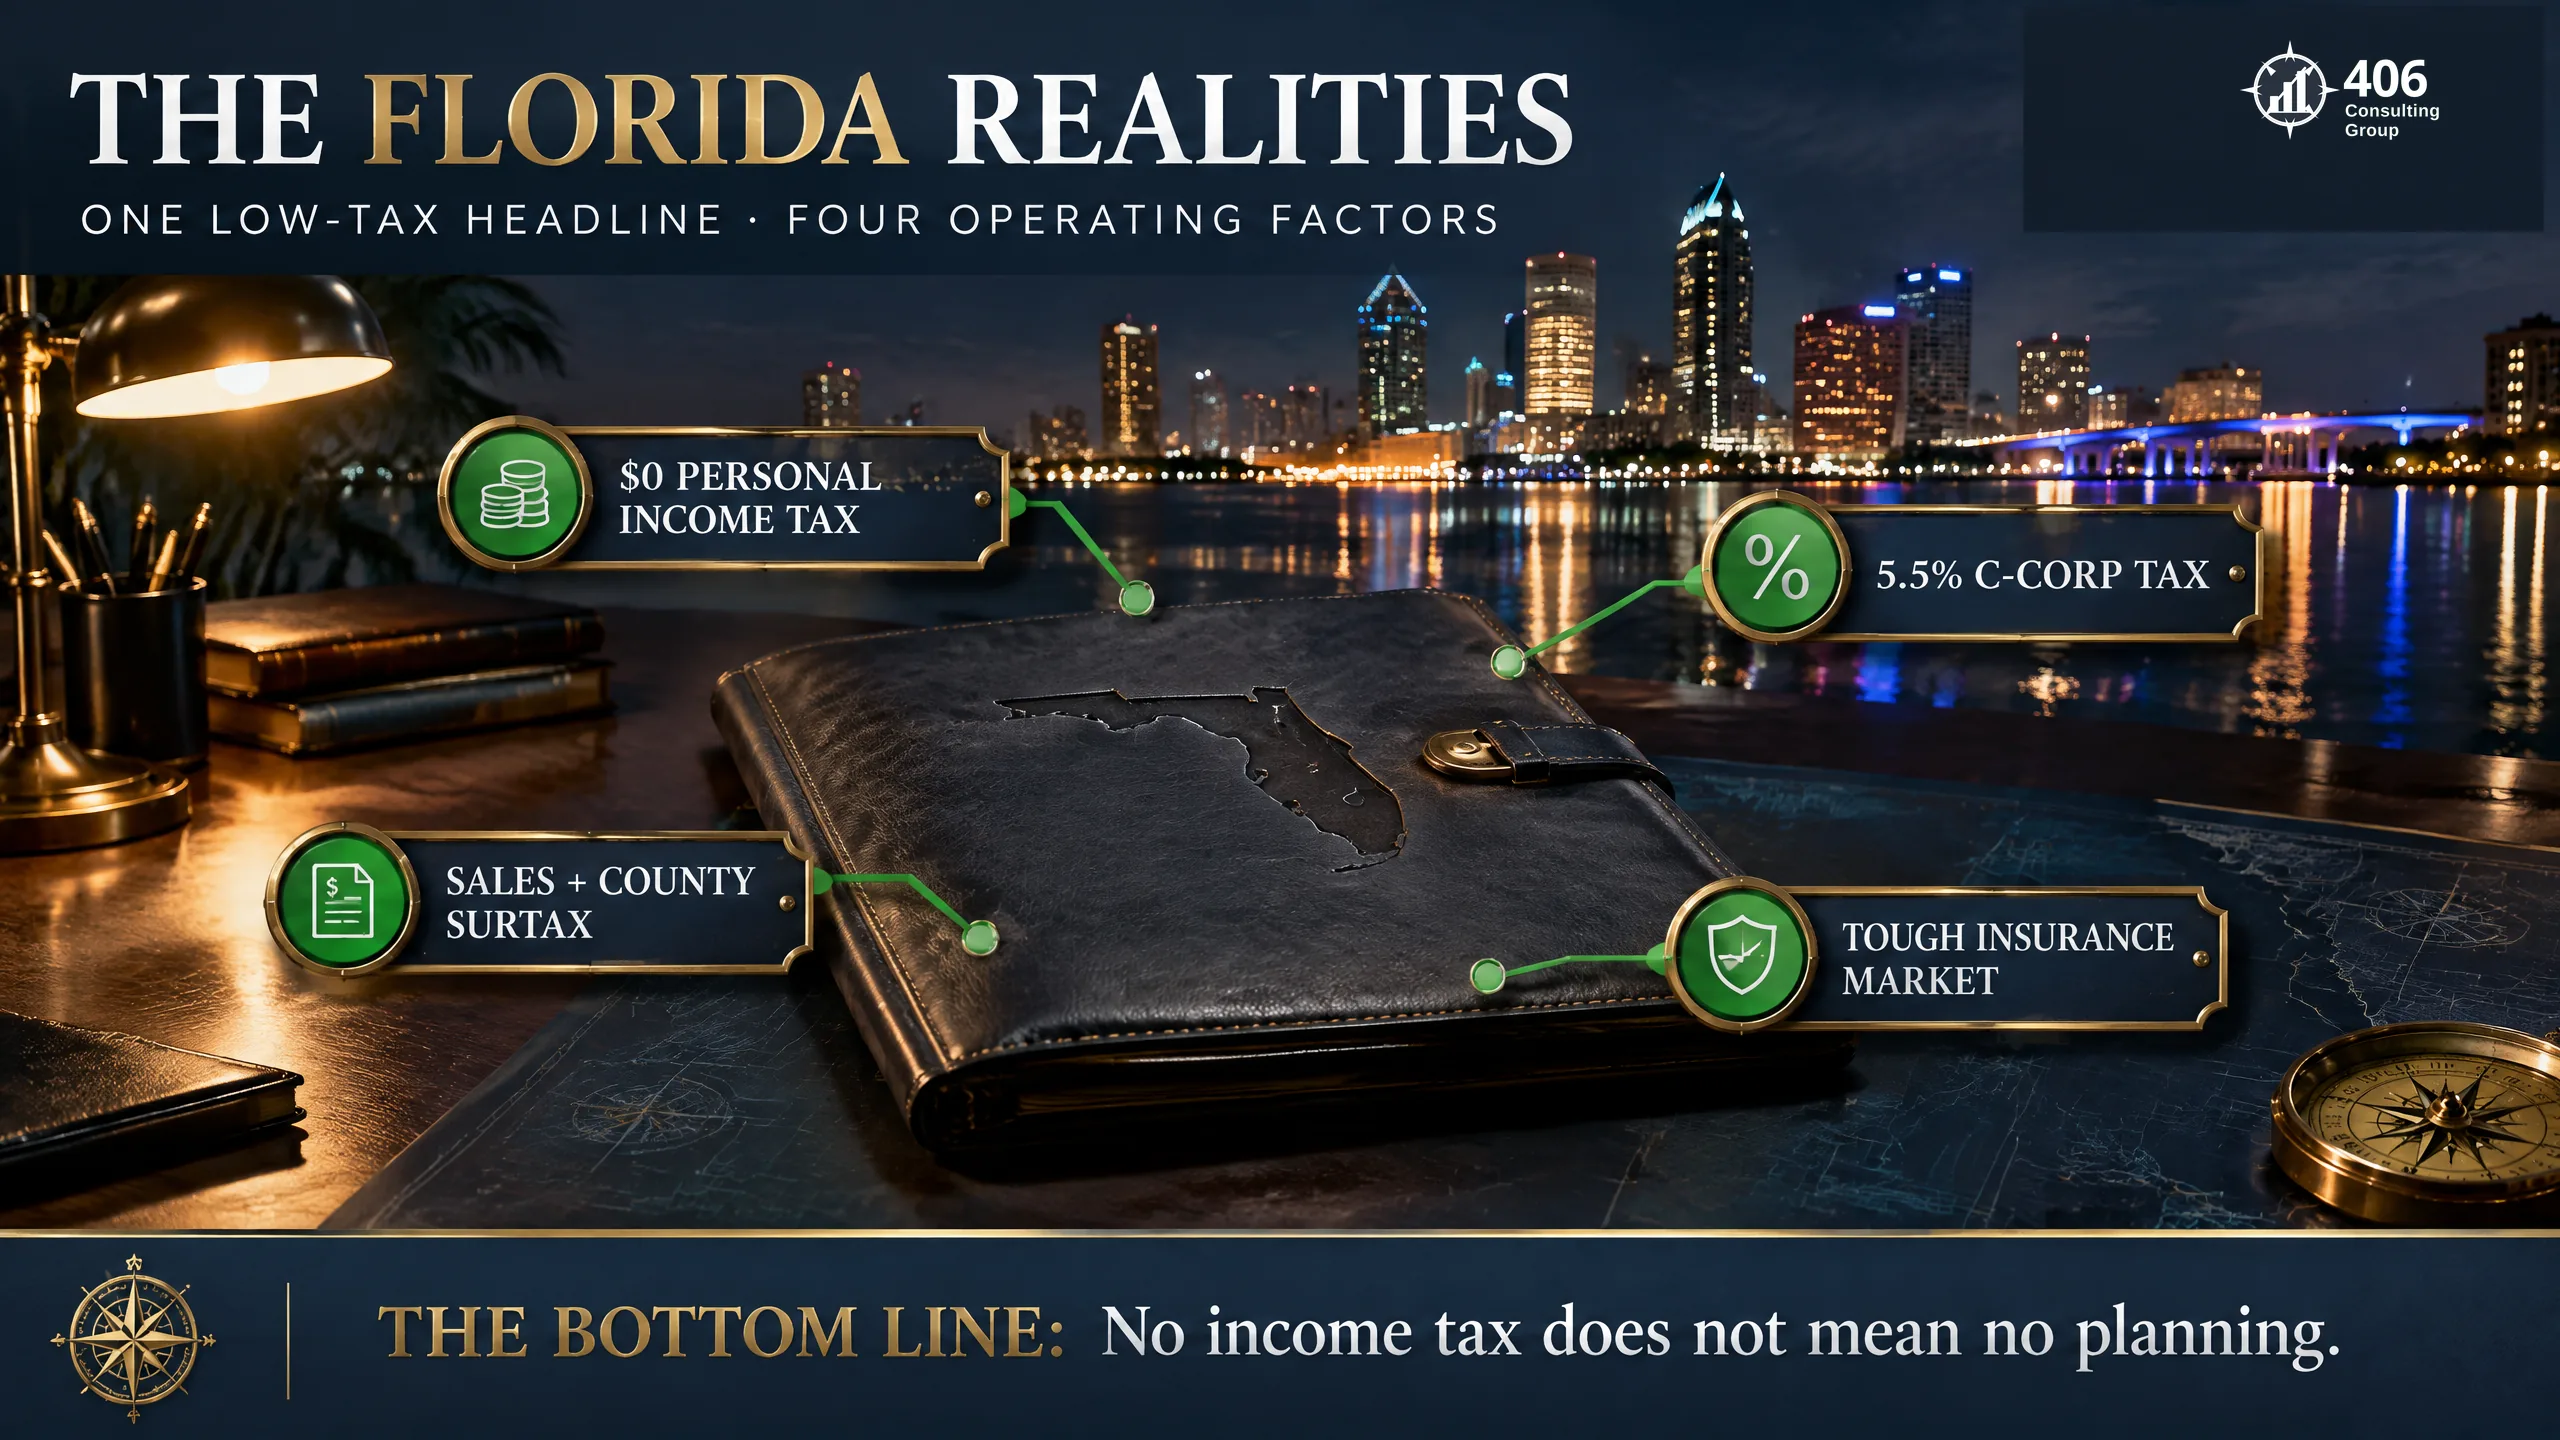
Florida is genuinely tax-friendly, with no personal income tax, but it has its own wrinkles. The 5.5% corporate income tax on C-corporations quietly changes the entity math for anyone who incorporated that way. Sales tax plus a county surtax (around 7.5% in Hillsborough County) trips up owners who treat collected tax as cash or forget use tax. Property insurance is a major, volatile cost that belongs in every forecast, and seasonality plus hurricane risk make cash reserves a real planning question. Because there's no personal income tax, your income-tax planning is federal. None of these are reasons to panic; they're reasons to have someone who plans around them.
Always confirm current specifics with the Florida Department of Revenue — and, more usefully, with an advisor who plans ahead. Which raises the real question: how do you pick that advisor?
How to Choose an Accounting Partner
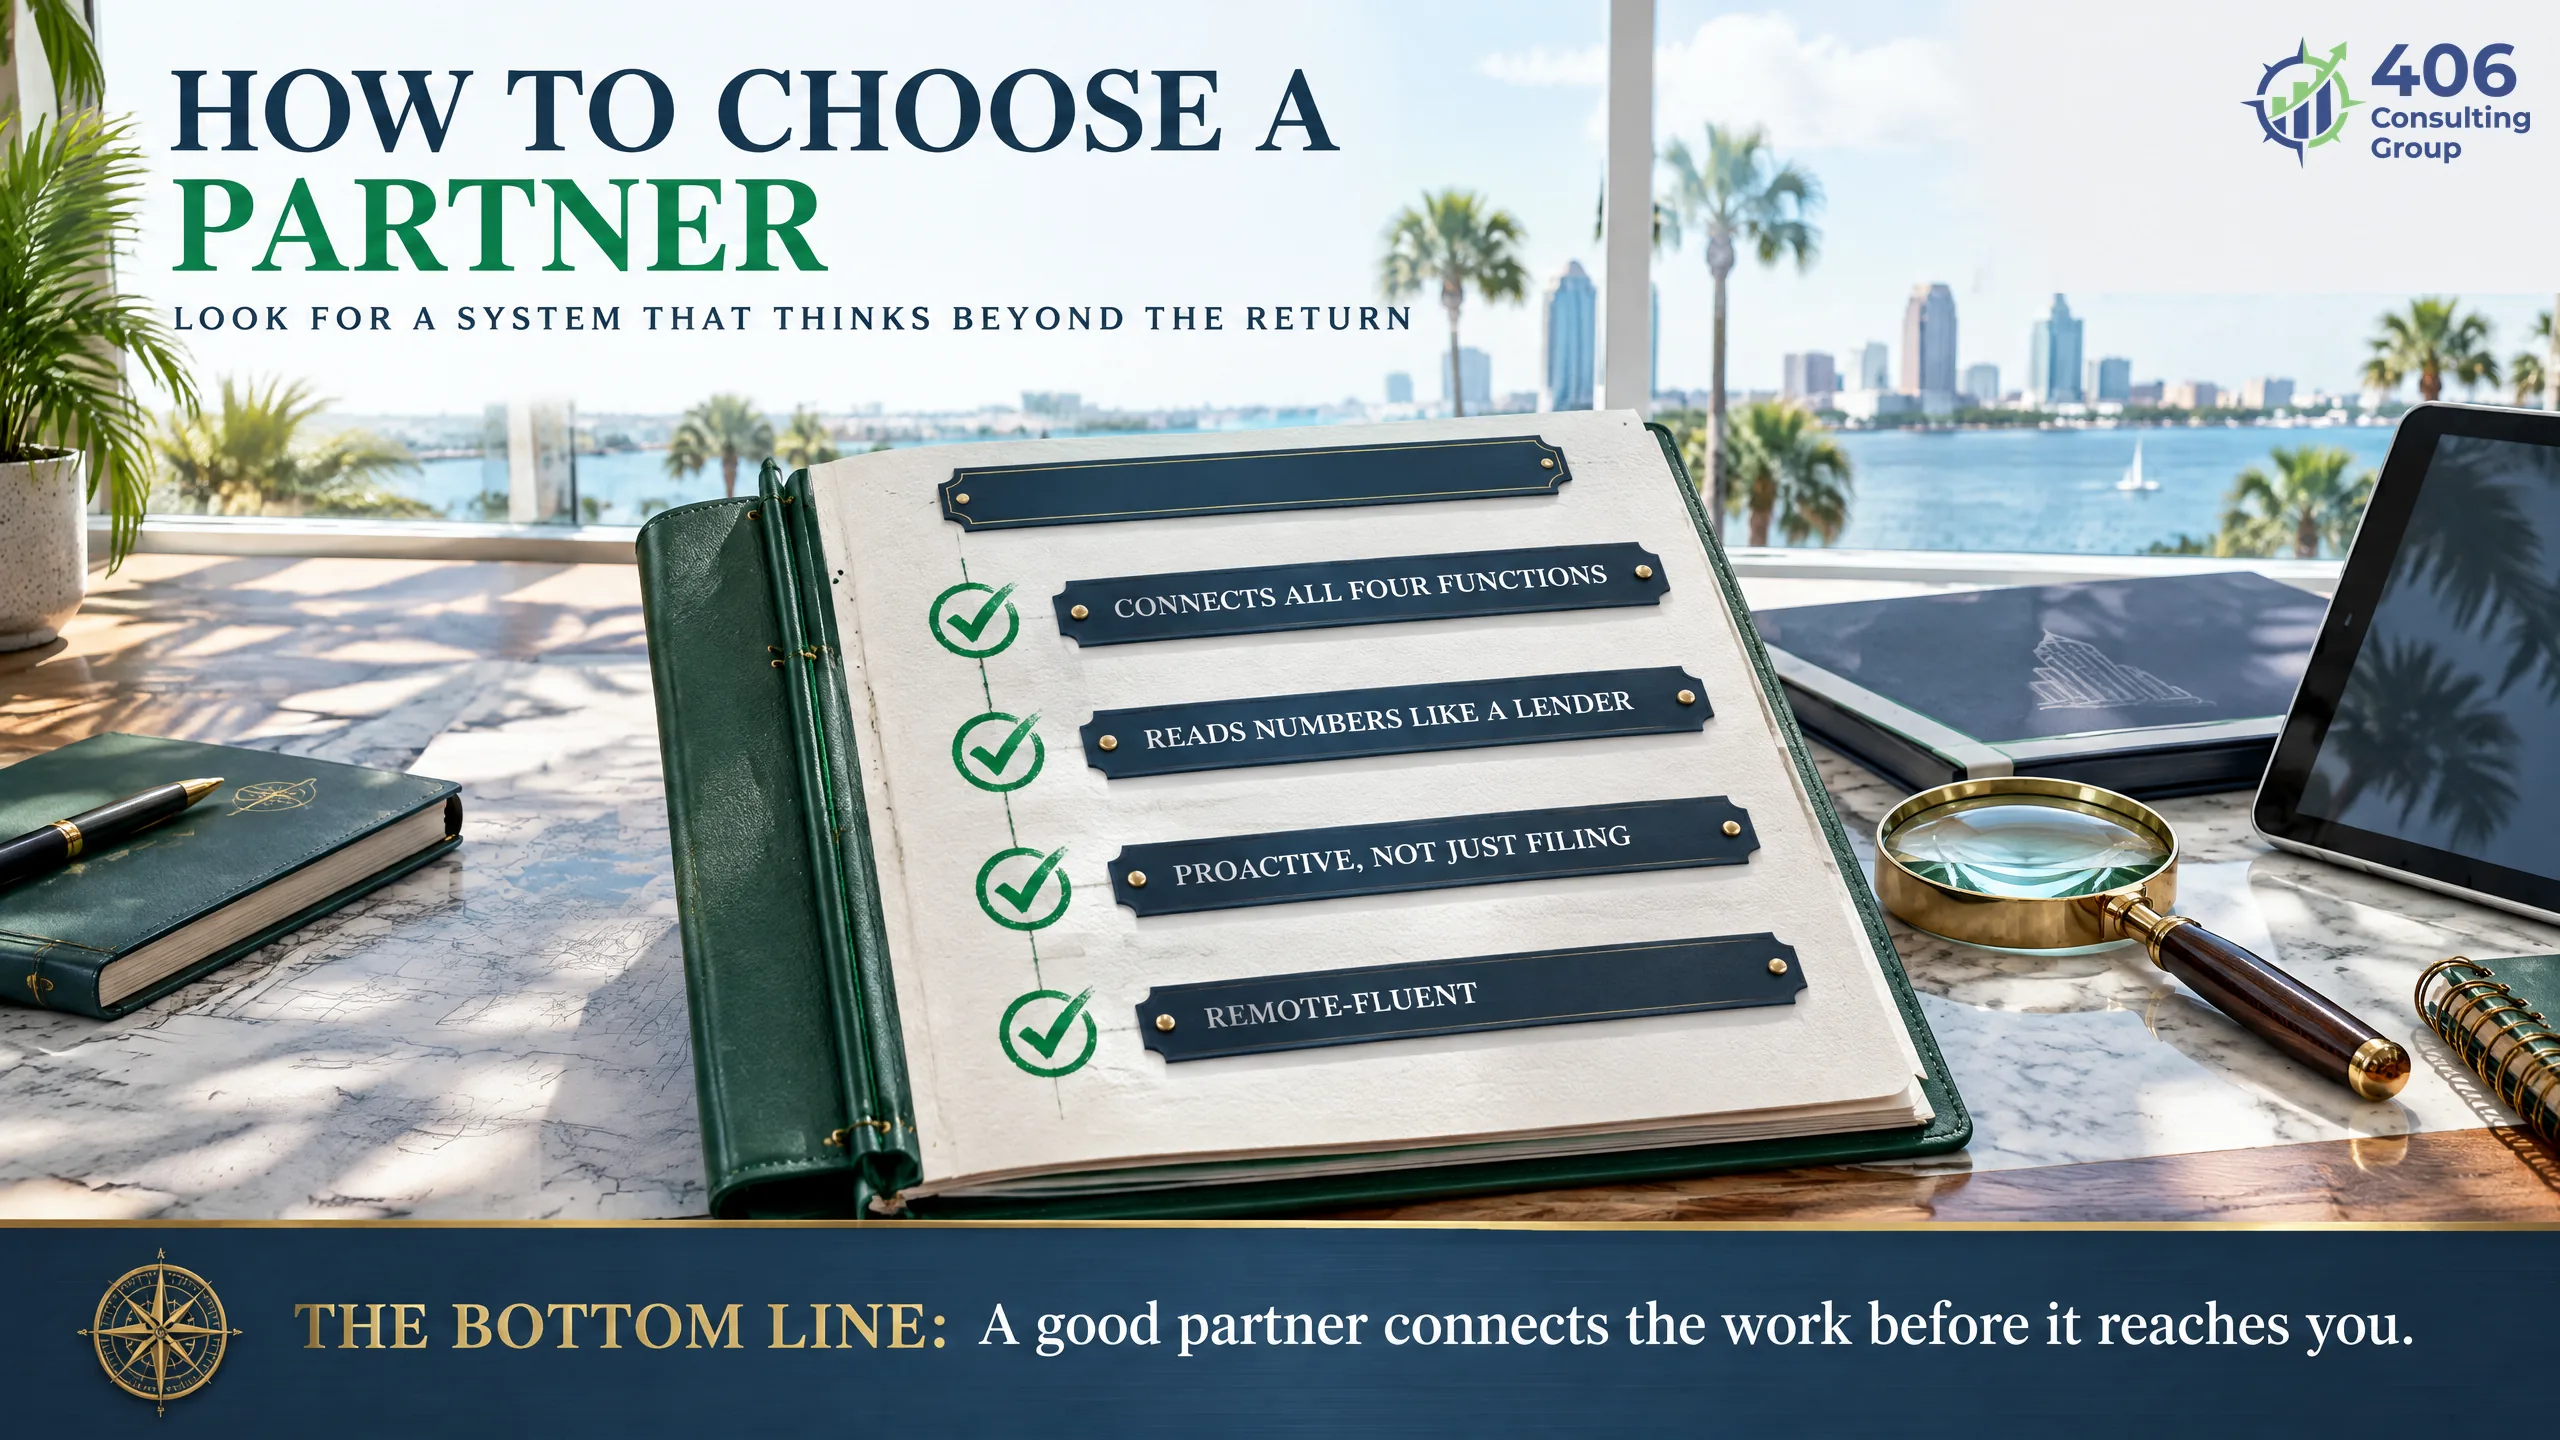
The most common failure isn't hiring a bad bookkeeper or a bad tax preparer — it's hiring four disconnected ones. When your bookkeeper, tax preparer, and whoever gives you advice don't talk to each other, the gaps between them are where money leaks and opportunities die. The best partner treats the four functions as one connected system, so a tax decision reflects your real books and a growth plan reflects your real tax picture. In a hub economy, add one more test: does this partner understand how a lender reads your numbers?
Five questions to ask a prospective partner
- 1.Do you connect bookkeeping, tax, and advisory — or just do one piece?
- 2.Can you give me a real monthly close, not just a year-end scramble?
- 3.Do you plan taxes proactively (the S-corp election, entity choice, depreciation) or only file them?
- 4.Have you prepared financials that lenders and bonding companies actually read?
- 5.Will you design around how my whole business runs, not just the accounting?
That standard also tells you when it's time to stop doing it yourself.
When to Graduate From DIY
Doing your own books in the earliest days is normal and fine. The signs it's costing you more than it saves are consistent: you're doing the books at 11 p.m. instead of selling or serving, you can't confidently say whether last month made money, tax time is a panic, and you suspect you're overpaying but don't know where. When the hours you pour into the books are worth more spent running the business — and when a mistake in them could cost you real money or a loan — you've outgrown DIY. The goal was never to save the bookkeeping fee; it was to make more than the fee with the time and clarity you get back.
What separates a great partner from an adequate one is how far past the numbers they think.
The Whole-Company Systems Advantage
Most accounting help looks at your business through an accounting-only lens. We design financial systems from a whole-company, cross-departmental view— how sales, operations, and the field actually create and spend money — so the numbers connect to how the business really runs, and the reports answer questions an owner actually has. It's the difference between an accountant who hands you statements and a partner who helps you build a company that runs on clean information. That systems mindset is what turns accounting from overhead into an advantage.
And none of it requires the partner to be down the street — a point our own client base proves every day.
Remote by Default — Even for Locals
It's natural to assume a Tampa business needs a Tampa accountant down the road. But the strongest evidence against that is our own client base: roughly 80% of our local clients handle the entire relationship remotelyand never come into the office. People who could drop by choose screen-shares, a document portal, and regular calls instead — because modern accounting is cloud-based and collaborative, and what actually matters is the expertise and how connected the work is, not the drive time. A great remote partner who plans your taxes, runs a real close, and prepares lender-ready financials beats an okay local one who just files a return.
~80%
of our local clients are fully remote
If the clients next door run it remotely, distance is a non-issue.
Here's how the full Tampa series fits together.
The Tampa Accounting Series
Each guide below goes a level deeper on one function. Start wherever your biggest gap is.
Bookkeeping Services in Tampa, FL
Clean books, the C-corp tax, the county surtax, reemployment tax, and insurance tracking.
Tax Services in Tampa, FL
Federal-first planning, the S-corp election, the C-corp nuance, and relocation cleanup.
CFO & Controller Services in Tampa, FL
Reliable numbers, forecasting for seasons and storms, and funding growth.
Construction Accounting in Tampa, FL
Job costing, WIP, Florida licensing and workers' comp, and the numbers bonding companies need.
Not sure where to start?
Take the Financial Maturity Assessment and we'll show you which rung you're on — and the one function that will move your Tampa business furthest right now.
FAQ: Accounting for Tampa Small Business
How much does accounting cost for a small business in Tampa?
It depends on which of the four functions you need and how complex your business is. Basic monthly bookkeeping for a straightforward small business is modest; layering in proactive tax planning, a real monthly close, and fractional CFO strategy costs more because it does far more. The better way to think about it isn't price but return: good bookkeeping and federal tax planning routinely pay for themselves in taxes saved and mistakes avoided, and CFO-level work is judged by the decisions and financing it unlocks. Beware the cheapest option that only files once a year — it's usually the most expensive once you count what it misses, like a mishandled surtax or a skipped S-corp election.
Do I need a CPA, a bookkeeper, or a full accounting firm?
Most small businesses need more than one of those, which is exactly the problem with hiring them separately. A bookkeeper keeps the records; a CPA or tax professional handles planning and returns; a controller and CFO make the numbers reliable and strategic. Hiring them as disconnected vendors leaves gaps between them where money leaks. A firm that connects all four functions — and reads your numbers the way a lender does — gives you one coherent financial picture instead of three partial ones. That integration, more than any single credential, is what actually moves the needle.
When should a Tampa business hire an accountant instead of doing it themselves?
When the time you spend on the books is worth more spent running the business, or when a mistake could cost you real money or a loan. Concretely: you're doing books late at night instead of selling, you can't confidently say whether last month was profitable, tax season is a panic, or you're about to approach a lender. In a fast-growing metro especially, the moment you're reaching for capital is the moment amateur books start costing you — a lender's read of your financials directly affects what you can borrow and on what terms.
What makes accounting different in Tampa specifically?
Two things. First, Florida's own rules — no personal income tax (so income-tax planning is federal), a 5.5% corporate income tax on C-corporations, sales tax plus a county surtax around 7.5% in Hillsborough County, reemployment tax on payroll, and the nation's toughest property-insurance market. Second, Tampa's identity as a fast-growing hub and a magnet for relocation from higher-tax states: growth capital is within reach, but only for businesses whose financials can earn it, and relocating companies often need multi-state cleanup. That combination rewards accounting that plans federally, handles Florida's taxes, and prepares your numbers for a lender.
Can a Tampa business use a remote accounting firm?
Yes — and increasingly it's the norm. In fact, around 80% of our own local clients run the entire relationship remotely and never come into the office. Modern accounting runs on cloud software, shared books, and video planning calls, so the work happens the same whether your accountant is in Tampa or across the country. What matters is expertise, responsiveness, and how well the functions connect — a great remote partner who plans your taxes and prepares lender-ready financials beats an okay local one who only files a return. We serve Tampa and Florida entirely remotely.
The Four Functions
Which are you missing?
Tampa Accounting
One connected system, remote.
About the Author
Carrie Anderson
Co-Founder, 406 Consulting Group
A former commercial banker, Carrie reviewed hundreds of businesses' financials from the lender's side of the table. She helps Tampa owners build accounting that saves tax and supports real growth.
Read the Full Story