
Construction & Trades Accounting in Tampa, FL:
Job Costing, Licensing & Bonding
Tampa is booming, and construction is where a busy company can still go broke. This is job costing, WIP, Florida's strict licensing and mandatory workers' comp, the insurance-and-storm reality, retainage, and bonding — the numbers that let a contractor bid bigger, built remotely.
Tampa is one of the busiest construction markets in the country — subdivisions and towers, warehouses and medical campuses, and a steady rebuild-and-harden cycle driven by the weather. It's a great time to be a contractor here, and a dangerous one, because construction is the industry where a company can be slammed with work and still go broke. Florida adds its own demands: some of the strictest state contractor licensing in the country, mandatory workers' compin construction, and building costs shaped by the toughest insurance market in the nation. The difference between the builders who scale and the ones who stall is almost never the work — it's the numbers behind it.
This guide covers what makes construction accounting its own discipline, the Florida rules that catch contractors off guard, and how a Tampa builder gets books that grow the business instead of just recording it — all delivered remotely.
By Jason Anderson — Co-Founder, 406 Consulting Group. Big-firm-trained accountant with deep trades and oilfield experience who builds job-costing, WIP, and license- and bond-ready financials for construction companies — designed from a whole-company view.
Quick Answer: Construction Accounting in Tampa
- →Construction needs job costing and WIP — you must know true profit per project, not just company-wide.
- →Florida licenses contractors through the state (DBPR), and qualifying takes proof of financial responsibility — your books are part of the application.
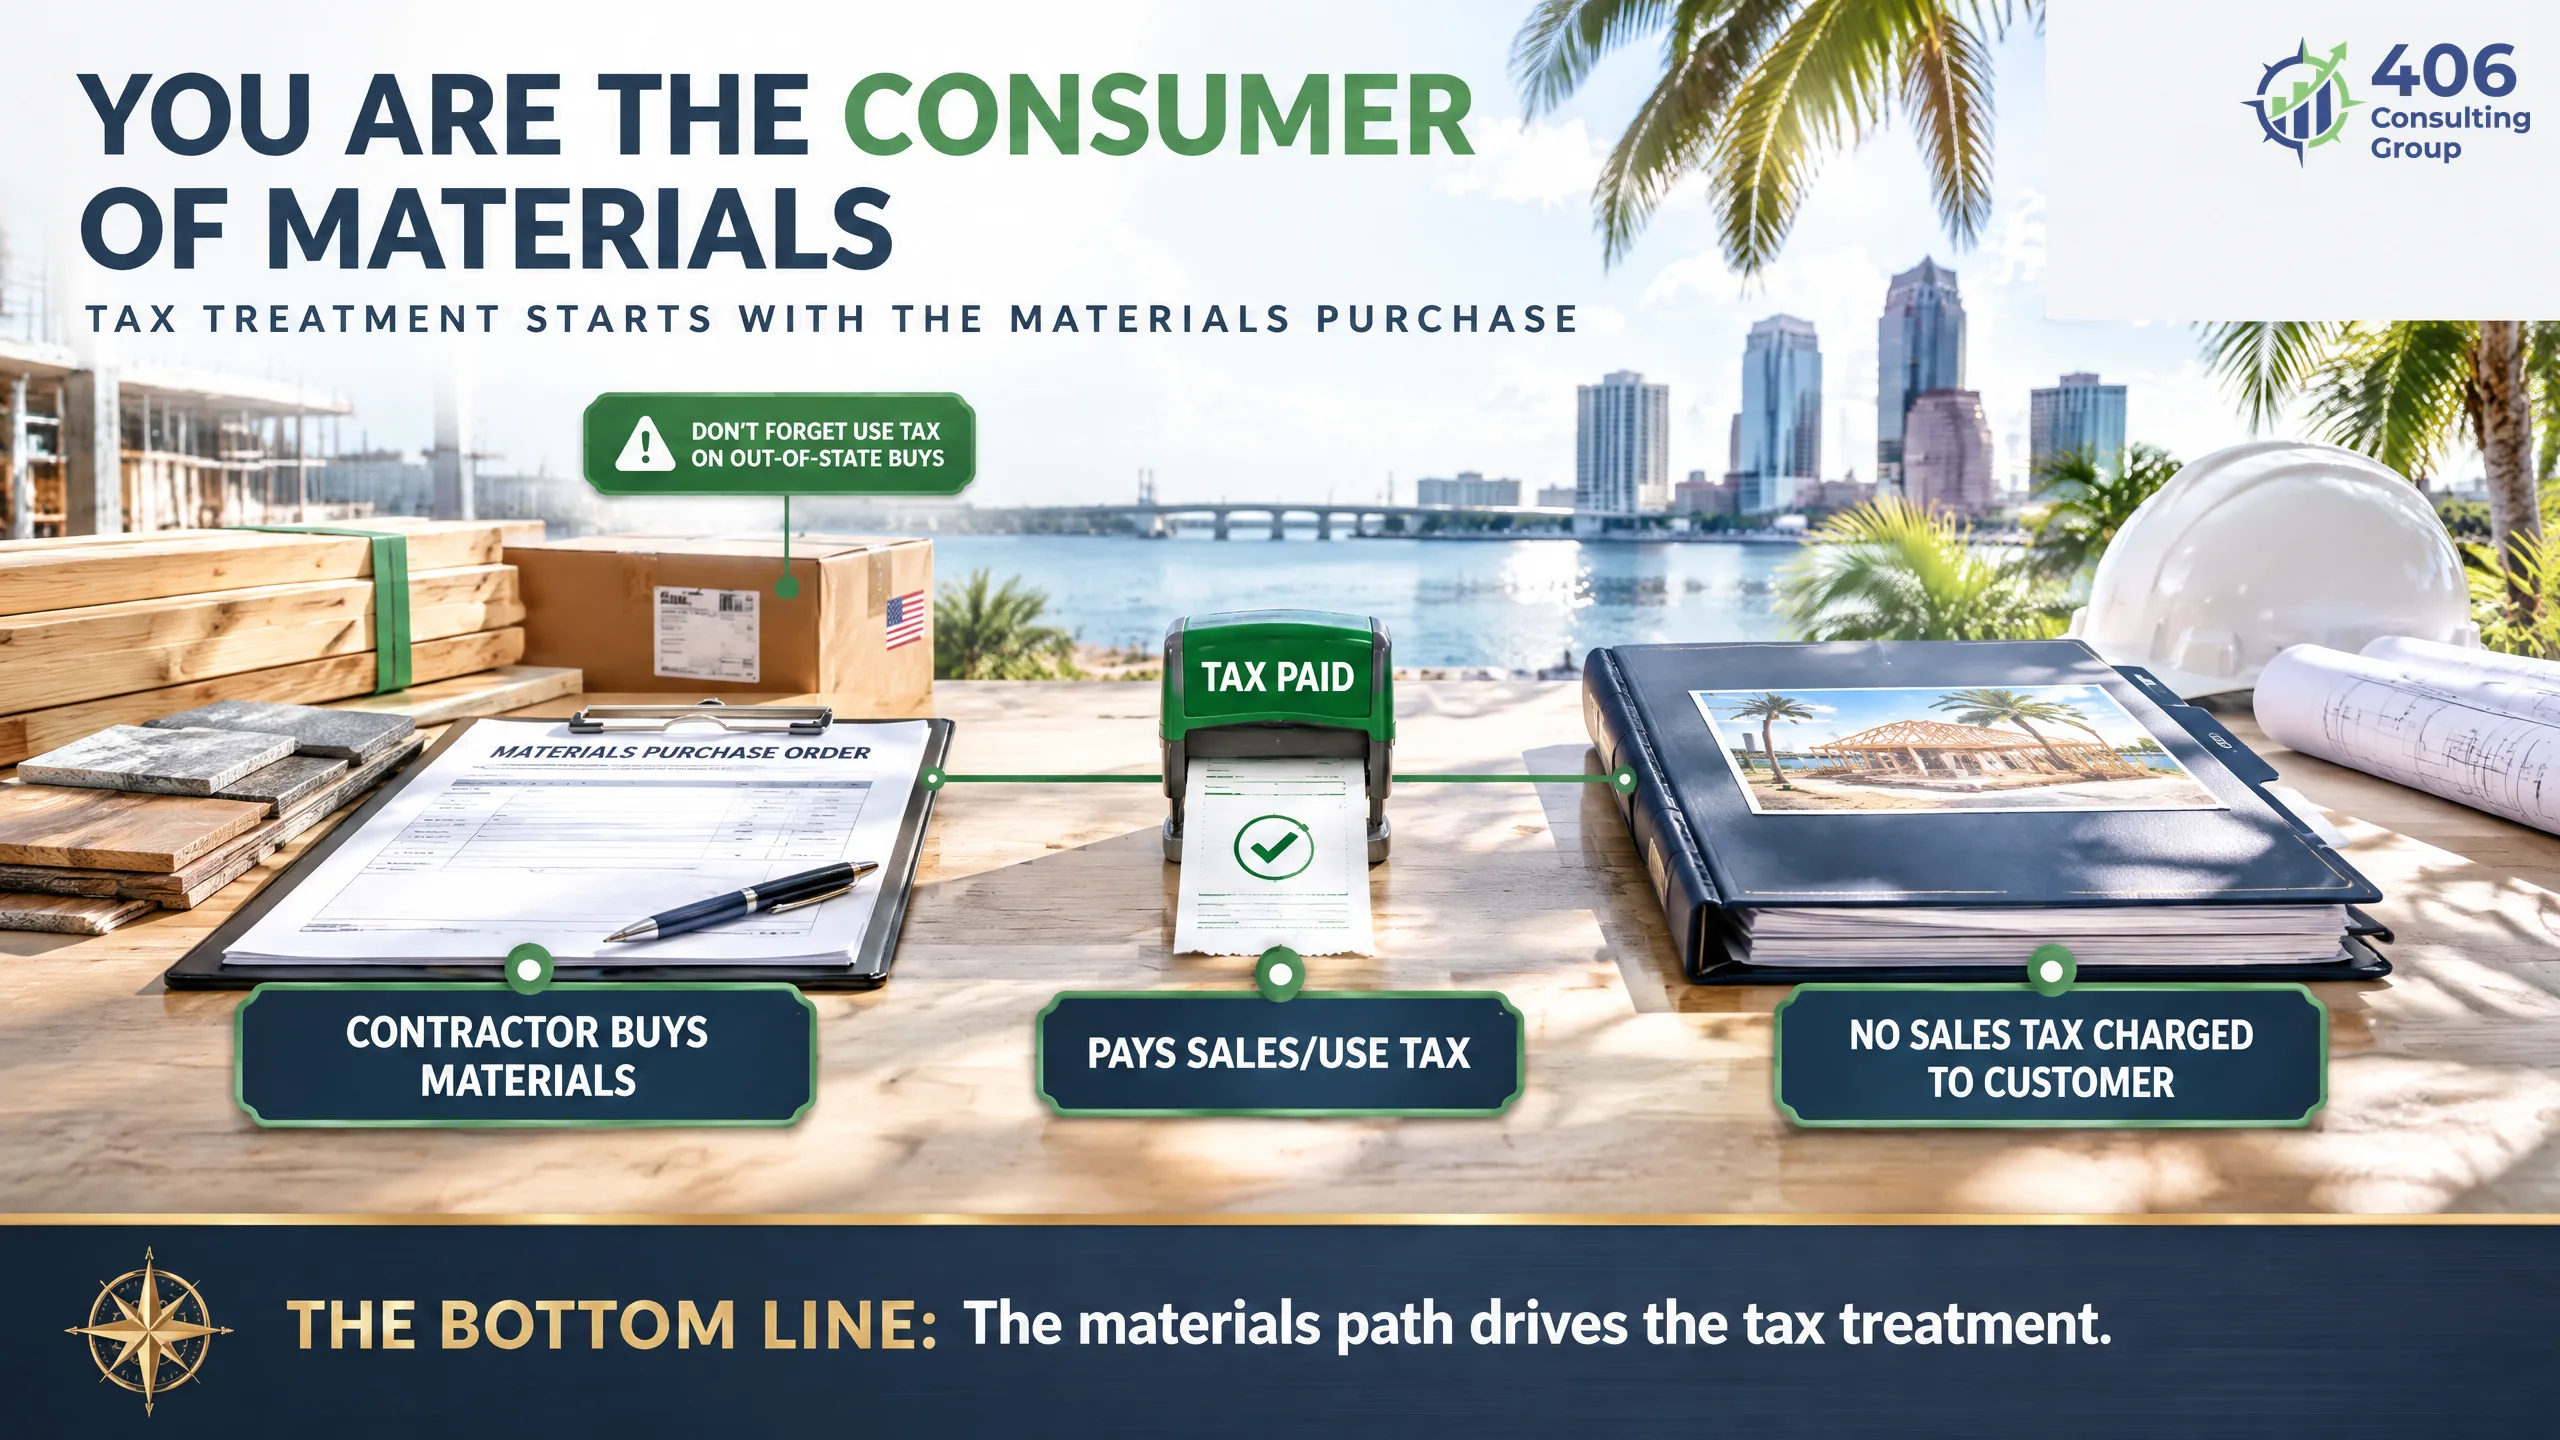
- →Contractors are generally the consumer of materials — you pay sales/use tax on materials, not the customer.
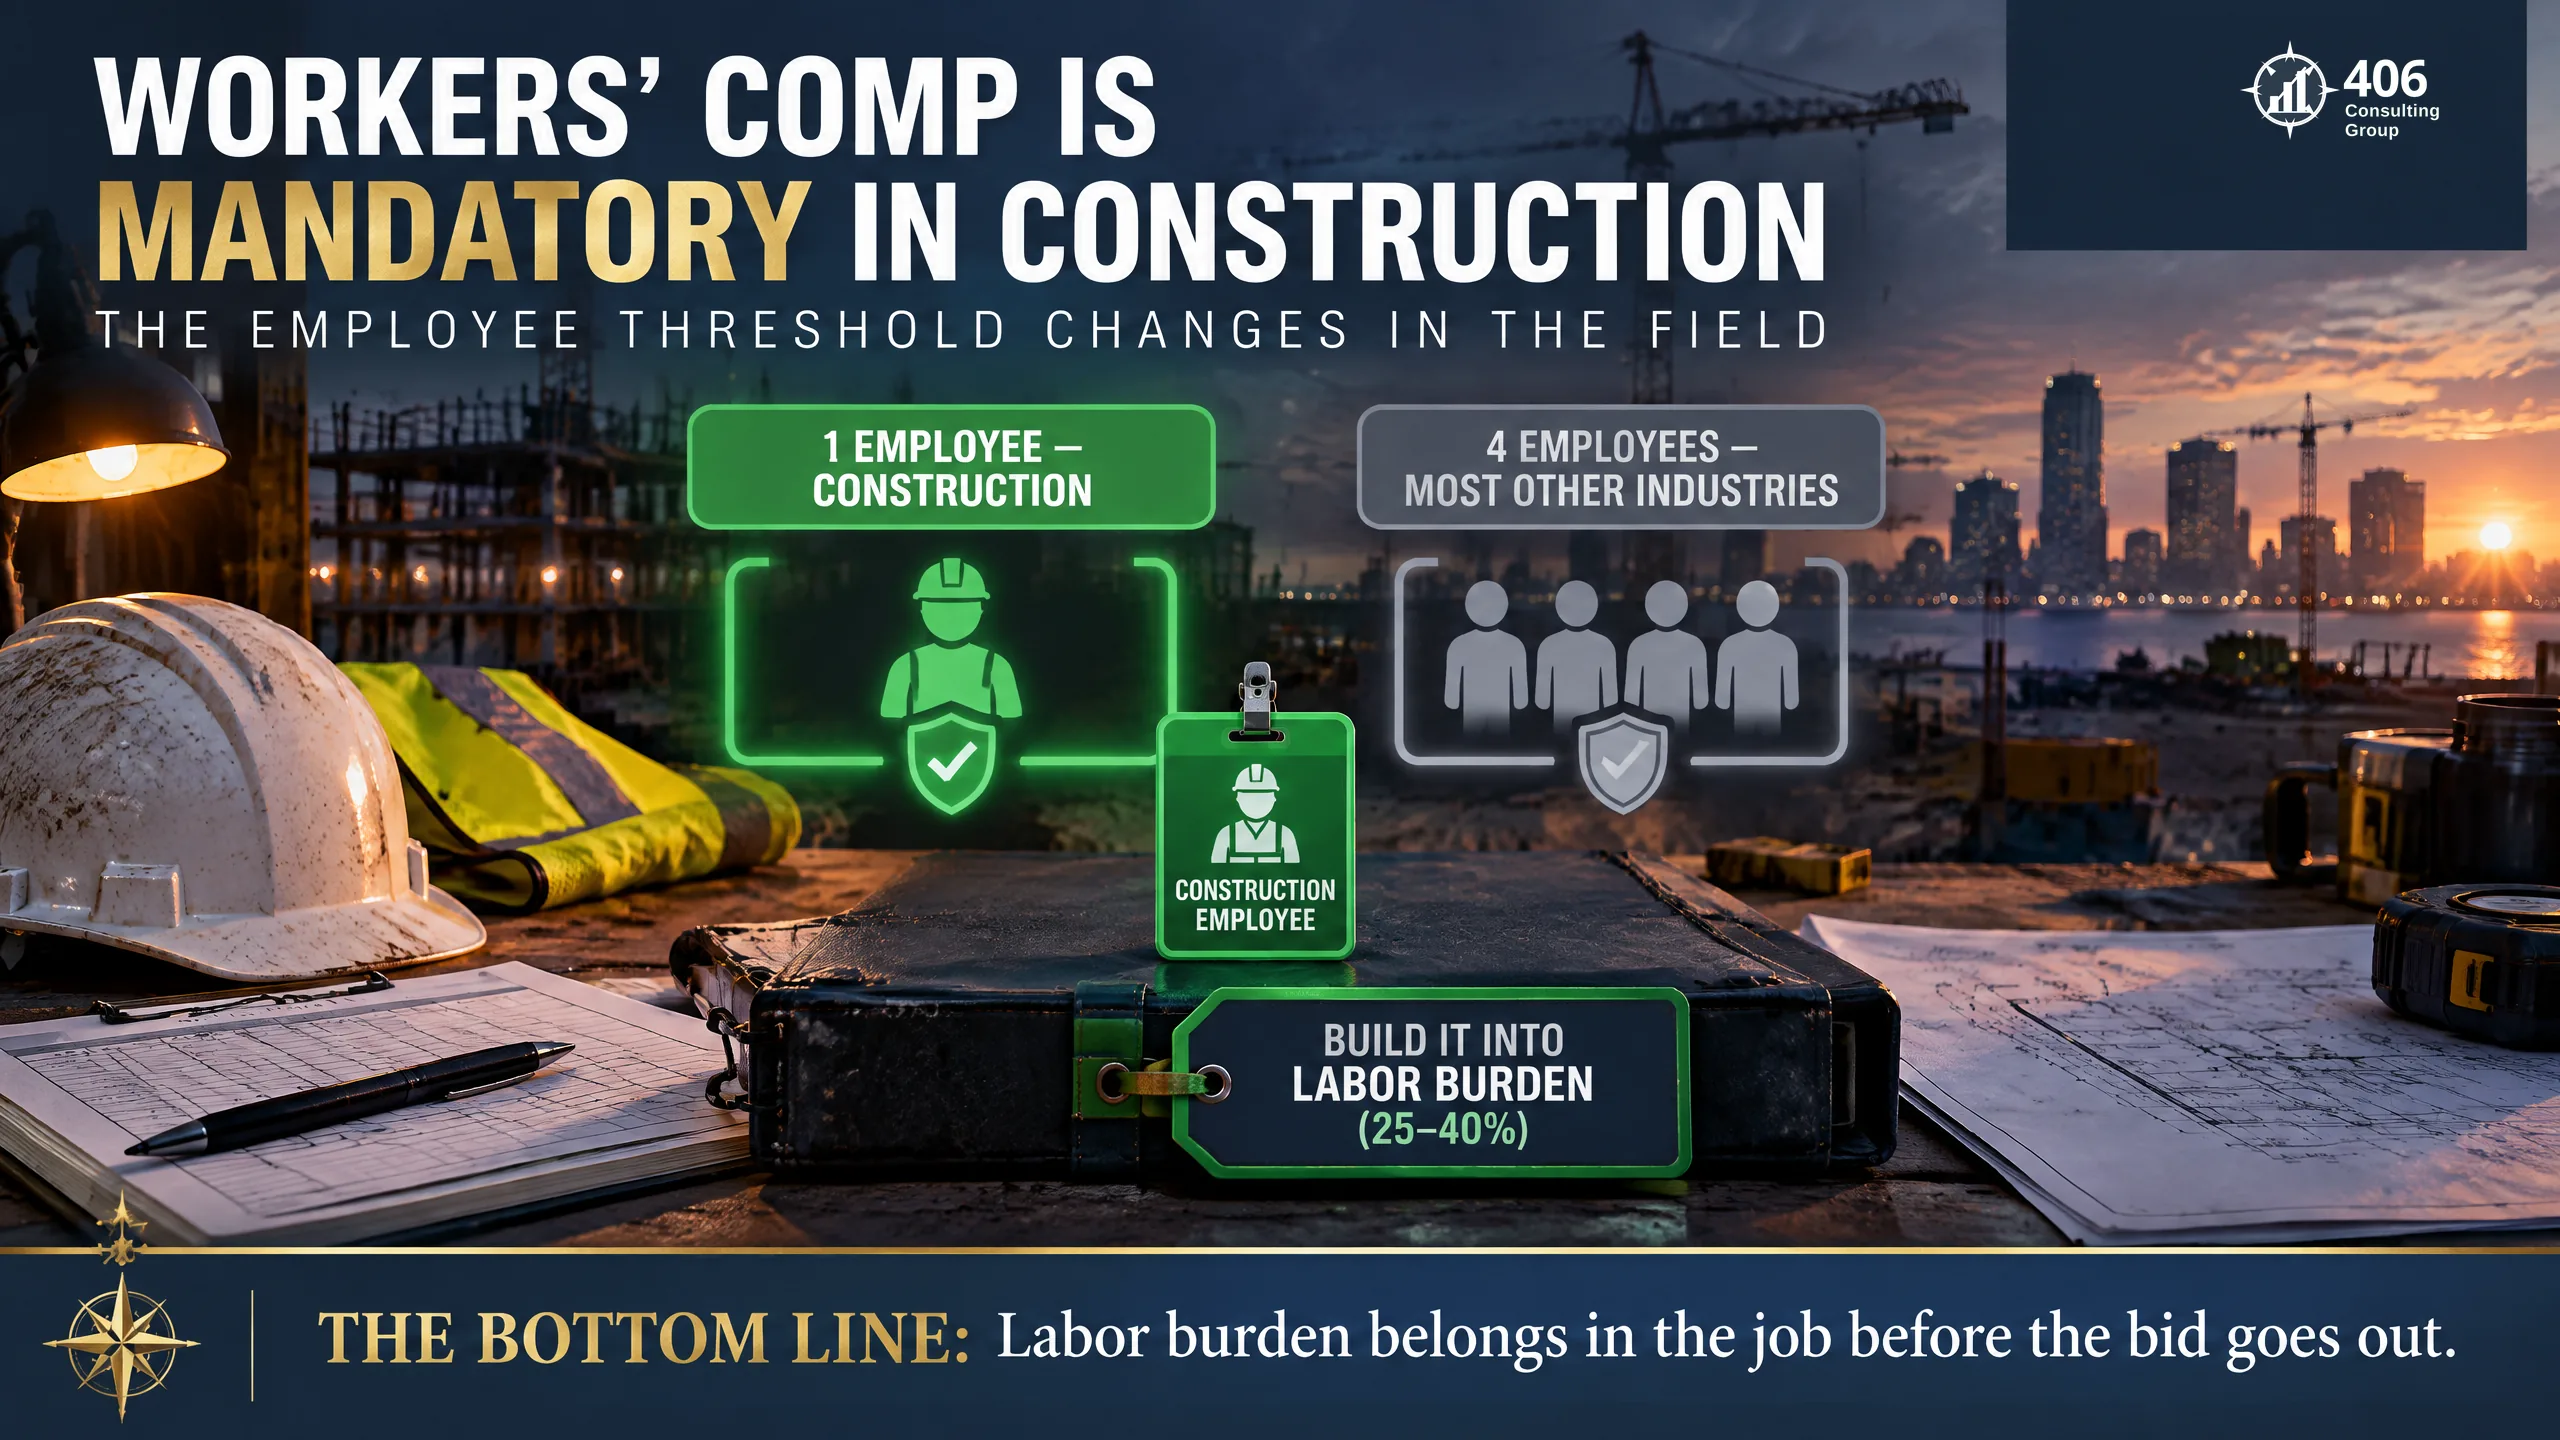
- →Workers' comp is mandatory in construction at just one employee — Florida's strictest-in-the-nation rule for the trades.
- →Insurance and storms shape Florida building costs — and it's all delivered remotely (about 80% of our local clients work that way).
Table of Contents
Building the Tampa Boom
A hot construction market hides a hard lesson every seasoned builder eventually learns: growth is where contractors most often go broke. More work means more materials bought before you're paid, more crews to make payroll for, and more jobs whose real profit you won't know until it's too late to fix. Volume feels like winning right up until the week the cash isn't there. The contractors who come through a boom stronger are the ones who could see, job by job, which work was actually making money — and who had the financials to keep bidding bigger.
In construction, revenue lies and cash tells the truth. A busy year with no job-level numbers is just a fast way to find out — too late — which jobs were bleeding you.
Seeing that clearly requires accounting built for how construction actually works.
Why Construction Accounting Is Different
Most businesses can run on a single company-wide profit-and-loss. Construction can't. Every project is its own little business, with its own budget, timeline, materials, labor, and margin — and your company's overall numbers can look fine while individual jobs quietly lose money. The core of construction accounting is job costing: tracking the true cost of each project — labor, materials, subs, equipment, and a fair slice of overhead — against what you bid, so you know real margin per job while there's still time to act on it.
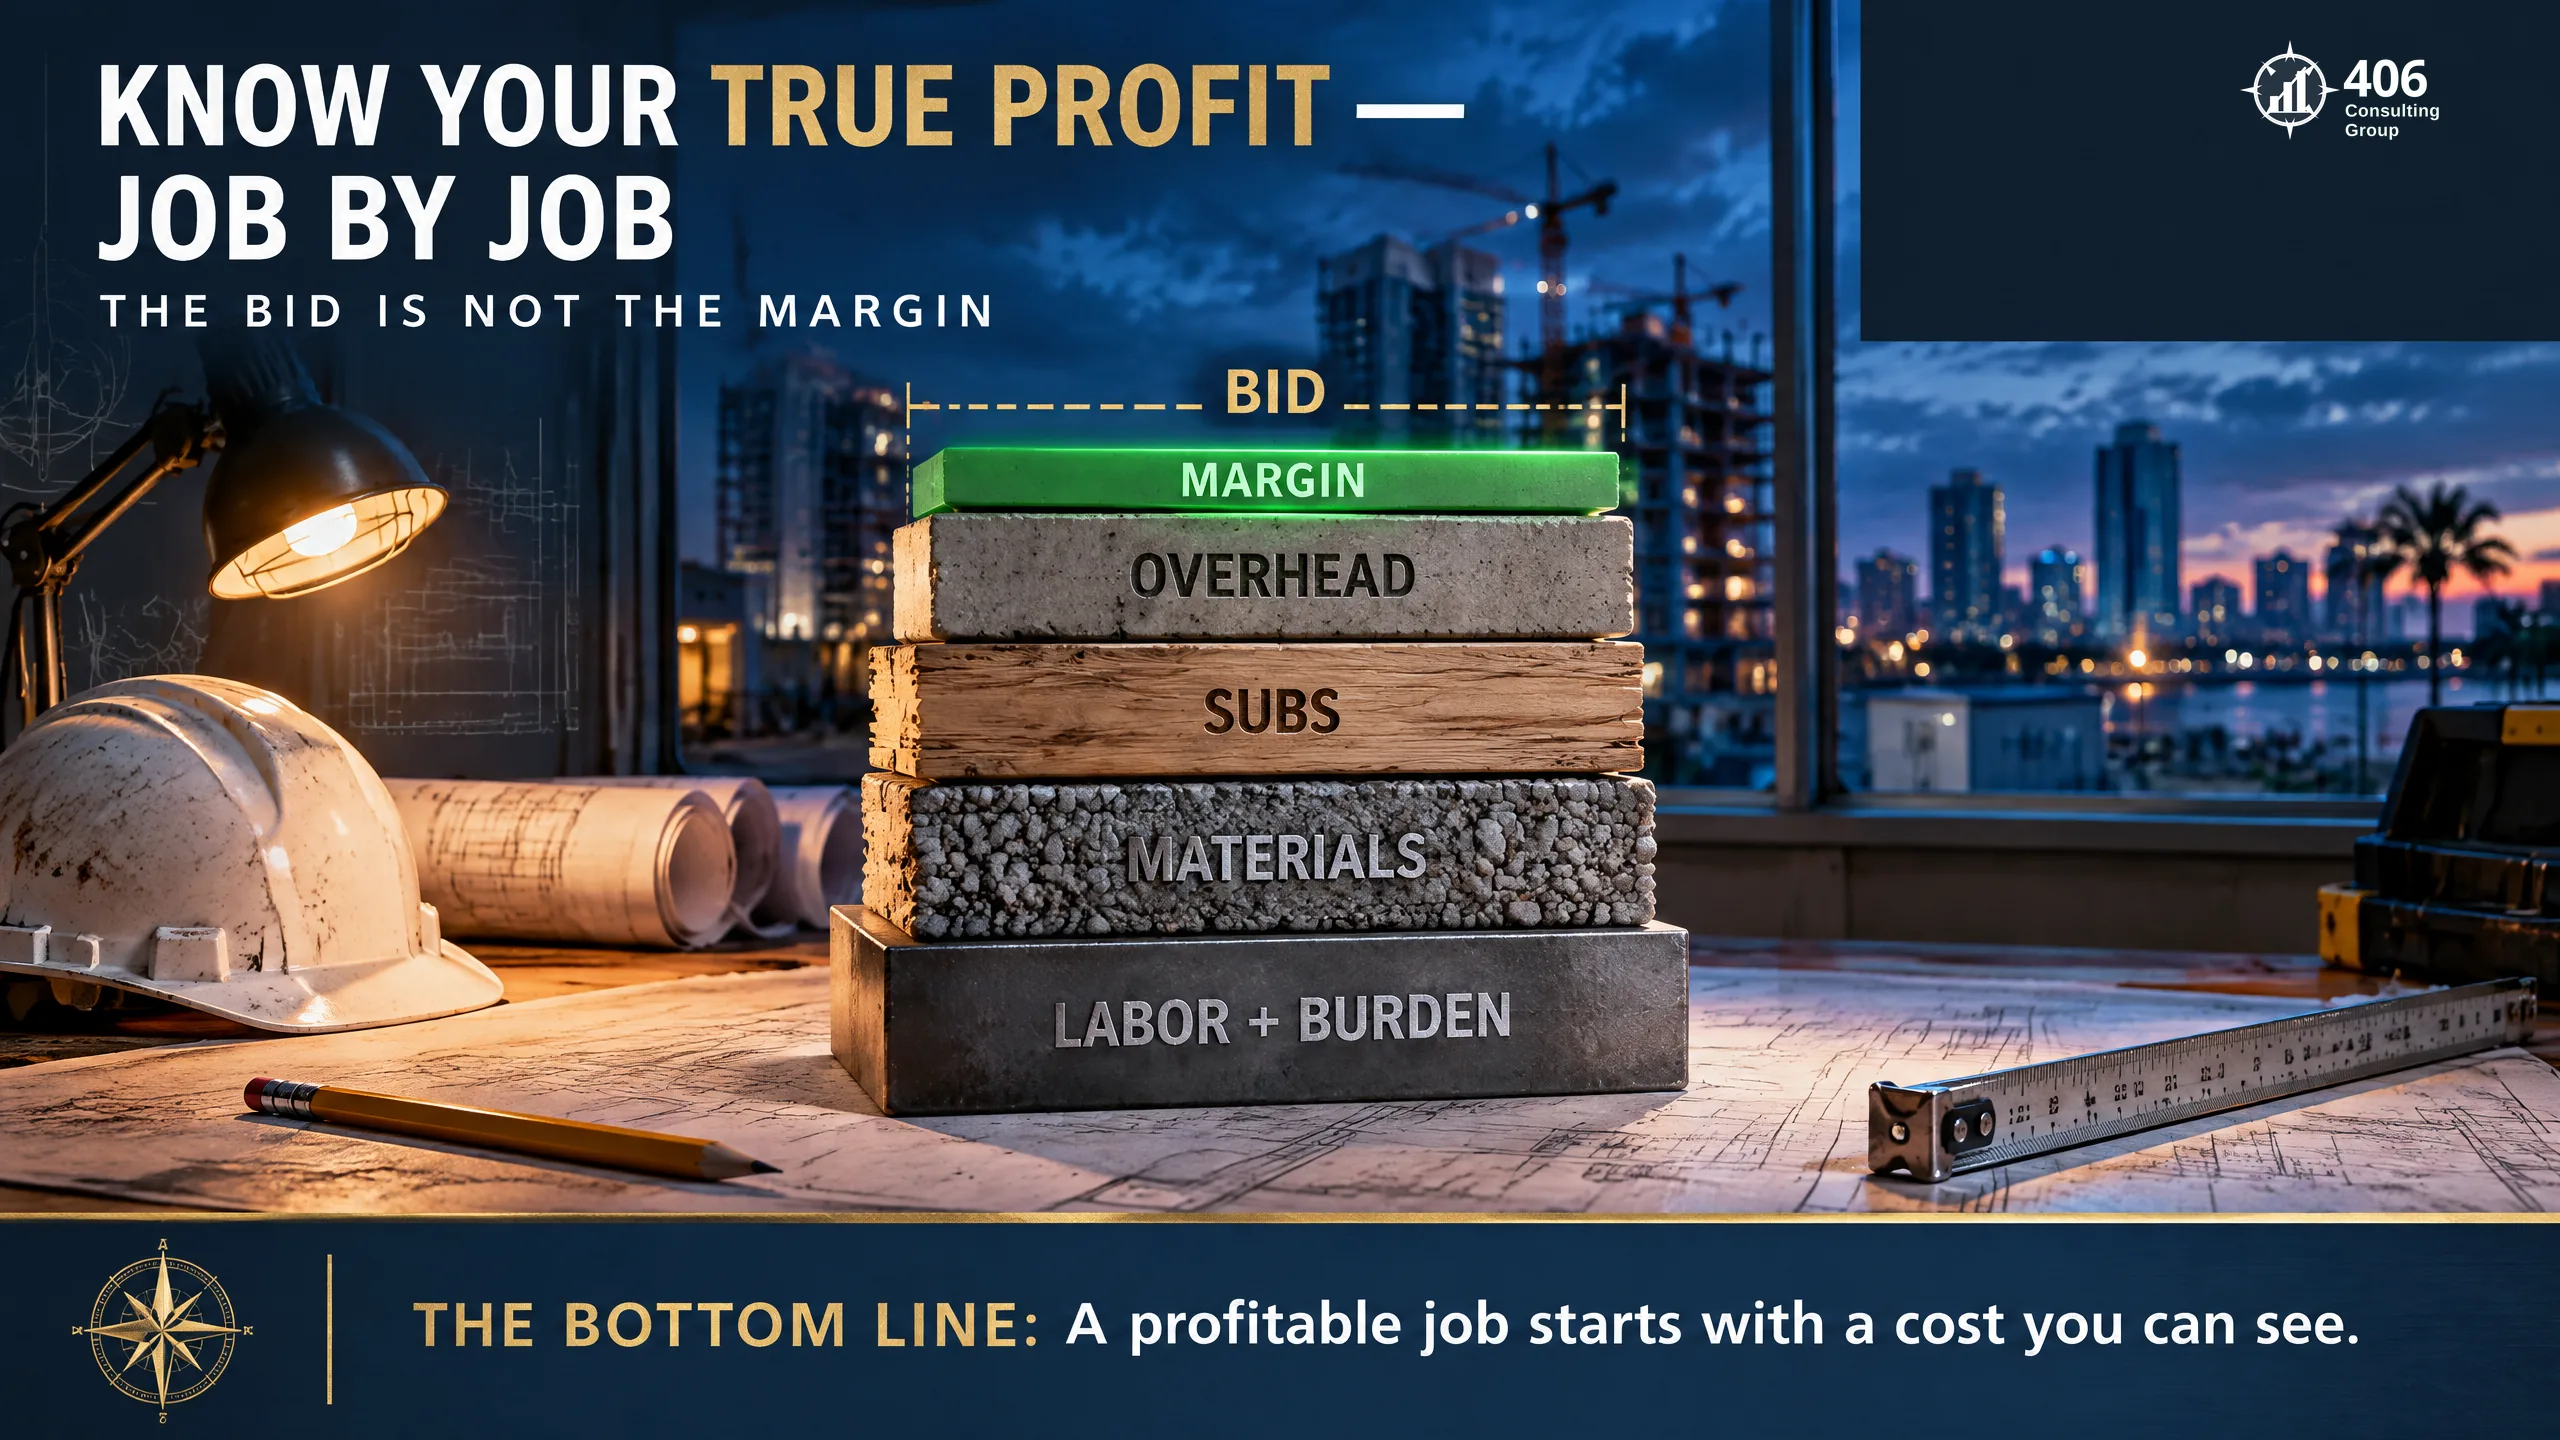
Get job costing right and everything else — bidding, licensing, bonding — gets easier. In Florida, that starts with the license.
In Florida, Your Financials Help License You
Florida licenses construction contractors through the state — the Department of Business and Professional Regulation (DBPR) and its Construction Industry Licensing Board — in two broad tracks: a Certified license (work statewide) and a Registered license (work in a specific local jurisdiction). Beyond the exam and experience, Florida asks for proof of financial responsibility— things like a credit review and, in cases, financial statements — along with insurance and often a bond. In plain terms, your books are part of your license application: weak or messy financials don't just cost you a loan, they can slow or shrink your ability to get and keep your license. Clean, credible statements are a growth tool, not just a compliance chore.
Florida ties your ability to build to your financial responsibility. The same clean books that win a loan help win — and keep — your contractor license.
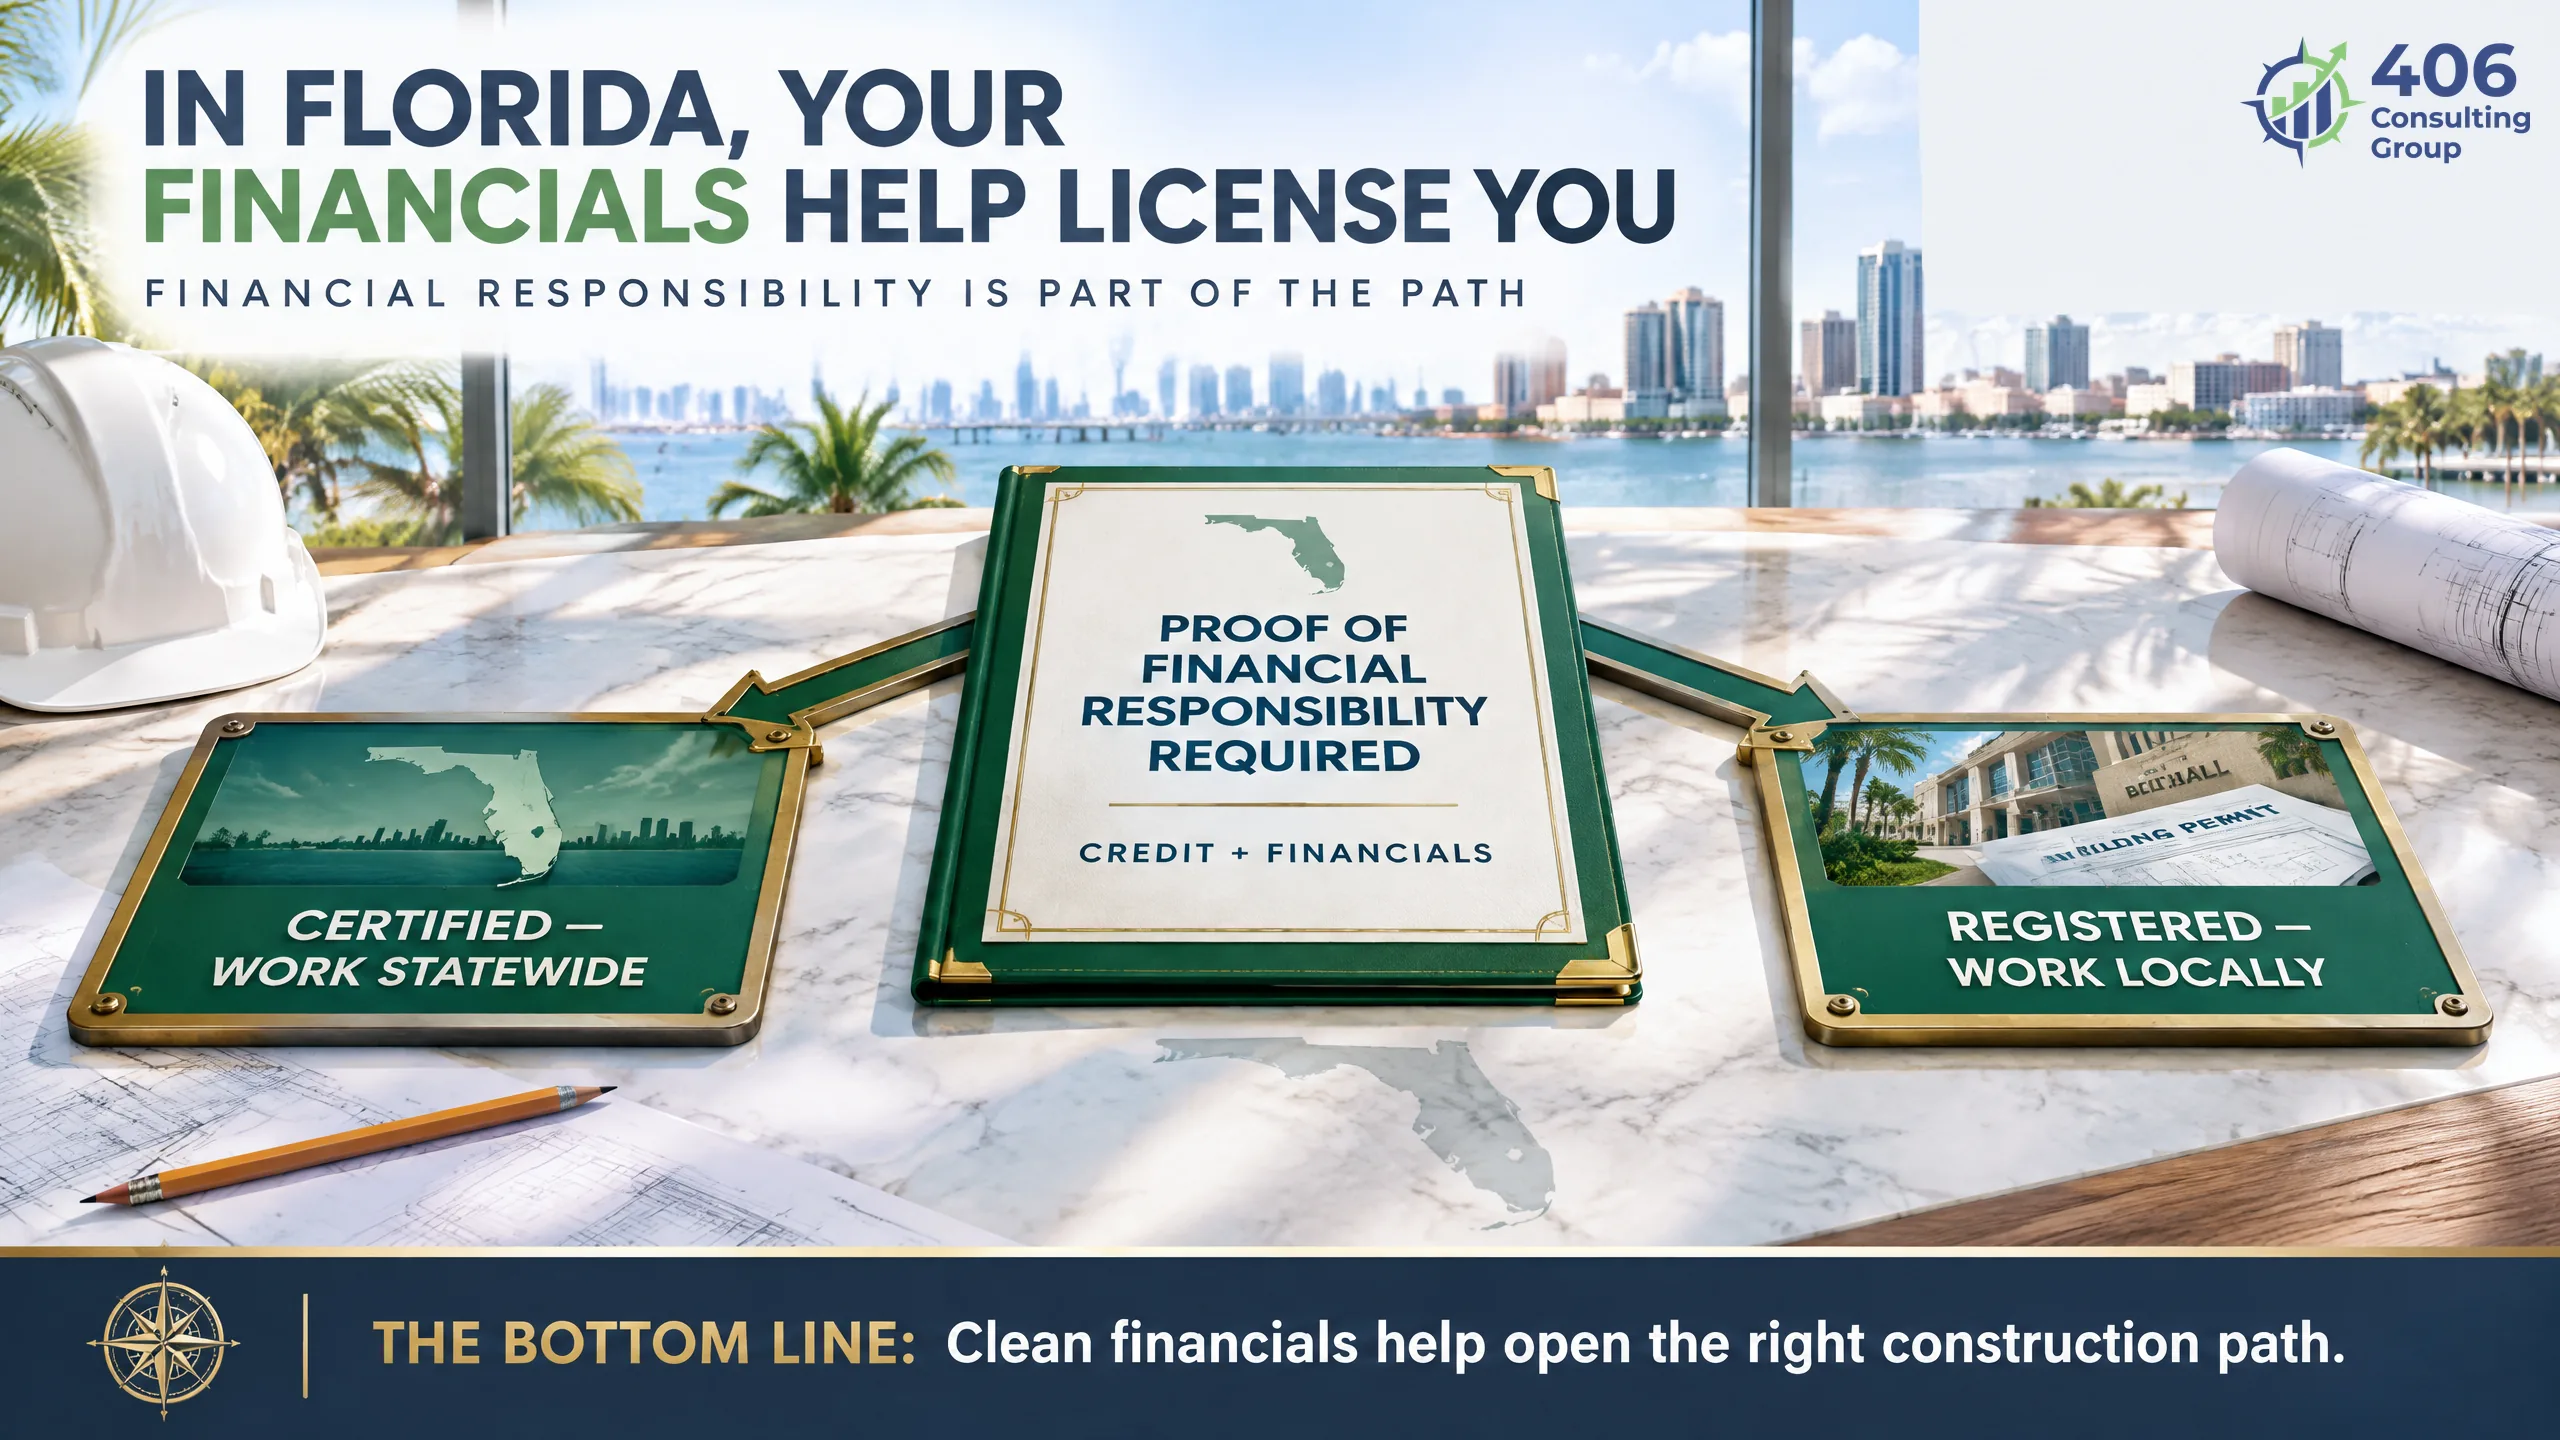
Always confirm current requirements with the DBPR. Making those financials credible depends on how you recognize revenue.
WIP and Percentage-of-Completion
On multi-month jobs, when you count the revenue matters as much as how much. The percentage-of-completion method recognizes revenue as a job progresses, and a work-in-progress (WIP) scheduleis the report that tracks it — showing whether each job is over- or under-billed relative to the work actually done. WIP is the single most important report in construction: it tells you if you've billed ahead of your costs (borrowing from the job's future) or fallen behind (financing the customer out of your own pocket). It's also the report the licensing board, bonding companies, and lenders all want to see — the same document strengthens your license file, your bond, and your line of credit.
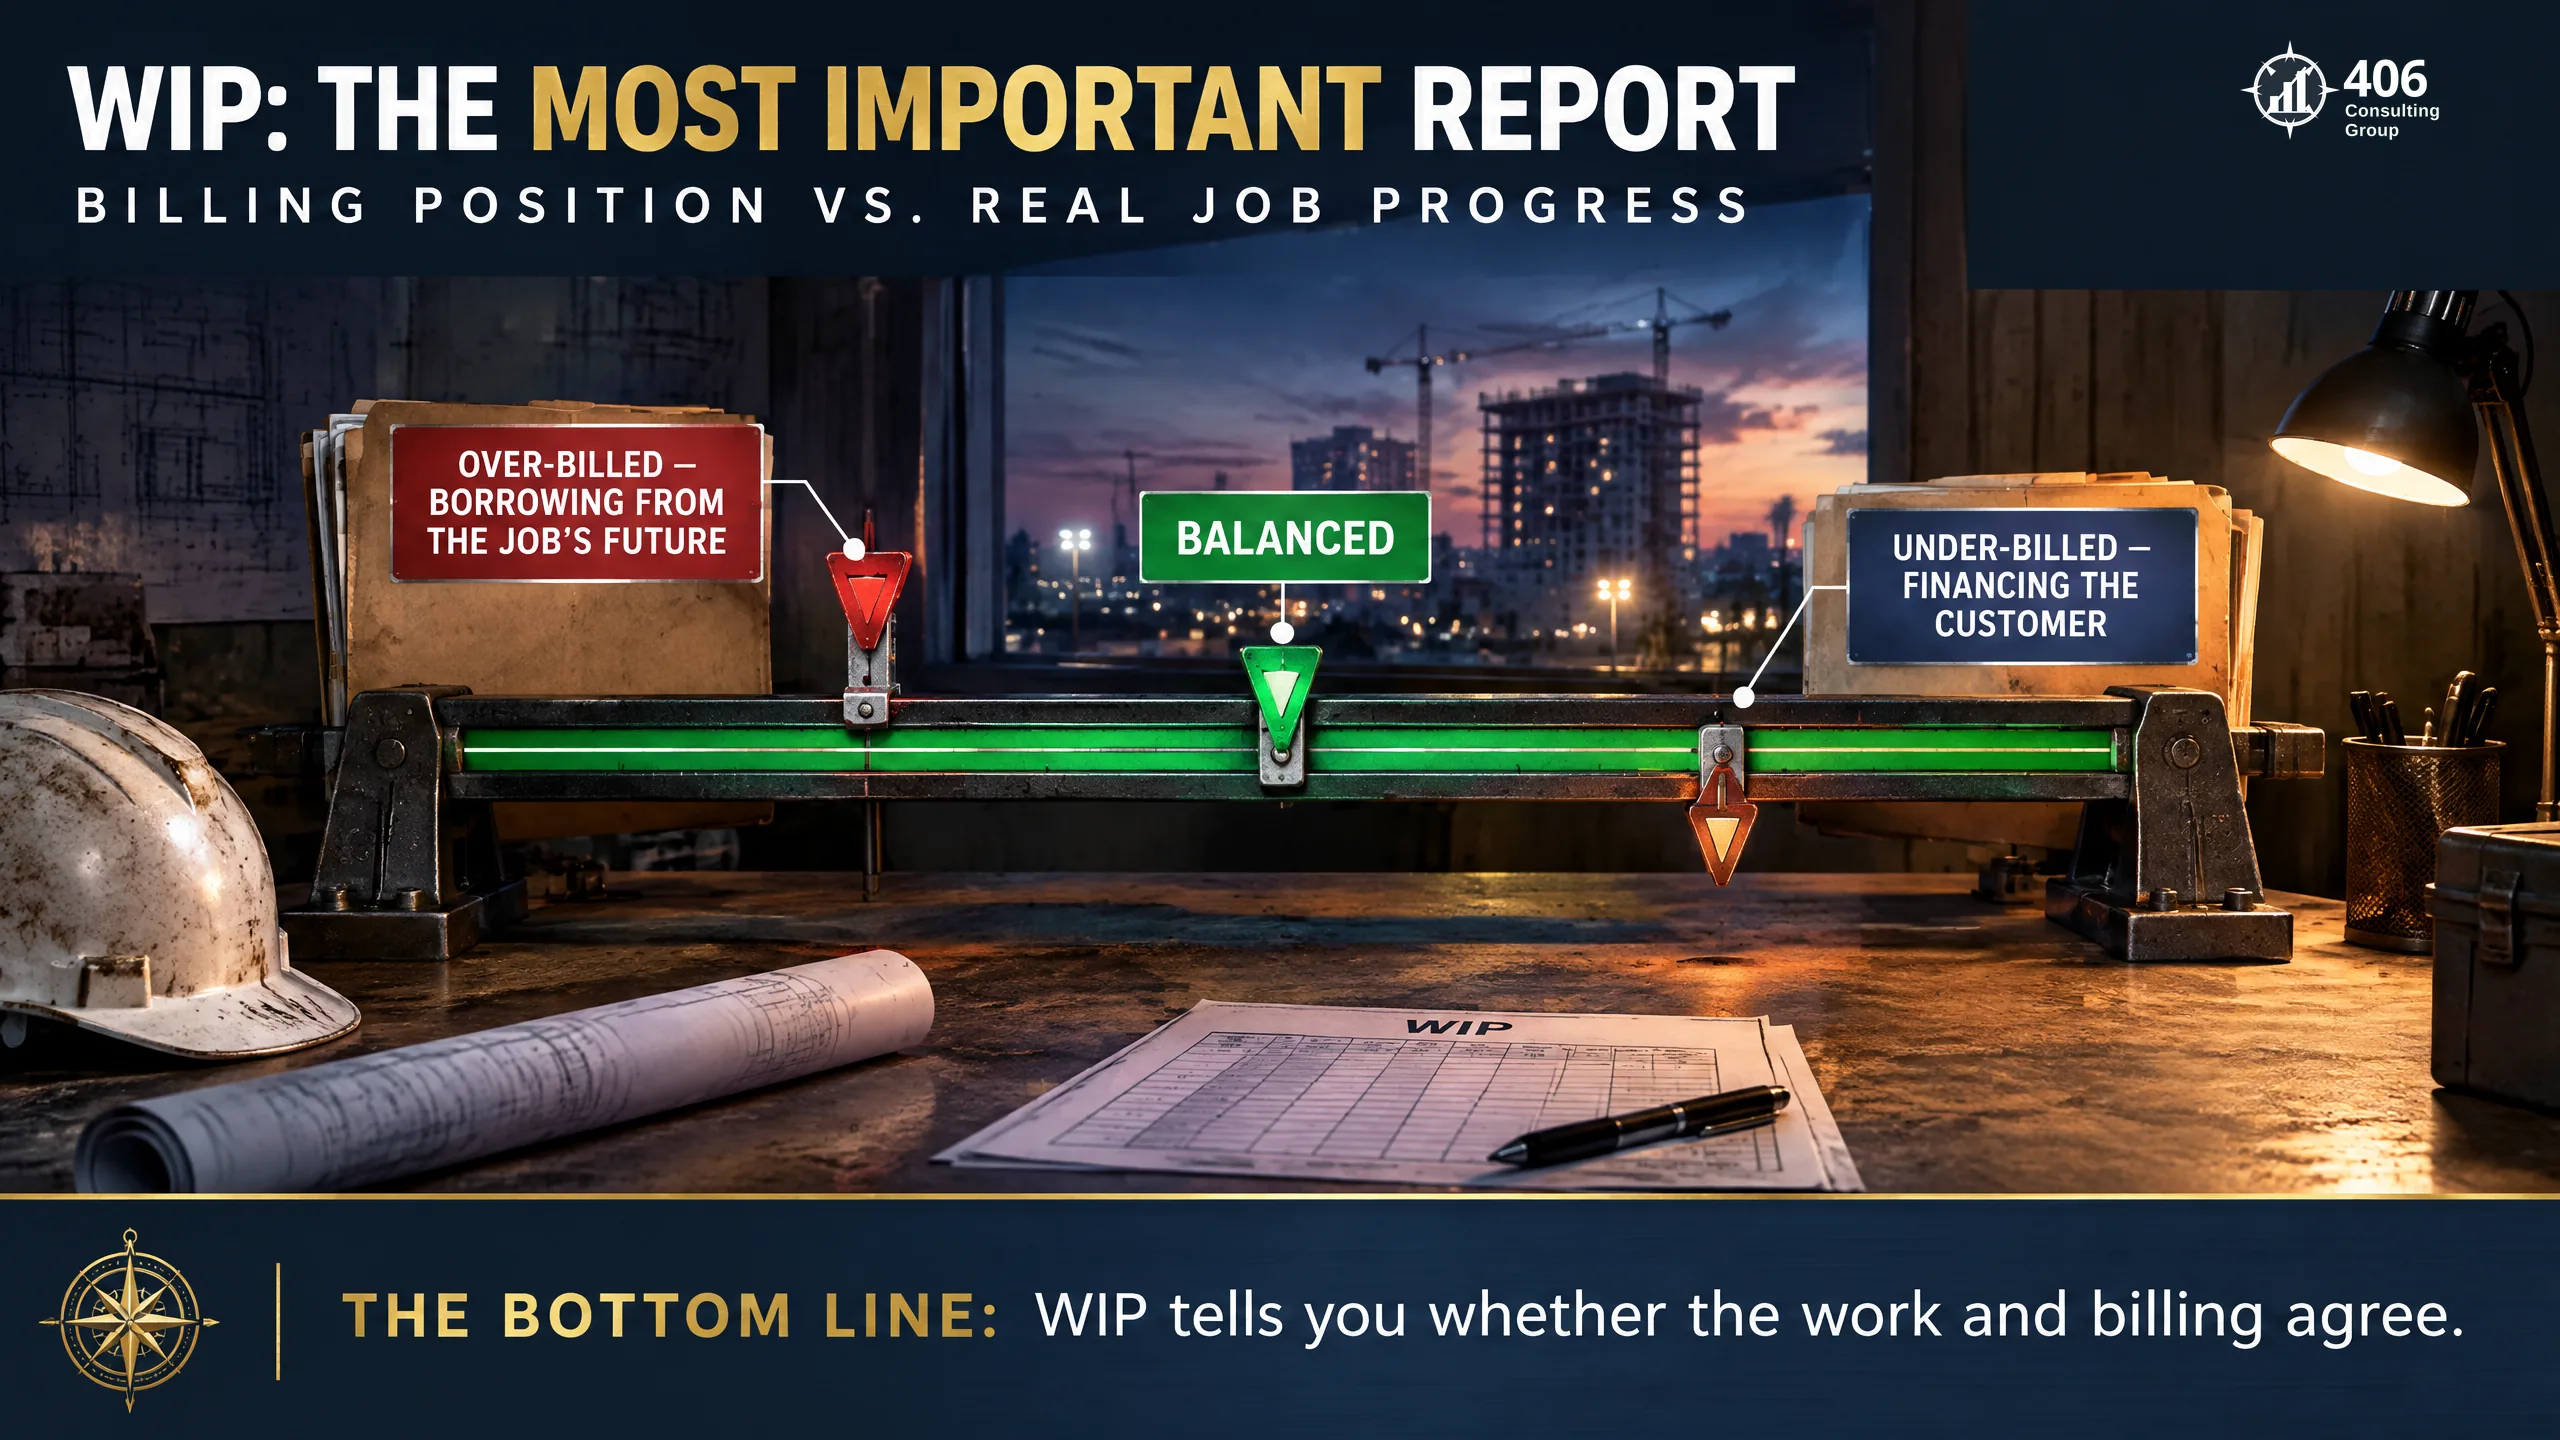
Accurate WIP depends on capturing every real cost — including a tax cost most contractors handle wrong.
FL Sales Tax: You Are the Consumer
For most contracts to improve real property, Florida generally treats the contractor as the consumer of the materials — meaning you pay sales or use tax when you buy the materials, and you don't charge your customer sales tax on the finished improvement. That sounds simple, and it trips people up in two ways: contractors forget to build the material tax into their bids as a real cost, and they owe use tax on materials bought out of state or online where no Florida tax was collected. Contracts structured as a retail sale of items plus installation can be treated differently, so how a given job is written affects what you owe. Confirm your specific contracts with the Florida Department of Revenue.
The other cost Florida contractors can't treat as optional is workers' comp.
Workers' Comp Is Mandatory in Construction
Florida draws a hard line for the trades: while most industries don't need workers' compensation until they have four employees, construction businesses generally must carry it at just one employee — and working owners and officers are counted unless they file for a valid exemption. It's one of the strictest construction WC rules in the country, and the premiums are significant. That makes it a major cost that has to be captured against every job as part of labor burden: a field employee's real cost is the wage plus payroll taxes, workers' comp, insurance, and benefits — often 25% to 40% more than the base rate. Contractors who bid off the raw hourly wage lose money on labor and never understand why.
Confirm exemption rules with the state. And workers' comp is only one piece of Florida's biggest cost story.
Insurance, Storms & the Cost of Building
Building in Florida means building in the toughest insurance market in the country. General liability, builder's risk, and property coverage all run high and move fast, and for a contractor those premiums are a real, volatile line item — not an afterthought. Hurricane season adds its own rhythm: material and labor costs can spike after a storm, permitting and inspection timelines shift, and demand surges and stalls. A contractor who isn't tracking insurance as a true cost and planning cash around the season is exposed twice — on margin and on liquidity. Good construction accounting builds both into the numbers so a storm is a plan, not a panic.
Between licensing, material tax, workers' comp, and insurance, the thread tying it together is cash — and construction has a built-in cash trap.
Retainage and the Cash-Flow Trap
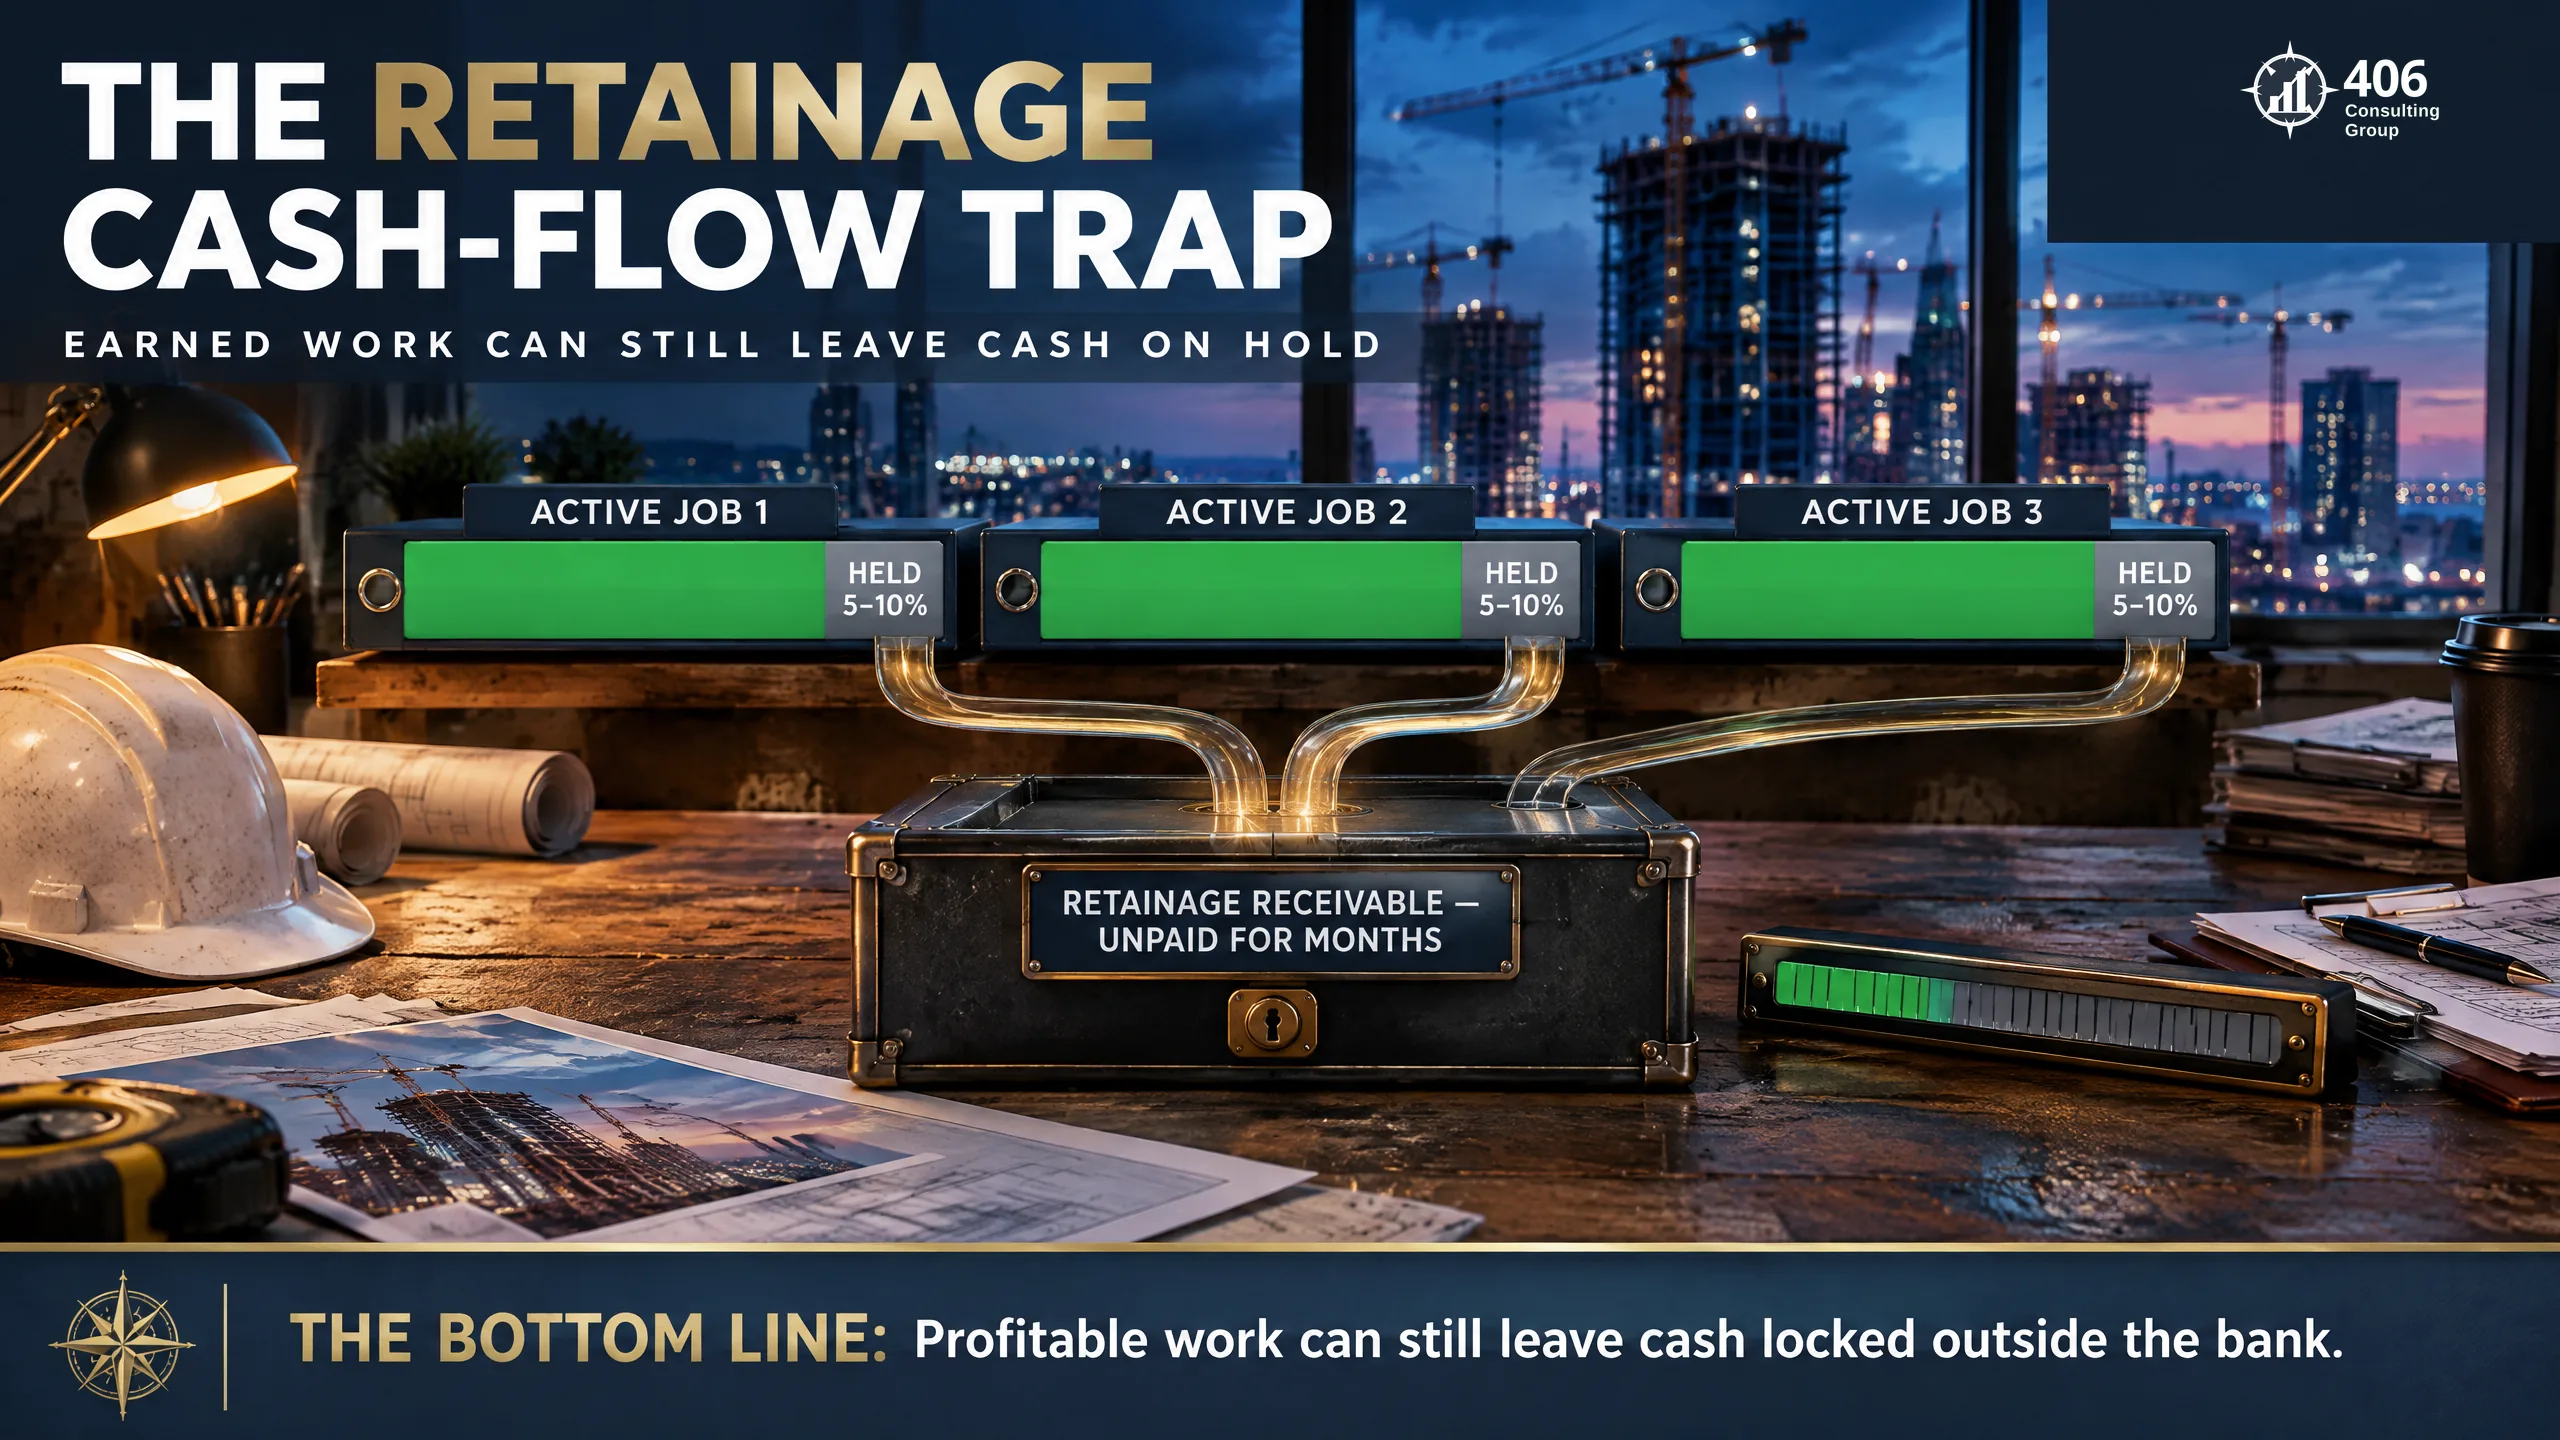
Retainage— the portion of each payment (often 5% to 10%) the customer holds back until the job is complete — is where profitable contractors run dry. You've paid for the labor and materials, but a slice of what you're owed sits unpaid for months, sometimes long after the work is done. Multiply that across several active jobs and a busy, profitable contractor can be genuinely short of cash. Managing it means tracking retainage receivable as the real asset it is, forecasting when it releases, and financing the gap on purpose rather than discovering it on payroll Friday. This is exactly the kind of construction-specific cash reality that generic accounting misses.
Handle cash and job costing well, and you unlock the two things that let a Tampa contractor scale: bonding and capital.
Bonding and Capital for Bigger Jobs
Bigger and public projects require surety bonds, and a surety underwrites your bonding capacity almost entirely on your financial statements — your WIP schedule, working capital, and profit history. Weak books mean a small bonding line and small jobs; strong, credible books mean the capacity to bid the work that actually grows a company. In Tampa, that stacks on top of the licensing financial-responsibility requirement and the metro's deep pool of capital: the same clean financials satisfy your license, expand your bond, and open the line of credit that funds materials and retainage. Because our background is commercial banking and underwriting, we prepare contractor financials the way sureties and lenders actually read them — so your numbers open doors instead of closing them.
All of it — job costing, WIP, licensing, bonding — can be built and run without anyone setting foot on your site.
Getting Started — Remotely
Construction accounting is done from the numbers, not the jobsite — job-cost data, payroll, and WIP live in the cloud, and reviews happen over screen-share and calls. It's why around 80% of our own local clients run the entire relationship remotelyand never come into the office. What a Tampa contractor needs is an accountant who genuinely understands construction — job costing, WIP, Florida's licensing and tax rules, mandatory workers' comp, insurance, retainage, and bonding — not one who happens to have a local office. We build these systems from a whole-company view, tying the field, the office, and the financials together, and we serve contractors across Tampa and Florida remotely.
Build books that let you bid bigger.
Let's get your job costing, WIP, and financials to where they satisfy your license, grow your bond, and fund your growth — remotely, for Tampa and Florida contractors, the way most of our clients already work.
For the rest of the Tampa picture, see our Tampa accounting overview and the CFO & controller guide.
FAQ: Tampa Construction Accounting
Do I need a contractor's license in Florida, and how does my accounting affect it?
Yes — Florida licenses construction contractors through the state (the DBPR and its Construction Industry Licensing Board), in two broad tracks: a Certified license to work statewide and a Registered license to work in a specific local jurisdiction. Beyond an exam and experience, Florida requires proof of financial responsibility — such as a credit review and, in cases, financial statements — plus insurance and often a bond. That means your books are effectively part of your license application: clean, credible financials help you qualify and keep your license, while messy ones can slow or shrink it. Always confirm current requirements with the DBPR.
Is workers' compensation required for Florida contractors?
Yes, and the construction rule is unusually strict. Most Florida industries don't need workers' compensation until they have four employees, but construction businesses generally must carry it at just one employee, and working owners and officers are counted unless they obtain a valid exemption. Premiums in construction are significant, which makes workers' comp a major cost that has to be built into your labor burden and captured against each job. It's one of the strictest construction workers'-comp rules in the country, so confirm your obligations and any exemption options with the state.
How does sales tax work on Florida construction contracts?
For most contracts to improve real property, Florida treats the contractor as the consumer of the materials — you pay sales or use tax when you buy materials, and you don't charge your customer sales tax on the finished improvement. Two things trip contractors up: forgetting to build that material tax into bids as a real cost, and owing use tax on materials bought out of state or online where no Florida tax was collected. Contracts structured as a retail sale of items plus installation can be treated differently, so how a job is written affects what you owe. Confirm your specific contracts with the Florida Department of Revenue.
What is a WIP schedule and why does it matter so much in construction?
A work-in-progress (WIP) schedule tracks each active job's costs and billings against the work actually completed, using the percentage-of-completion method. It tells you whether you've over-billed (collected ahead of your costs, borrowing from the job's future) or under-billed (financing the customer out of your own pocket). It's the most important report in construction because it reveals both true job profitability and hidden cash risk — and it's the exact document the licensing board, surety bonding companies, and lenders all want to see. One accurate WIP schedule strengthens your license file, your bond, and your line of credit.
Can 406 Consulting Group handle construction accounting remotely for a Tampa contractor?
Yes. Construction accounting is done from the numbers — job-cost data, payroll, and WIP schedules that live in the cloud — with reviews over screen-share and calls, so it works the same whether we're across town or across the country. In fact, around 80% of our own local clients run the whole relationship remotely and never come into the office. What matters is genuine construction expertise: job costing, WIP, Florida's licensing and tax rules, mandatory workers' comp, insurance, retainage, and bonding. With our commercial-banking background, we also prepare your financials the way sureties and lenders read them. We serve Tampa and Florida contractors entirely remotely.
FL Contractor Facts
Tampa construction at a glance
Tampa Construction
Job costing to bonding, remote.
About the Author
Jason Anderson
Co-Founder, 406 Consulting Group
Jason pairs big-firm accounting training with hands-on trades and oilfield experience, building job-costing, WIP, and license- and bond-ready financials that let contractors bid bigger — designed from a whole-company view and delivered remotely.
Read the Full Story