
Bookkeeping Services in Miami, FL:
Built for Money That Crosses Borders
Multi-currency, foreign-owned entities, short-term rentals, and a hospitality scene that never sleeps — Miami bookkeeping carries weight generic bookkeeping never touches. The Miami Books Baseline: the six things your books must do before tax season or a lender call, delivered remotely the way 80% of our local clients already work.
Miami runs on money that moves across borders. A Brickell import business invoices in euros, a Coral Gables holding company is owned by a family in Bogotá, a Wynwood restaurant group opens its fourth location while its books sit ten months behind, and a South Beach condo owner splits nights between Airbnb, a broker, and a long-term tenant. Bookkeeping services in Miamihave to carry weight that generic bookkeeping never touches: foreign currency, foreign ownership, per-property real estate, and a hospitality scene that never sleeps. Florida keeps the state side friendly — no personal income tax — but the records still have to survive tax season, a lender's underwriting, and, for a growing share of Miami owners, an IRS related-party filing where the penalty for bad records starts at $25,000.
This guide lays out what Miami bookkeeping actually has to do, introduces a simple framework — The Miami Books Baseline— and walks the situations that trip up owners here: multi-currency entries, the foreign-owned entity record trail, short-term rentals, restaurant tips and POS tender, county sales tax, and cleaning up books that fell behind during a growth sprint. All of it delivered remotely.
By Jason Anderson — Co-Founder, 406 Consulting Group. Big-firm-trained accountant and Six Sigma systems builder who designs clean, audit-ready, lender-ready books from a whole-company view — delivered remotely to Miami and Florida businesses.
Quick Answer: What Bookkeeping in Miami Must Cover
- →Multi-currency transactions recorded in USD functional currency with FX gains/losses tracked and source-currency detail kept.
- →Foreign-owned entity books that keep a clean related-party trail for Form 5472 — where a records failure can mean a $25,000 penalty.
- →Per-property real estate and short-term rental books — each unit and platform payout tracked separately.
- →Hospitality detail — tips, POS tender types, and seasonal labor — plus ~7% Miami-Dade sales and use tax tracked correctly.
- →It's all remote — about 80% of our own local clients run the entire relationship that way.
Table of Contents
What Miami Bookkeeping Must Cover That Generic Bookkeeping Doesn't
Bookkeeping services in Miami have to handle four things a generic bookkeeper rarely sees together: money in multiple currencies, ownership from outside the United States, real estate income split across platforms and units, and a hospitality economy built on tips and seasonal swings. National bookkeeping advice assumes a single-currency, US-owned service business in a state with income-tax withholding. Miami is almost none of that. The books here are a compliance document for the IRS, a currency ledger, a per-property P&L, and a lender's underwriting file — often all at once.
In most cities the books just record what happened. In Miami they also have to prove where money came from, in what currency, from which owner, on which property — and do it cleanly enough for the IRS and a lender to trust.
Florida's state side is genuinely light — no personal or pass-through income tax, and only C-corporations pay the 5.5% corporate income tax. But "light state tax" and "simple books" are not the same sentence. The complexity in Miami lives in how the money moves, not in a state income-tax return. That is exactly what the Miami Books Baseline is built to cover.
The Miami Books Baseline
The Miami Books Baseline is our name for the six things your books must do before you file a tax return or take a lender call. It is a floor, not a ceiling — the minimum standard a Miami business should clear before anyone else reads the numbers. Miss one of them and the return gets shaky, the loan slows down, or an IRS filing sits on a record trail that isn't there.
1. Reconciled to the bank
Every bank and credit-card account reconciled monthly, in USD, so the numbers actually tie to reality — including foreign-currency accounts converted at proper rates.
2. Currency-clean
Multi-currency transactions recorded in USD functional currency, with FX gains/losses tracked and the original source-currency amount preserved.
3. Related-party trail
For foreign-owned entities, every transaction with the owner or a related company documented and categorized to support a Form 5472 record trail.
4. Segmented by property/unit/location
Real estate tracked per property, rentals per unit, restaurants per location — so profit is visible where it's earned, not blended into one number.
5. Sales & use tax captured
Miami-Dade sales tax (~7%) collected and remitted where it applies, and use tax accrued on untaxed out-of-state and cross-border purchases.
6. Close on a cadence
A real monthly close that produces statements you can hand to a lender, a tax preparer, or an IRS filing without a scramble.
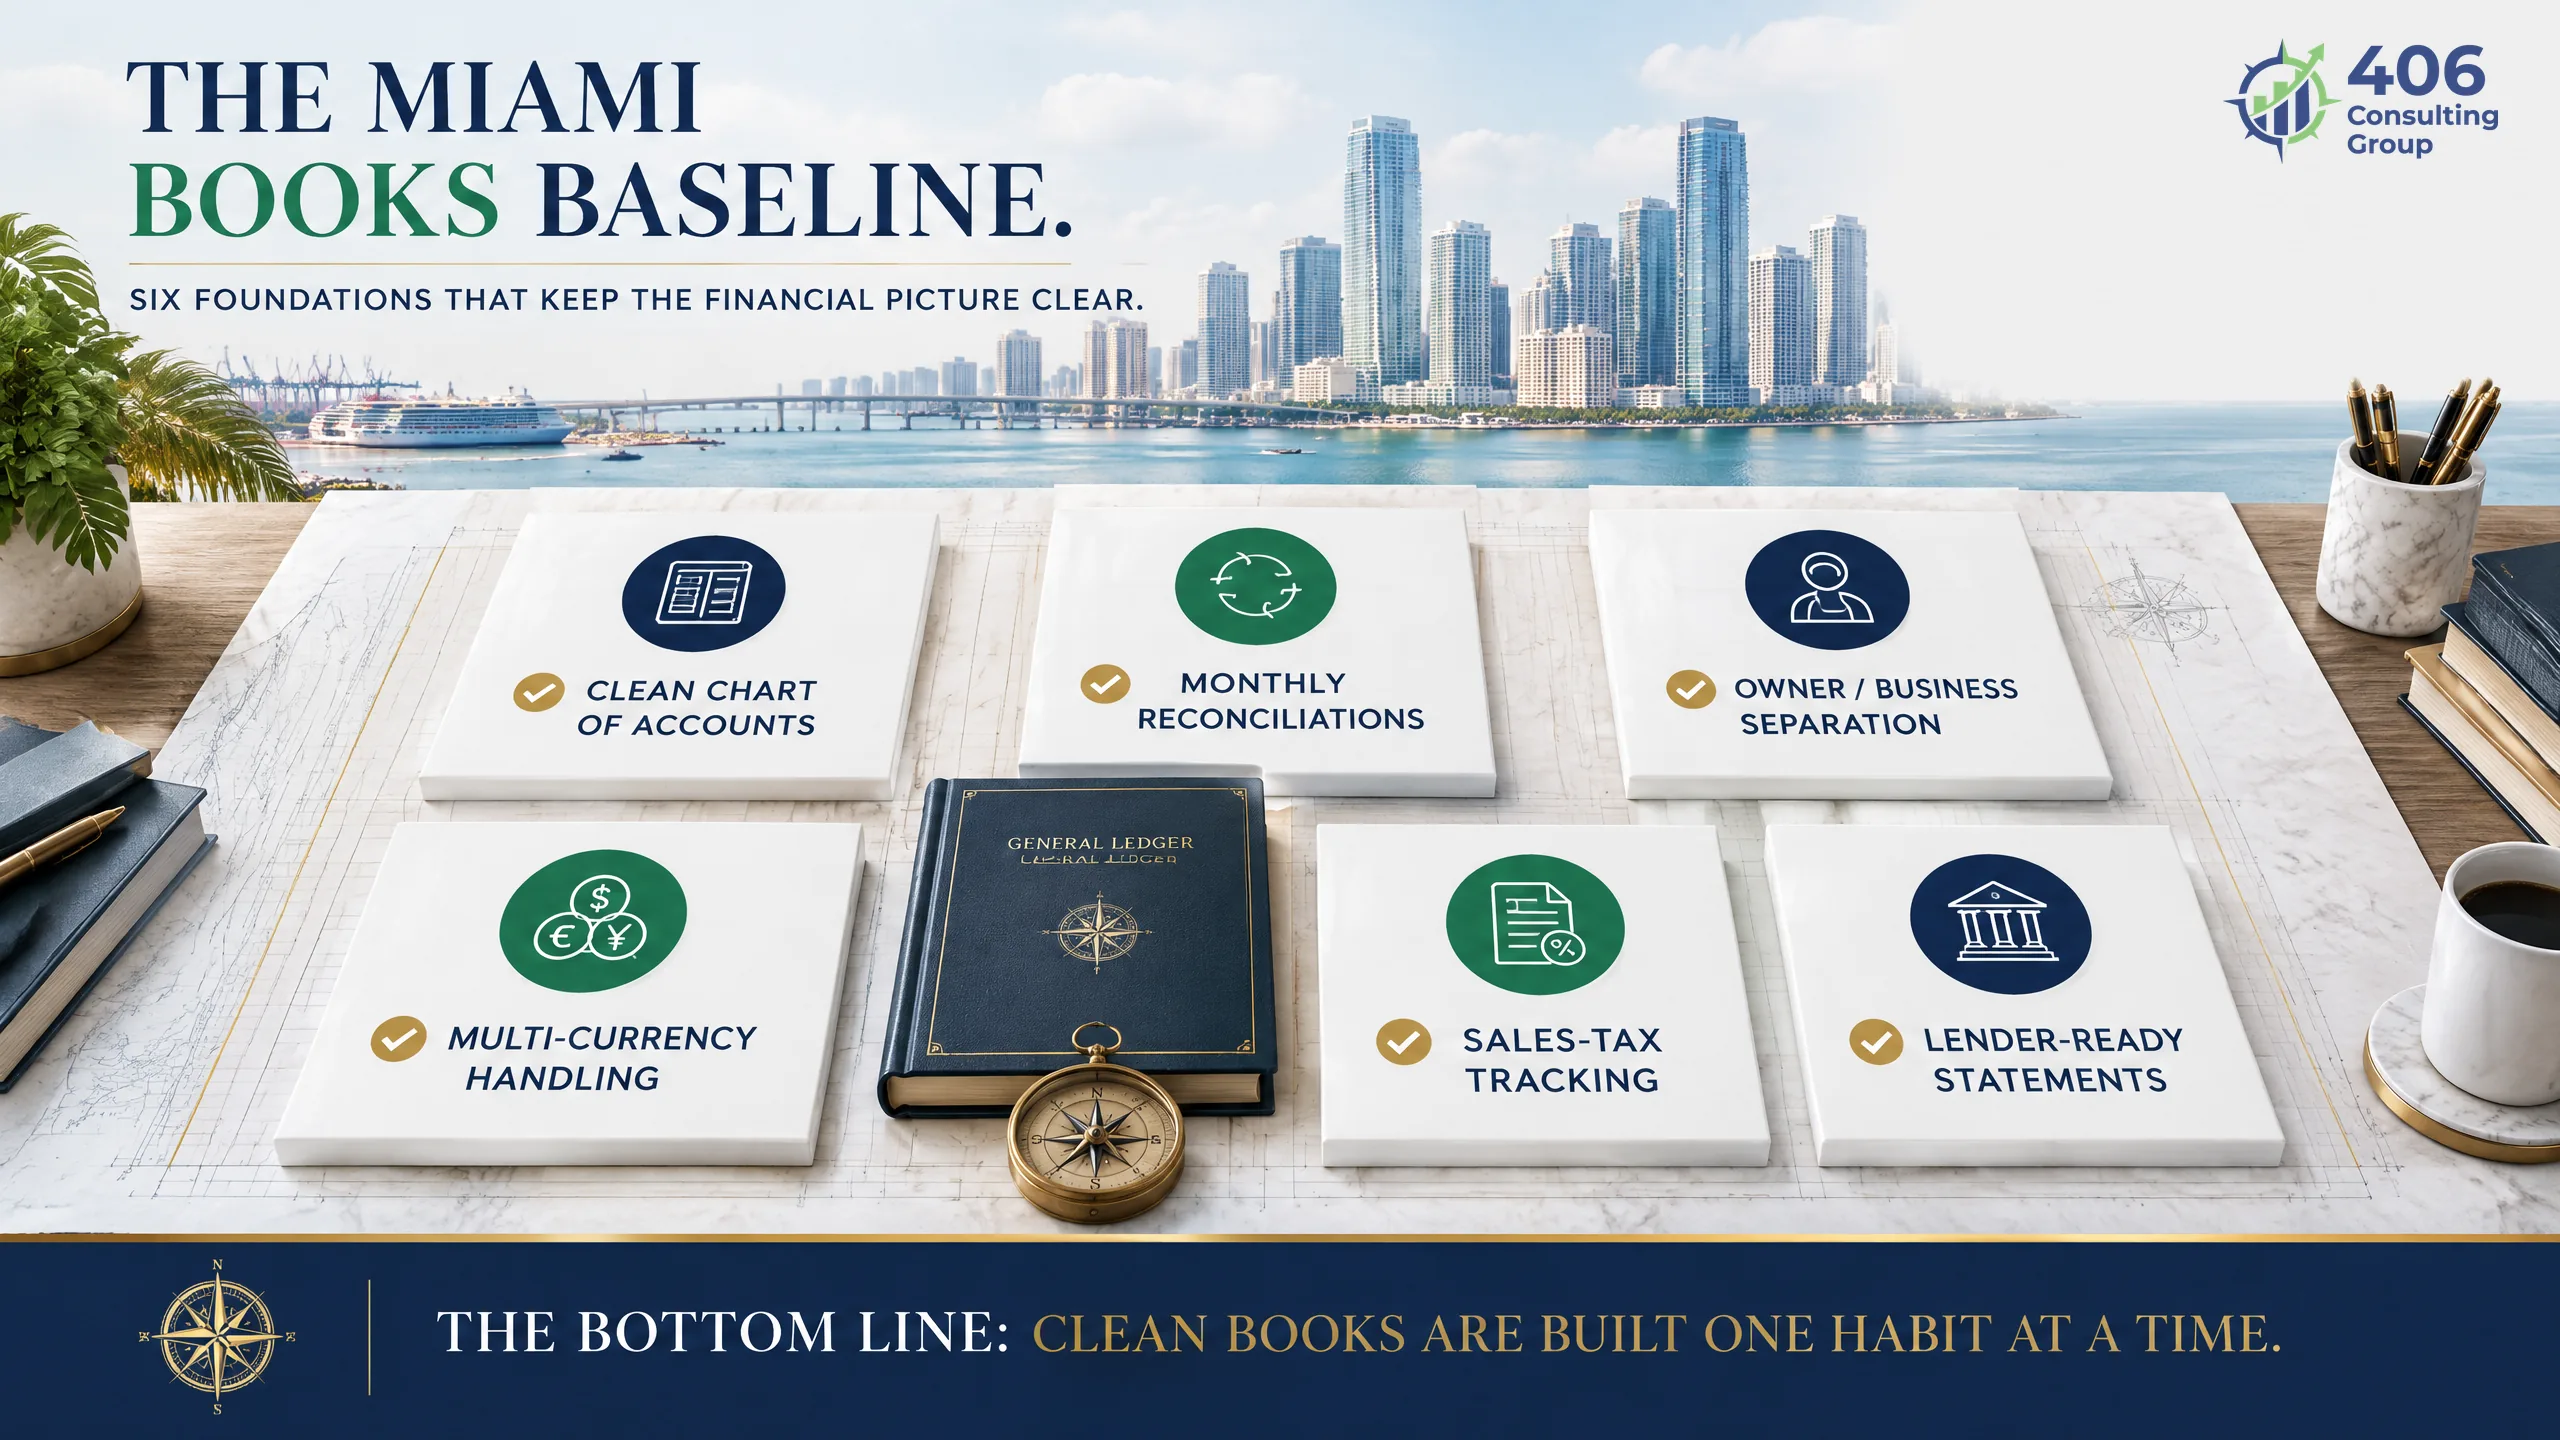
The rest of this guide walks each pressure point behind the Baseline — starting with the one that makes Miami books unlike almost anywhere else: currency.
Multi-Currency & International Transactions
Record every transaction in your USD functional currency, but keep the original source-currency amount and the exchange rate you used, and book the foreign-exchange gain or lossthat shows up between invoice and payment. That is the whole discipline — and in Miami, where a business might invoice a client in euros, pay a supplier in pesos, and settle in dollars, it is the difference between books that reconcile and books that quietly drift out of balance every month.
The trap is treating a foreign-currency invoice as if the rate never changes. You bill €10,000 when the euro is worth $1.08, so you book $10,800 in revenue. Payment lands three weeks later when the euro is worth $1.10, and $11,000 hits the bank. That extra $200 isn't more sales — it's a foreign-exchange gain, and it belongs in its own account, not buried in revenue. Do it wrong and your revenue is overstated, your reconciliation is off by exactly the FX swing, and every downstream number inherits the error.
The rule of thumb: revenue is what you invoiced in USD at the invoice-date rate; the difference at payment is an FX gain or loss. Keep the source-currency detail so anyone can retrace how you got to the dollar figure.
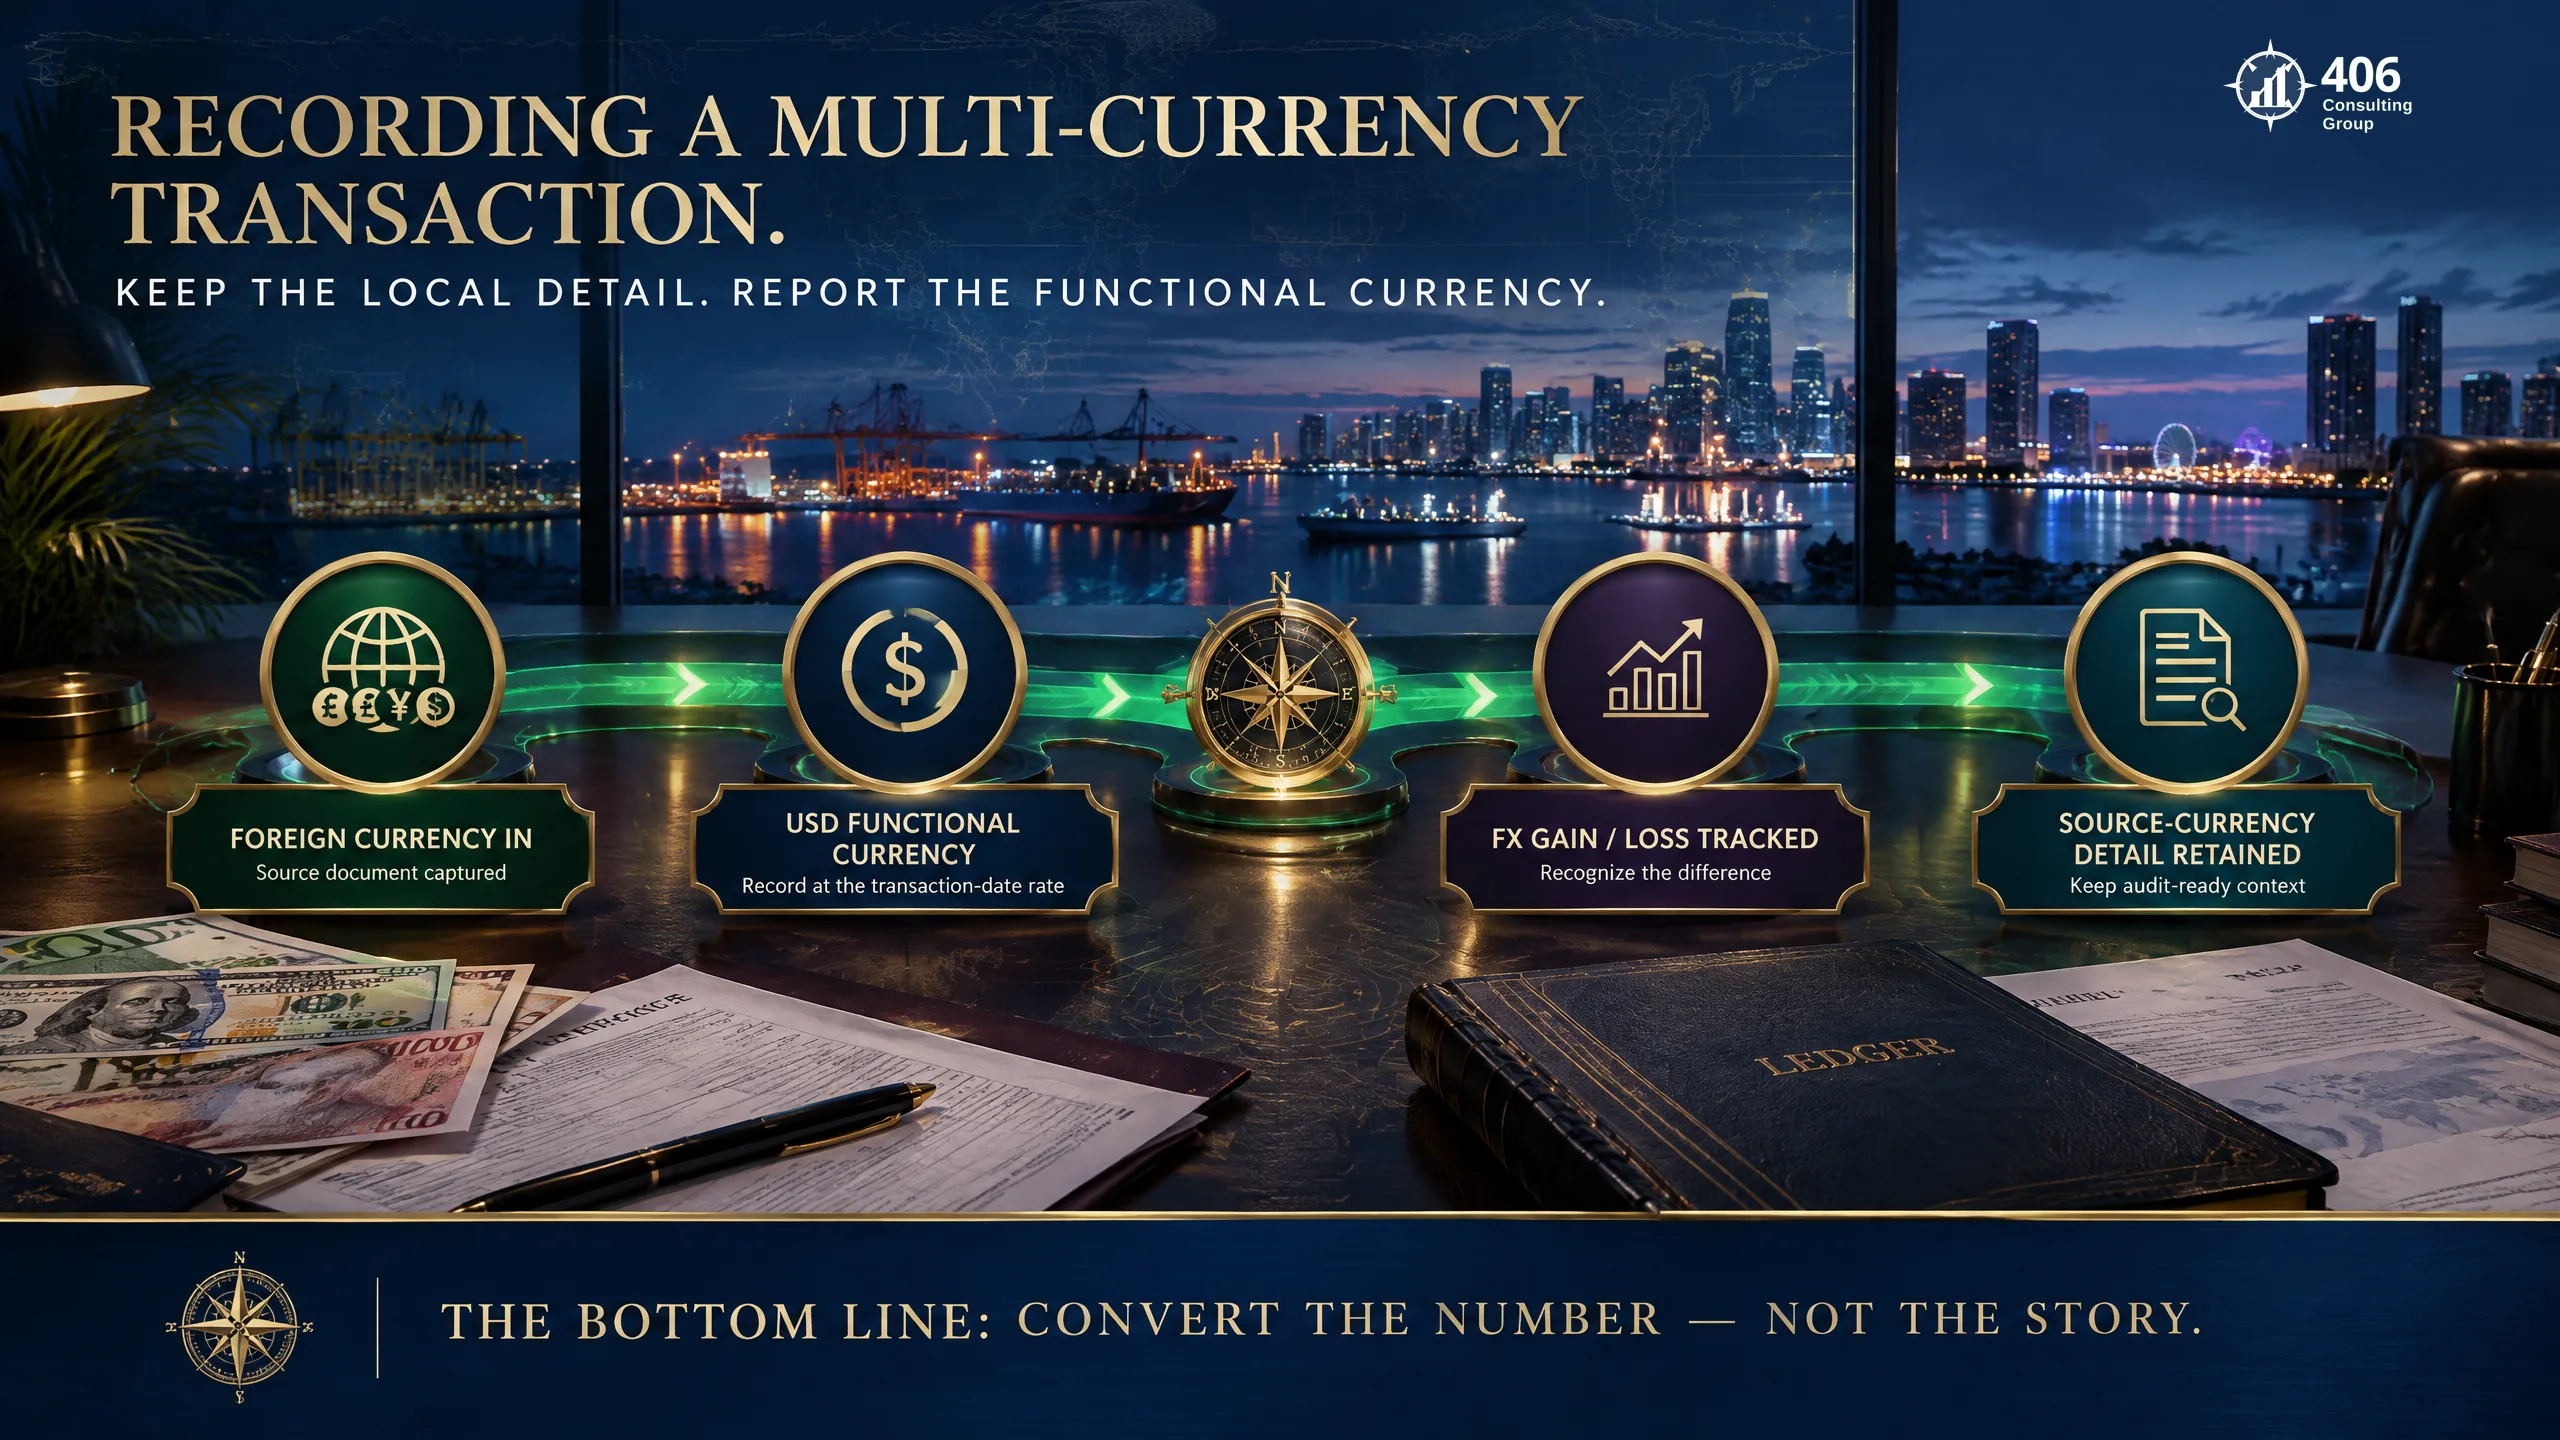
Good cloud accounting handles the mechanics if it's set up right — multi-currency turned on, a rate source chosen, and an FX gain/loss account in the chart of accounts. The judgment is in the setup and the review, which is where a bookkeeper who has actually done international books earns their keep. And when the entity itself is foreign-owned, the currency question sits underneath a bigger one: the record trail.
Foreign-Owned Entities & the Form 5472 Record Trail
If a foreign person or company owns a U.S. entity, the IRS wants a full record of every transaction between the business and its foreign owner or related parties — and the books are where that record lives. Form 5472 is the information return that reports those related-party transactions; a foreign-owned single-member LLC generally files it attached to a pro forma Form 1120. The filing itself belongs to your tax preparer. The record trail behind itbelongs to your bookkeeper — and that's the part owners underestimate.
Here's the plain-English version: Form 5472 is how the IRS keeps tabs on money moving between a U.S. business and its foreign owners — capital the owner puts in, money the business sends back out, loans, and payments between related companies. The failure-to-file penalty starts at $25,000, and "we didn't keep records" is not a defense. Your books have to show each related-party transaction with dates, amounts, currency, and what it was — capital contribution, distribution, loan, reimbursement — so the return sits on documentation, not guesswork.
What the books must capture
Every reportable transaction between the entity and a foreign owner or related party — contributions, distributions, loans, repayments, intercompany charges — with date, amount, and currency.
How to categorize it
Dedicated related-party accounts (e.g., 'Due to/from Owner') instead of dumping owner money into 'miscellaneous,' so the trail is legible at filing time.
Why it can't wait
Reconstructing a related-party trail after the fact is slow, expensive, and error-prone — and the $25,000 penalty makes clean-as-you-go bookkeeping the cheap option.
Where the filing lives
The 5472 form, penalty mechanics, and FIRPTA on property sales are the tax article's job — we keep the records that make that filing defensible.
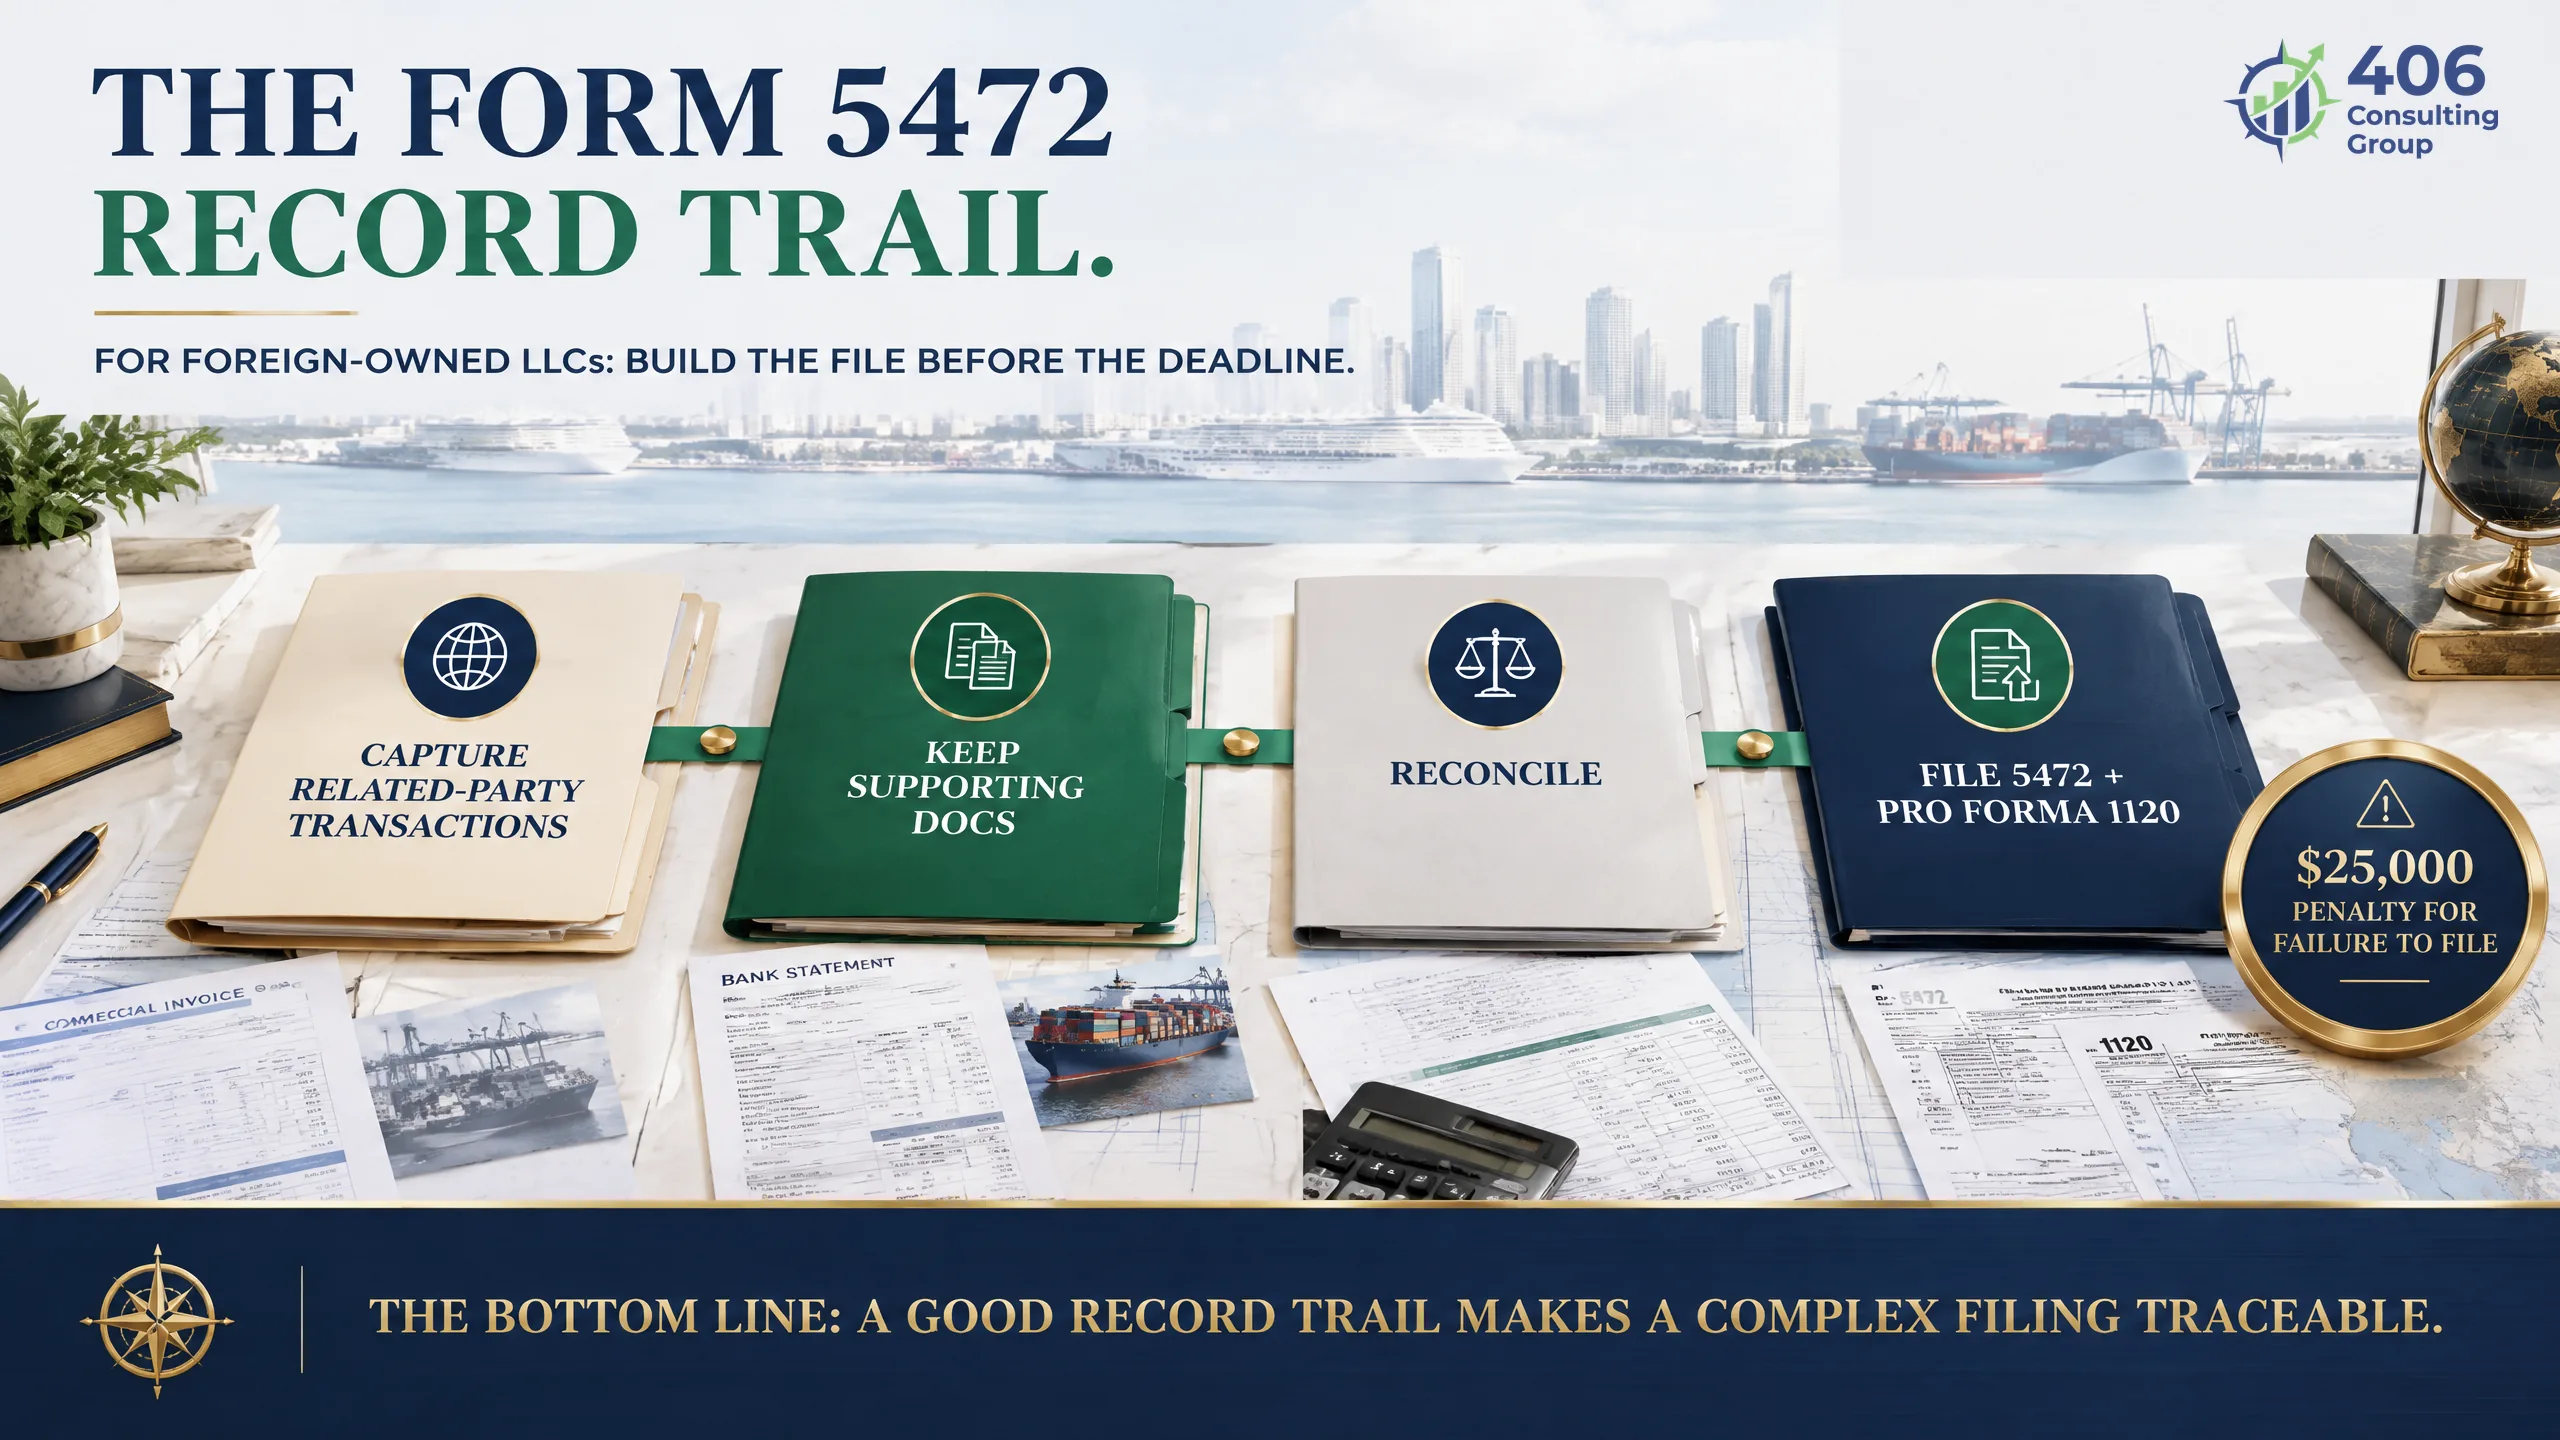
We own the records side of this. For the filing itself — how Form 5472 and the pro forma 1120 work, the penalty details, and FIRPTA when foreign owners sell U.S. property — see our Miami tax services guide. Confirm your specific filing obligations with a tax professional and the IRS Form 5472 instructions.
Real Estate & Short-Term Rental Books
Track real estate per property, rentals per unit, and short-term rental income per platform payout— because a blended number hides which property is actually making money. In a market as property-heavy as Miami, a portfolio owner running everything through one account genuinely does not know whether the Brickell condo is carrying the Little Havana duplex or the other way around. Segmented books answer that on the first page of the P&L.
Short-term rentals add a wrinkle: the platform is not paying you your gross. Airbnb or Vrbo takes its service fee, may collect and remit some taxes, and deposits a net payout that rarely matches any single guest's booking. Your books have to reconstruct gross rent, platform fees, cleaning fees, and taxes from the payout report — not just record the deposit as income. Book only the net and your revenue is understated, your expenses vanish, and your occupancy math is fiction.
A short-term rental deposit is a net number with a story behind it: gross rent minus platform fees, plus cleaning, minus taxes. Book the story, not just the deposit — or the property's real economics disappear.
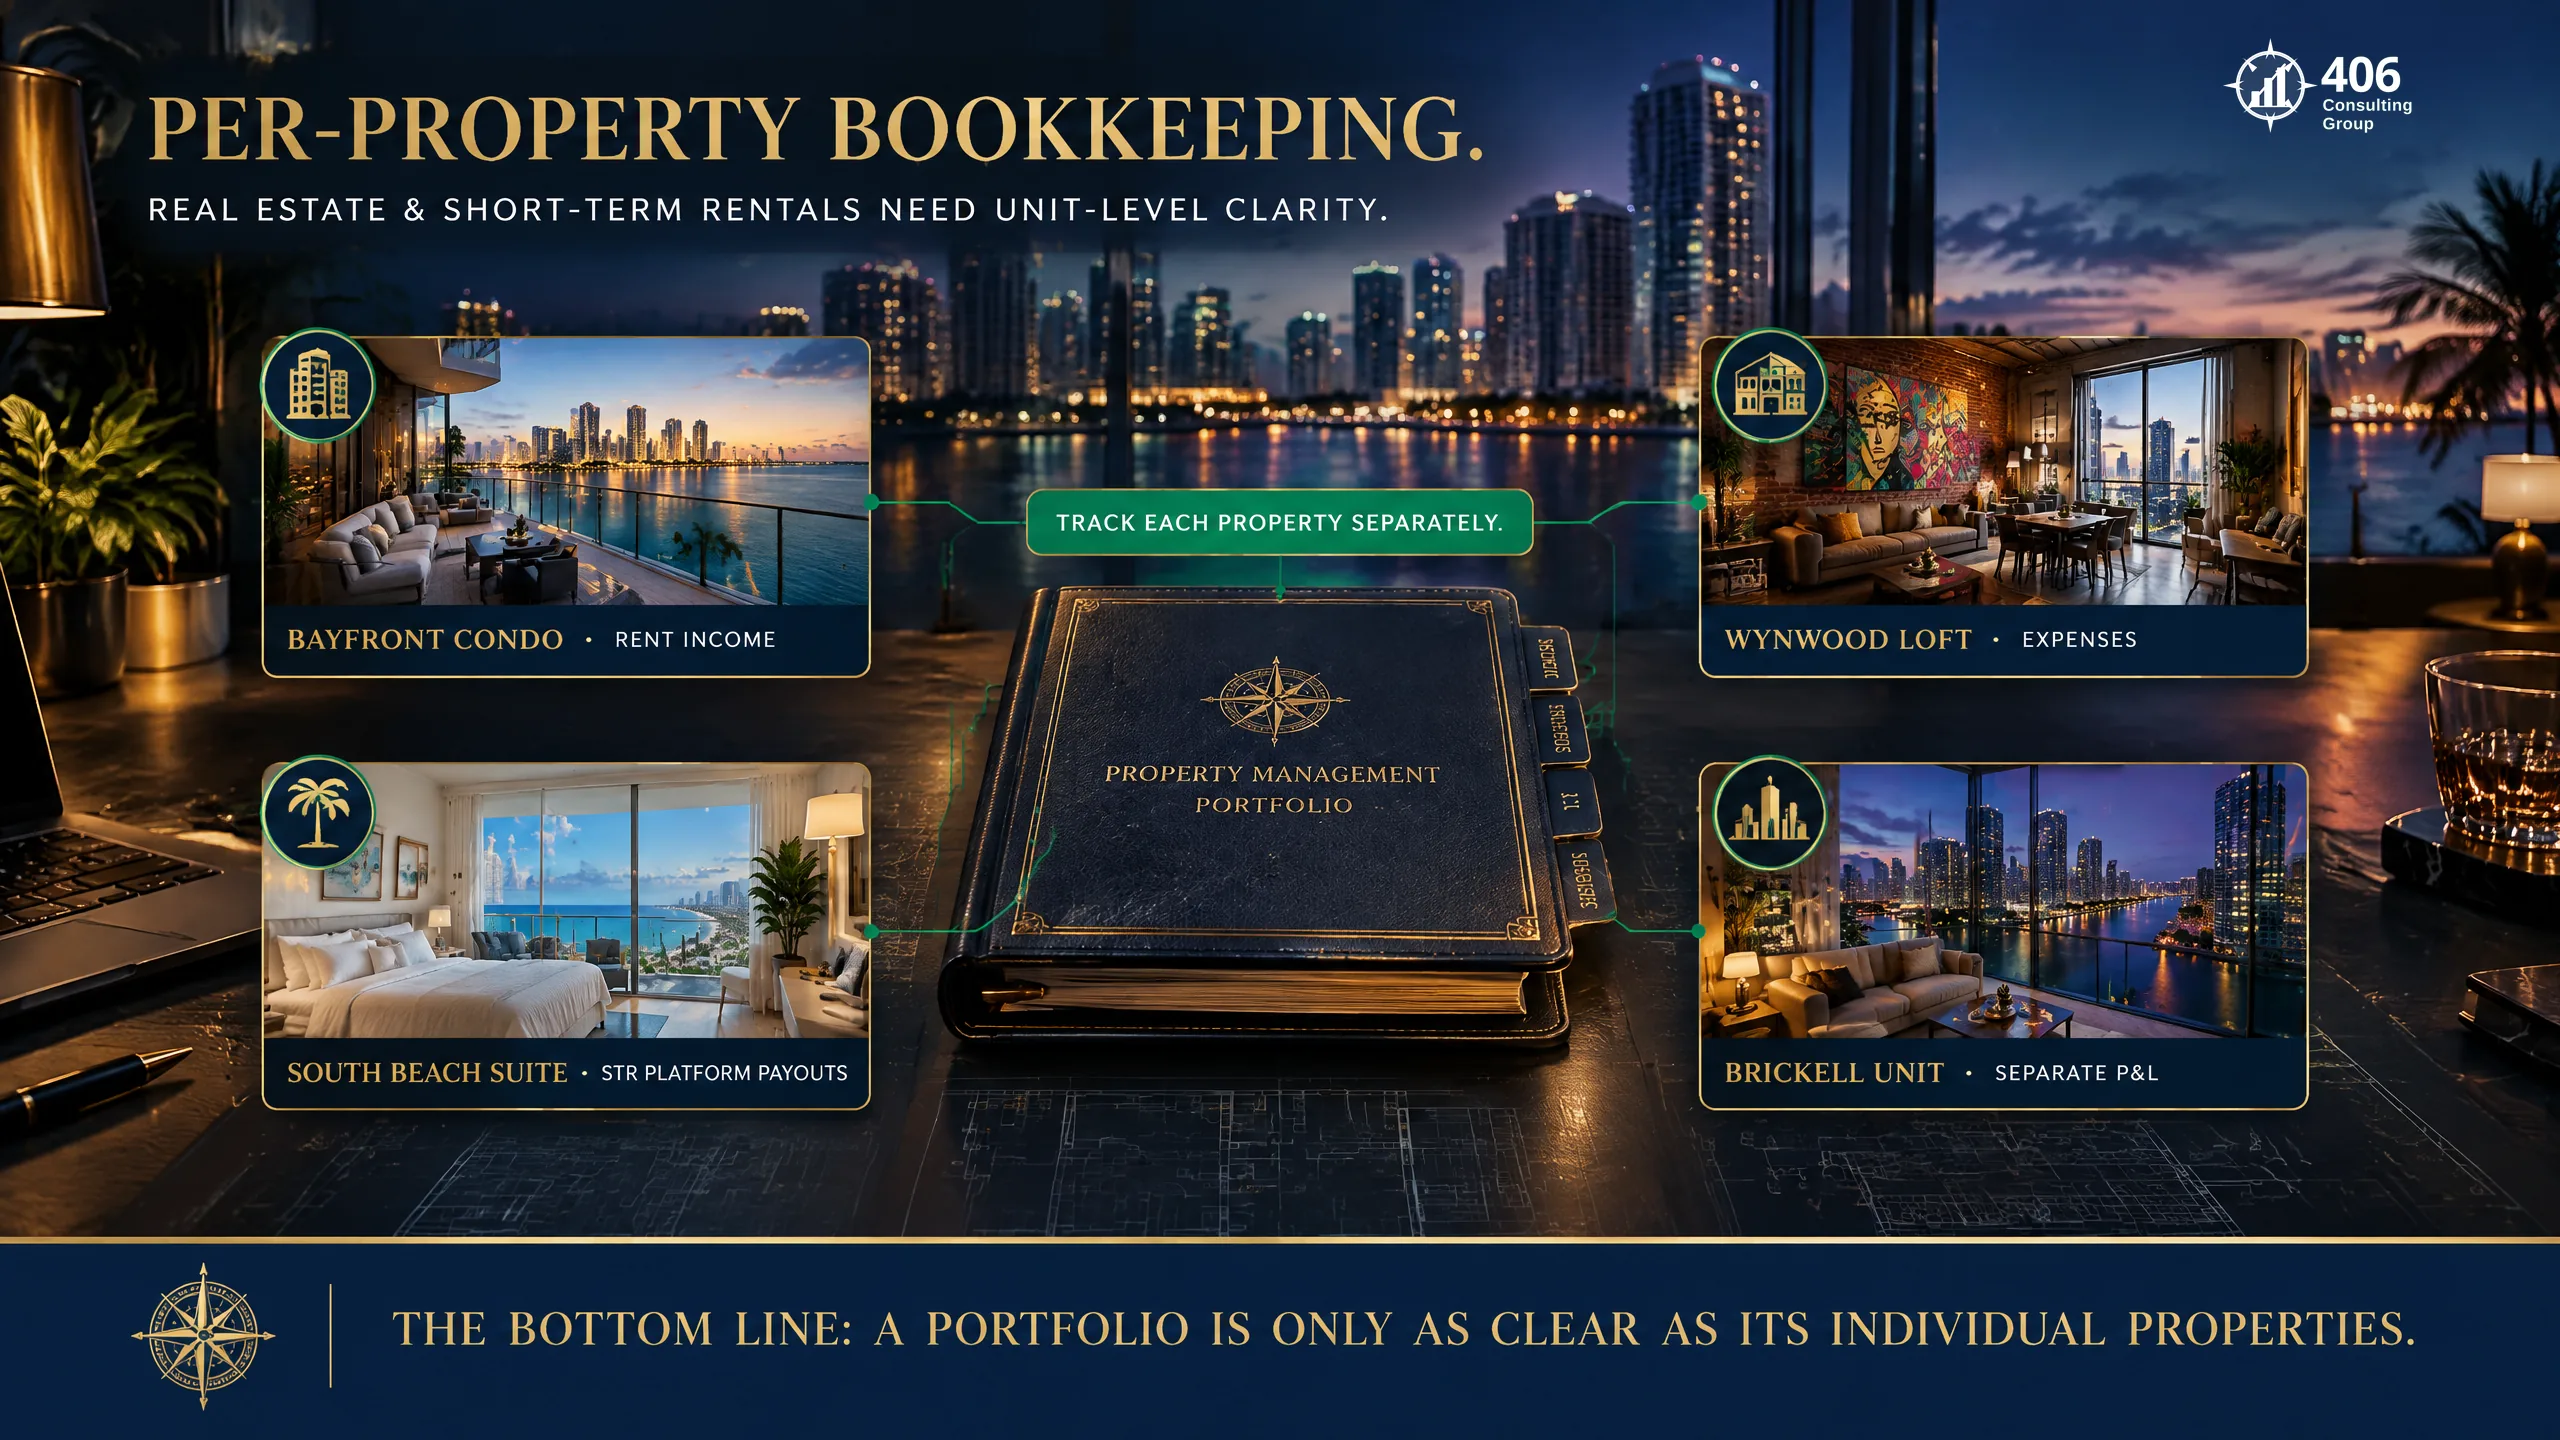
Done right, each property becomes its own mini income statement, and short-term rental payouts reconcile cleanly to platform reports. That same "track it where it's earned" discipline is what hospitality books need — for different reasons.
Restaurant & Hospitality Books
Restaurant and hospitality books live or die on three details: tips, POS tender types, and seasonal labor. Miami's dining and nightlife scene is enormous, and a restaurant that treats its POS as a black box — one number a day dropped into "sales" — is flying blind on the exact numbers that decide whether it survives. The books have to break the day apart the way the POS already does.
That means recording sales by tender type — cash, card, gift card, delivery apps — so deposits reconcile and the credit-card fees and delivery commissions land where they belong. It means handling tips correctly: distinguishing tips owed to staff (a liability that flows through, not revenue) from service charges the house keeps, and tracking them for payroll and the tip-credit rules. And it means seeing laboragainst the season, because Miami's winter high season and summer slowdown swing staffing costs hard, and a labor-cost percentage that looks fine in February can sink you in August.
Tender-type detail
Cash, card, gift card, and delivery-app sales recorded separately so daily deposits reconcile and processor and commission fees are visible, not netted away.
Tips vs. service charges
Tips owed to staff booked as a pass-through liability; house-kept service charges as revenue — the distinction drives payroll and tip-credit tracking.
Seasonal labor
Labor cost tracked against Miami's high-season/off-season swing so the labor-to-sales ratio is watched all year, not just when it's easy.
Prime cost visibility
Food, beverage, and labor tracked tightly enough to compute prime cost — the number that actually tells a restaurant operator if it's working.
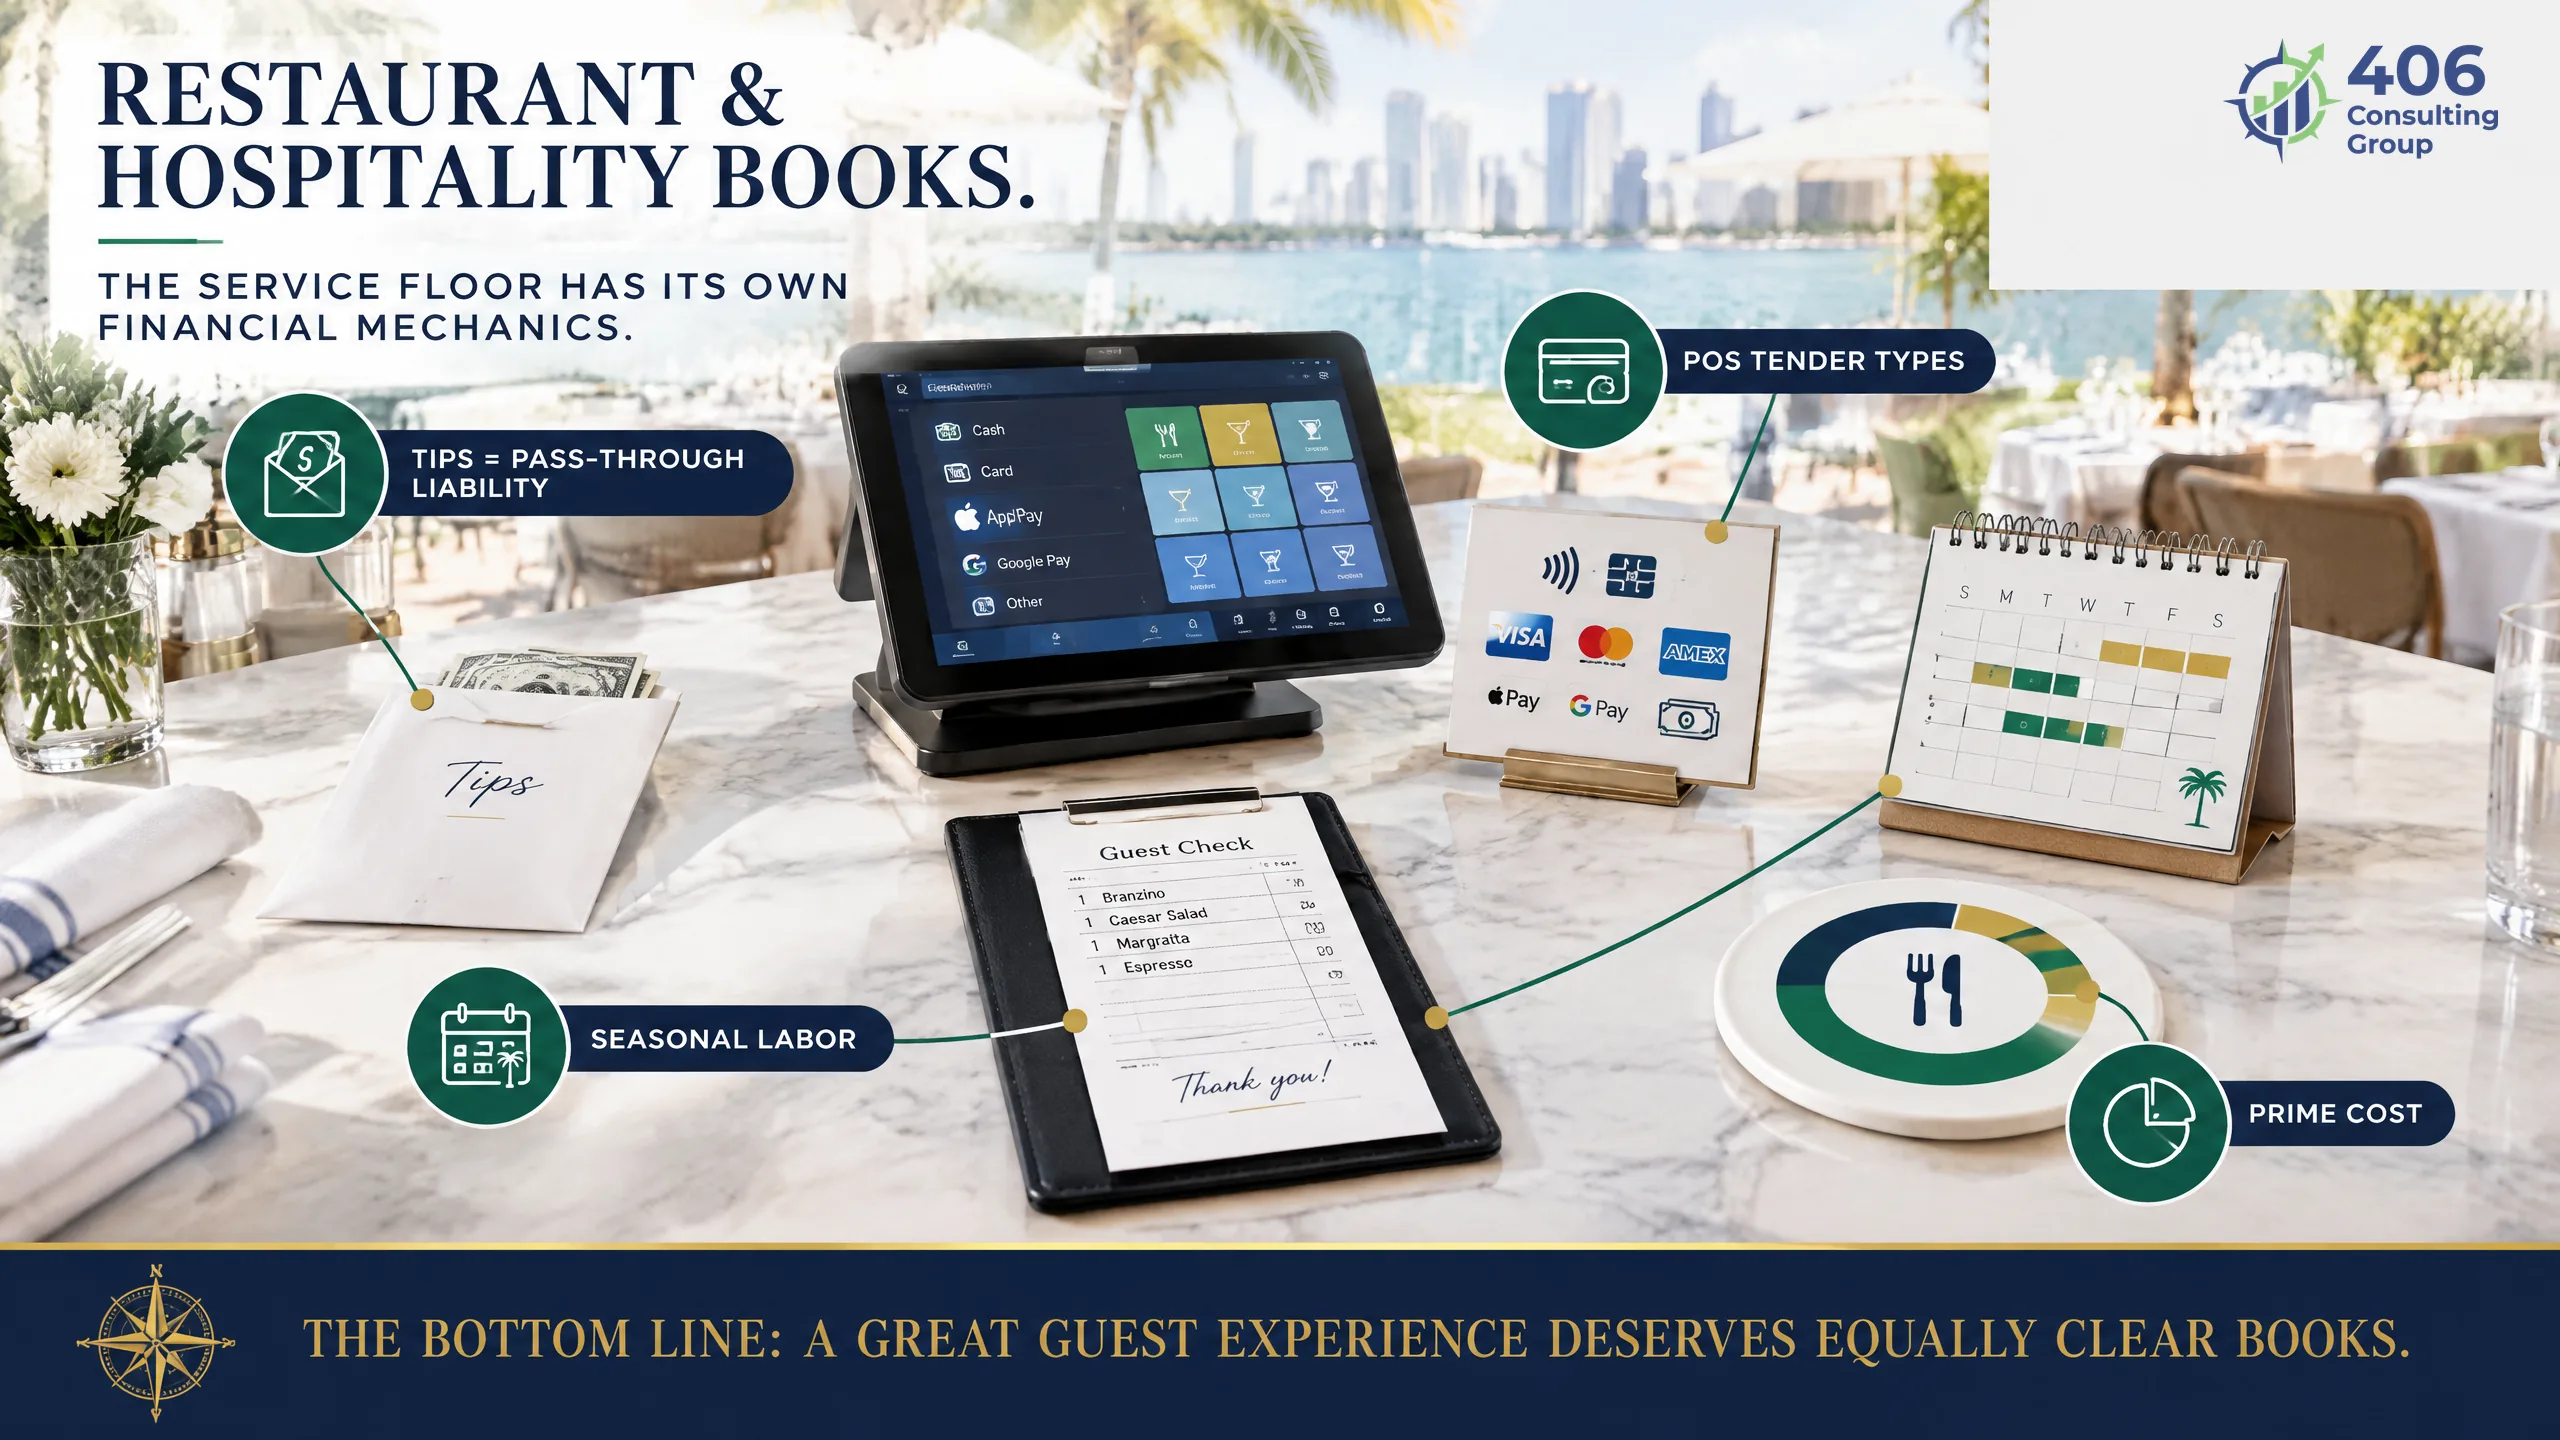
Every one of those sales also carries a tax the books have to capture correctly — the Miami-Dade sales tax.
Sales & Use Tax at ~7% in Miami-Dade
Collect and remit Florida sales tax on taxable sales at the Miami-Dade combined rate of roughly 7% (the state's 6% plus about a 1% discretionary county surtax), and accrue use taxon taxable items you bought without paying tax — often out-of-state or cross-border purchases. The rate is the easy part. The bookkeeping discipline is treating sales tax as money you're holding for the state, not as your own cash sitting in the bank.
When collected sales tax rides inside your bank balance, it looks like you have more money than you do, and remittance day becomes a scramble. Clean books route it to a sales tax payableliability the moment it's collected, so the balance sheet always shows what you owe the state. Use tax is the piece owners forget entirely: buy equipment or supplies from an out-of-state or foreign vendor who didn't charge Florida tax, and you generally owe use tax on it yourself. In an import-heavy market like Miami, that comes up more than most owners expect.
Sales tax you collect is never your money — it's the state's money in your custody. Books that park it in a payable account keep you honest and keep remittance day boring.
Confirm current rates and the county surtax with the Florida Department of Revenue, since surtax rates change. Which brings up the reality behind most bookkeeping calls we get in Miami: the books fell behind while the business took off.
Catch-Up & Cleanup — the Fast-Growth Miami Reality
Most Miami bookkeeping projects start with a cleanup, not a clean slate — because the business grew faster than its books. That is not a character flaw; it's what happens when an owner is chasing the opportunity in front of them and the bookkeeping is the thing that slips. The fix is a structured catch-up: rebuild the chart of accounts, reconcile every account month by month, sort the personal-versus-business mess, and re-categorize the transactions that got dumped into the wrong place while everyone was busy.
Catch-up in Miami carries extra weight because of everything above it. If the books are behind andthe entity is foreign-owned, the related-party trail has to be reconstructed for the 5472. If there's multi-currency activity, months of FX has to be untangled. If it's a restaurant or a rental portfolio, each location or property has to be pulled apart from the blended pile. Behind here isn't just behind — it's behind on the exact records the IRS and a lender will ask for.
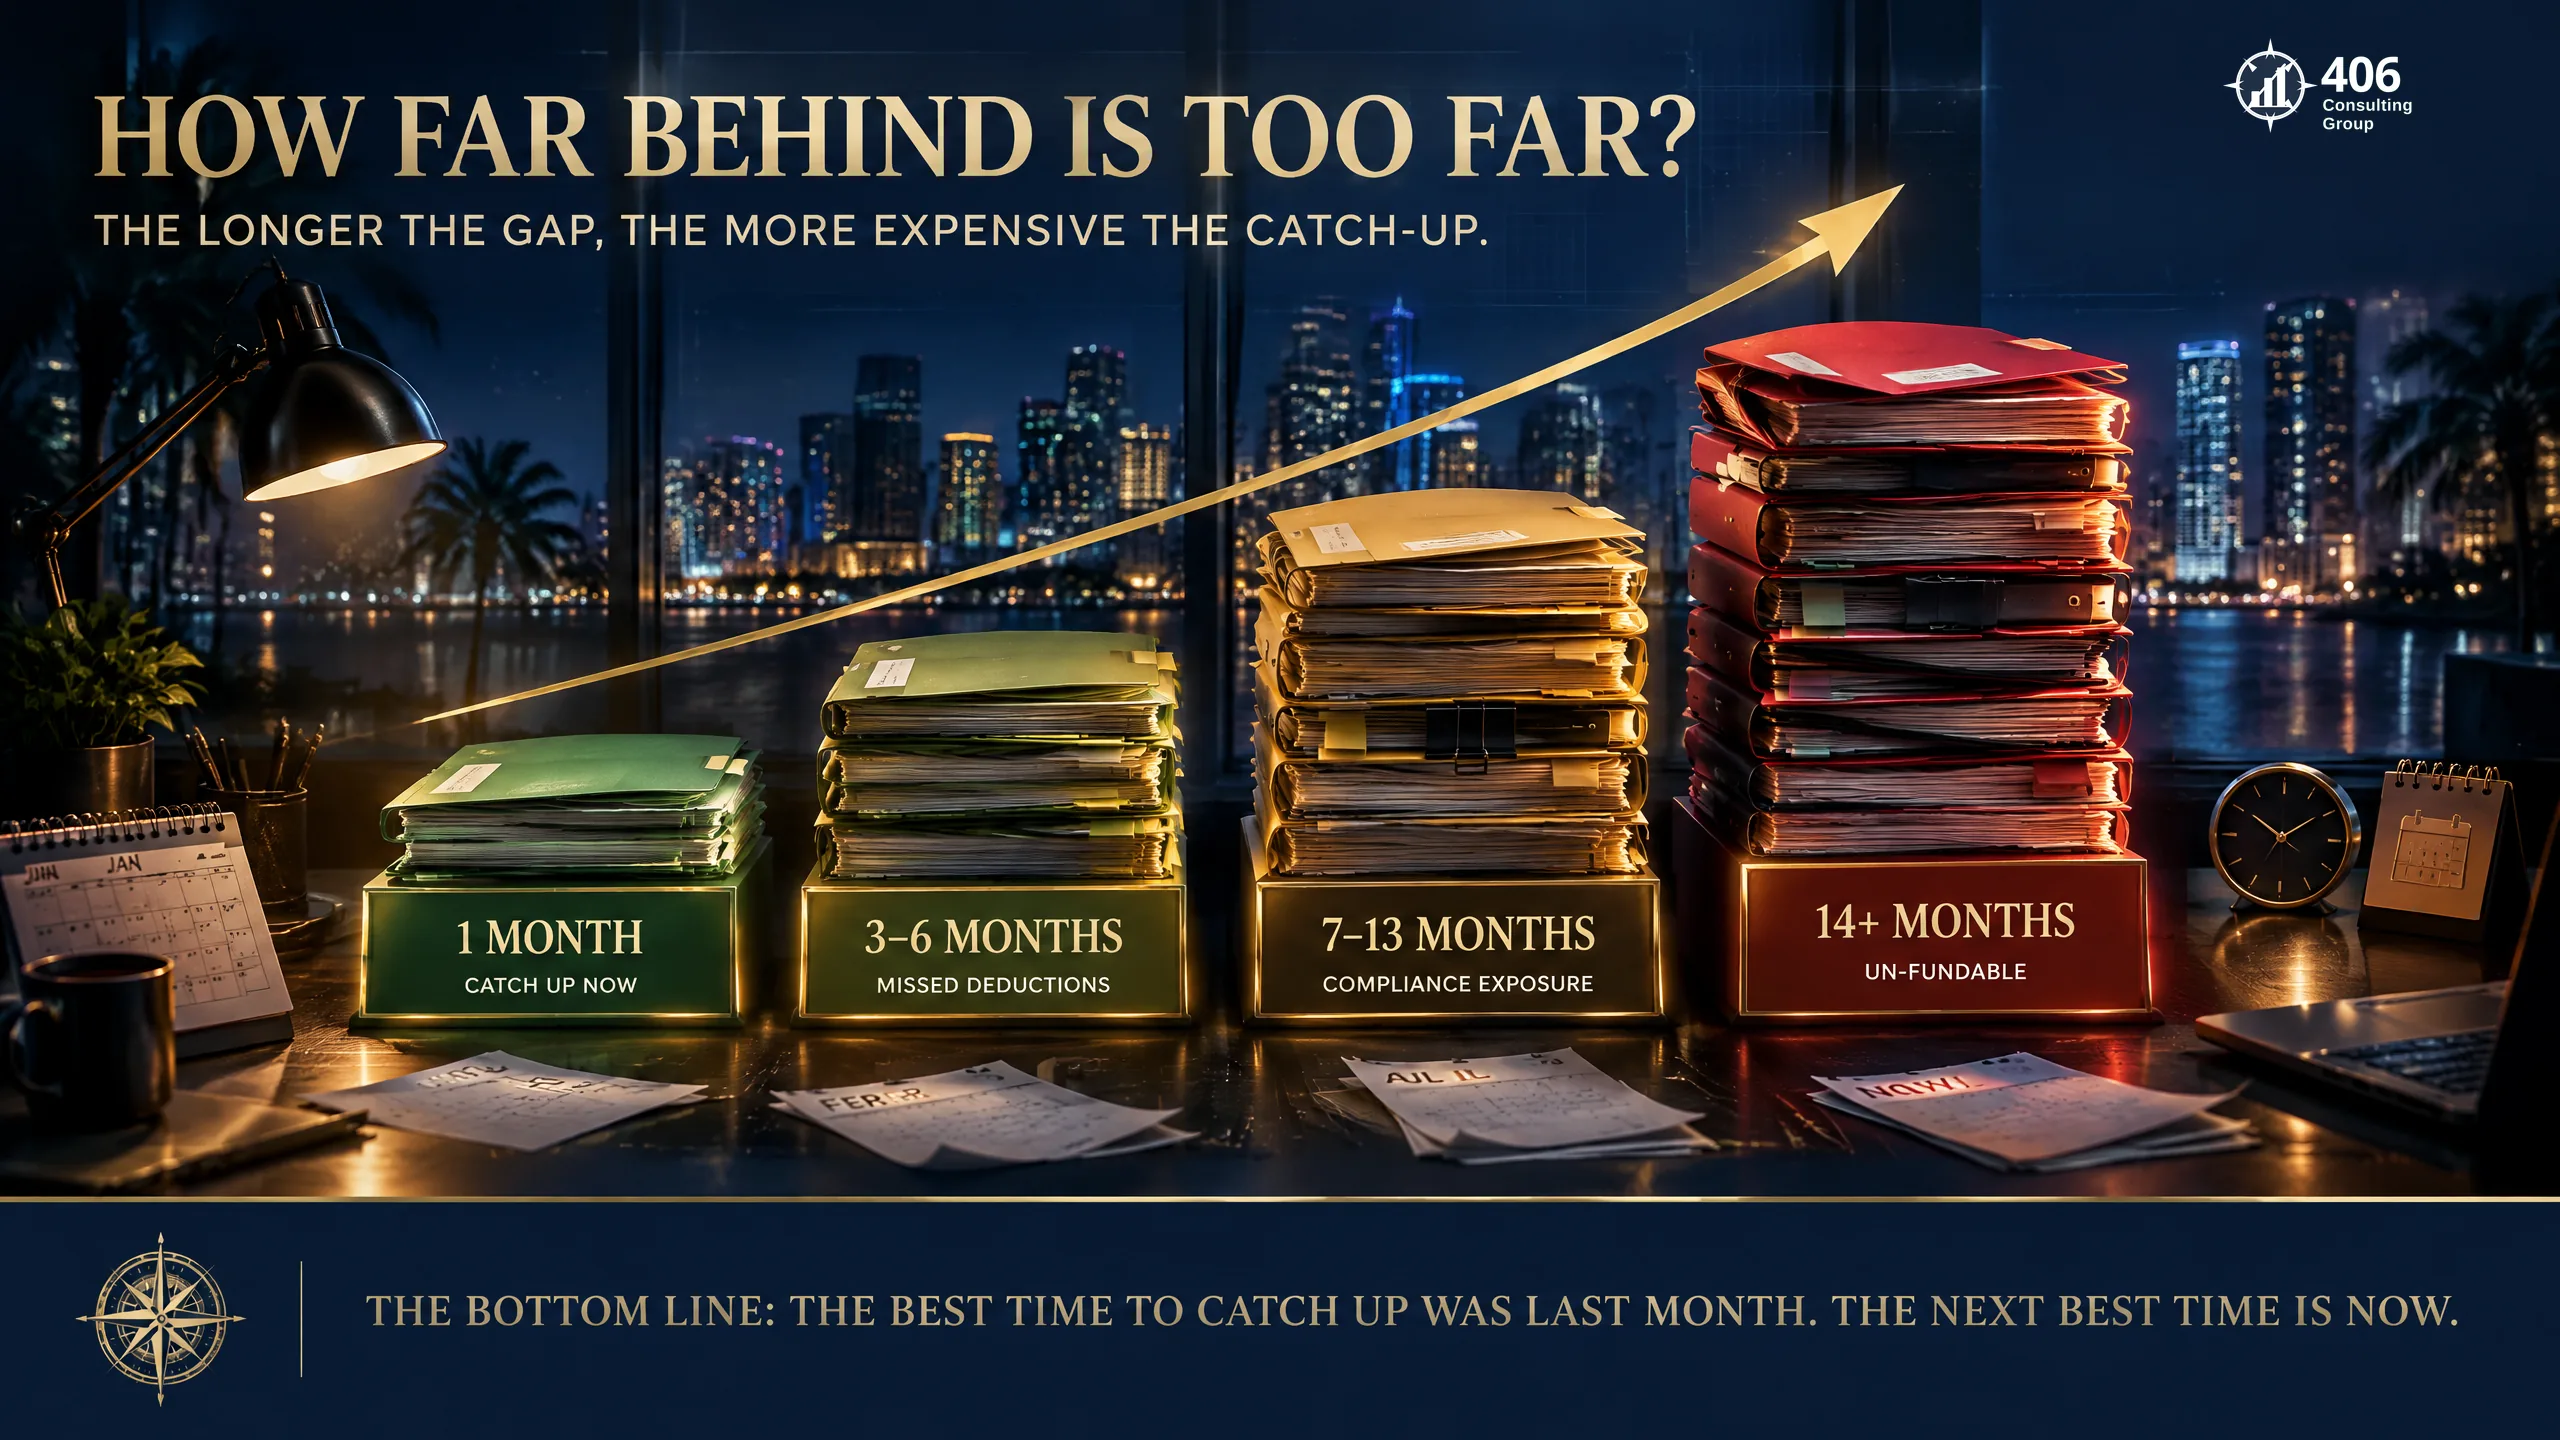
The honest answer to "is it too late?" is almost always no — catch-up is routine work, and the sooner it starts the cheaper it is. The payoff shows up the first time you need money.
Books That Pass a Lender
Miami growth runs on capital — a line of credit, an equipment loan, an SBA deal, a mortgage on the next property — and a lender decides yes or no by reading your financials. Books that pass a lender show a clean separation of business and personal money, a readable profit-and-loss that reflects true profitability (per property or per location, where that matters), and a balance sheet that supports the ask. Messy books answer the lender's question before you finish it: no.
This is where our background matters. Carrie, our co-founder, spent her career in commercial banking and underwriting — she has personally reviewed 300+ loans and knows exactly how a lender reads a set of financials and where they lose confidence. We keep your books to that standard from the start, so when you walk into the bank the numbers are already speaking the lender's language. In a foreign-ownership or multi-currency situation, that credibility gap is even wider, and clean books close it.
A booming Miami business with messy books isn't a fundable business. The quality of your books is often the difference between a fast yes and a slow, expensive no.
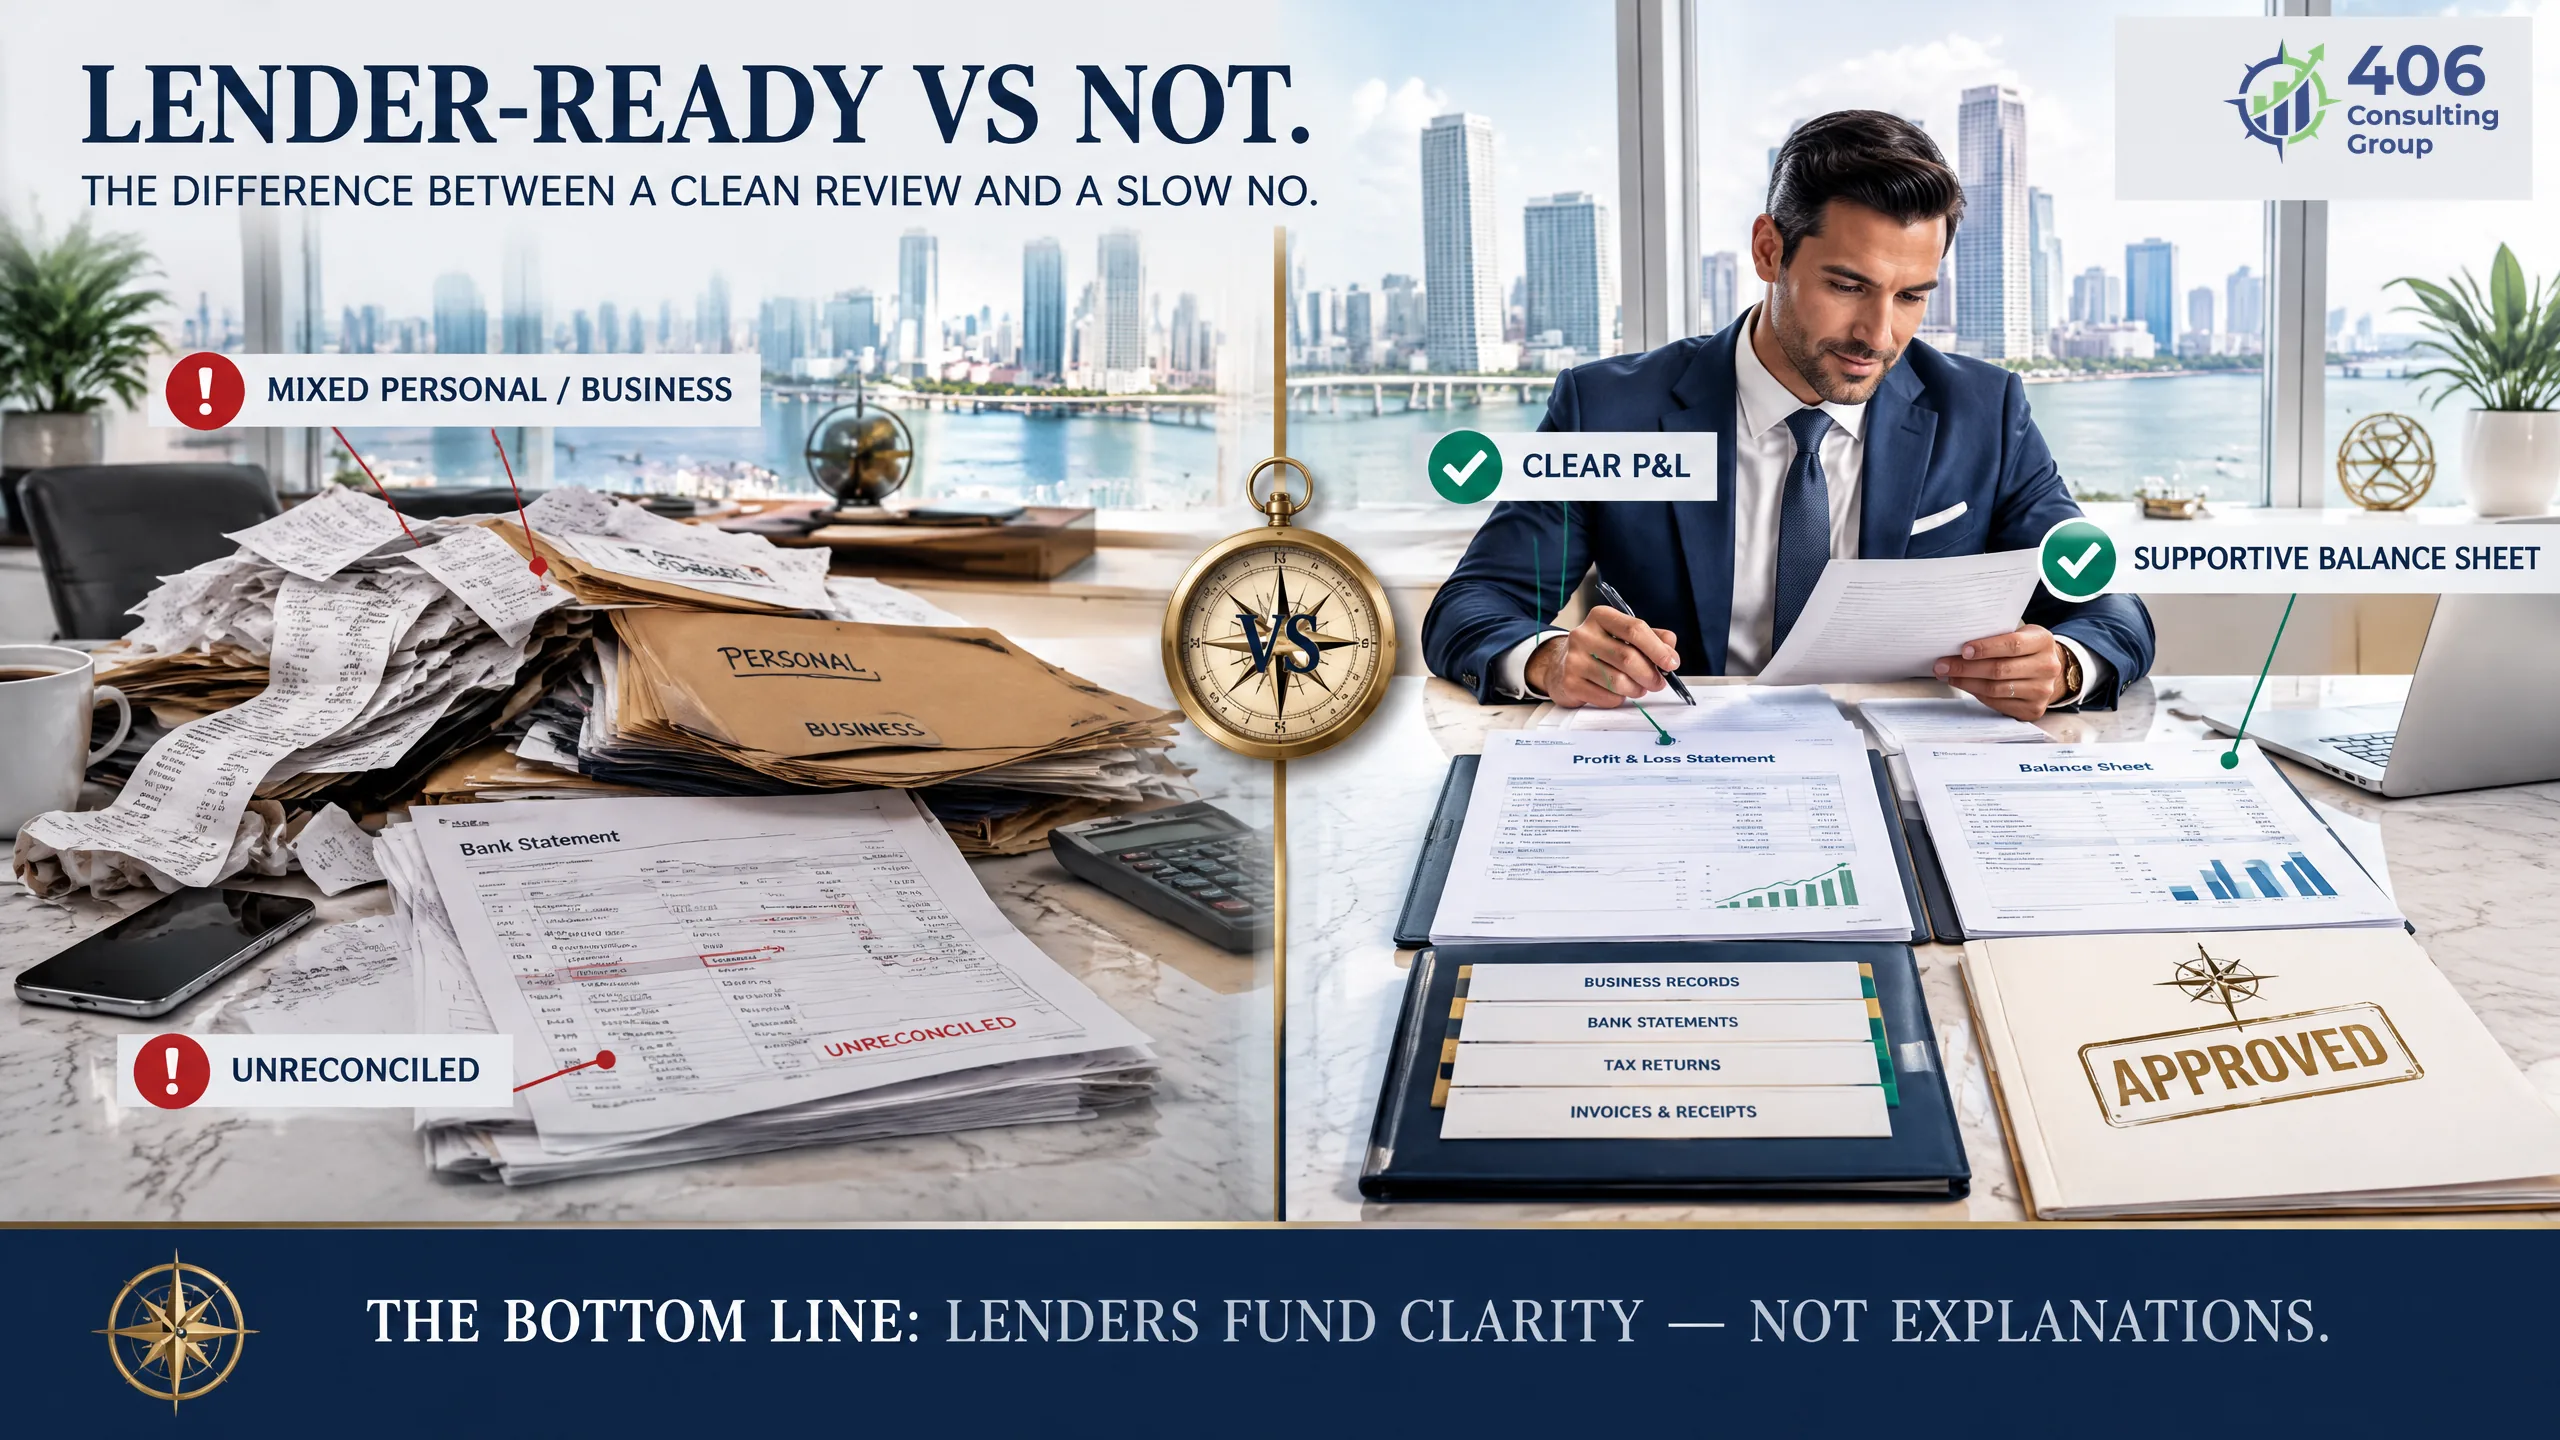
When the goal is a loan package, forecast, or full financial story, that's controller and CFO territory — see our Miami CFO & controller services guide. Clean books are the foundation the whole package is built on. Getting there is a matter of the right tools and a steady rhythm.
Tools & Monthly Close Cadence
Good Miami bookkeeping runs on cloud accounting with multi-currency turned on, connected bank feeds, a POS or property-management integration where it applies, and a disciplined monthly close. The tools matter less than the setup and the cadence: a chart of accounts built for your actual business, related-party and FX accounts in place, and a close checklist that runs the same way every month.
A real monthly close means reconciling every account, reviewing the categorizations, booking the FX gains and losses, checking sales tax payable against what was collected, and producing statements a human has actually looked at. That rhythm is what turns bookkeeping from a shoebox you dread into a monthly readout you can steer by — and it's the mentality behind our whole approach: don't boil the ocean, build a repeatable process and run it. When you're ready to see where your systems stand, the Financial Maturity Assessment is a fast way to find out.
~80%
of our local clients are fully remote
They never come into the office — the monthly close runs on cloud accounting, by choice.
None of this requires a bookkeeper down the street. Cloud accounting, live feeds, and screen-share reviews mean the close runs the same whether we're in Miami or in Montana. What matters is expertise in what makes Miami books hard — and to make that concrete, here's how a cleanup actually plays out.
Illustrative Example: A Wynwood Restaurant Group Cleans 14 Months of Books
Here's how a Miami cleanup tends to unfold. The scenario below is a hypothetical composite for illustration — not a real, named client — but every piece of it is a pattern we see.
Illustrative Scenario
A Wynwood restaurant group opens a third and fourth location inside eighteen months. Revenue roughly triples, and the books — run part-time by a founder between shifts — fall 14 months behind. Daily POS totals were dropped into a single "sales" line, delivery-app deposits were booked net, a partner's capital contribution from abroad was sitting in "other income," and sales tax collected was blended into the operating account. Their bank has verbally offered a line of credit — pending "current financials."
The catch-up: rebuild the chart of accounts by location; re-drive 14 months of sales from POS reports by tender type; separate tips (a pass-through liability) from house service charges; reconstruct delivery-app gross sales, commissions, and fees from payout reports; move the foreign partner's contribution into a documented related-party account for the 5472 trail; route collected sales tax to a payable account and true up what was owed; and reconcile every bank and card account, month by month.
The result (illustrative): four location-level P&Ls that show one store quietly losing money on labor, a sales-tax liability that was real and now provided for, a clean related-party trail ready for the foreign-ownership filing, and a financial package the lender could actually underwrite. The line of credit moves from "pending" to fundable.
14 mo.
of books rebuilt from POS and payout reports
4
location-level P&Ls, replacing one blended number
$0
surprises left for tax season or the lender
Figures are illustrative and simplified to show the shape of the work, not a promise of results. The point stands: behind is fixable, and clean books pay for themselves the first time someone important reads them.
FAQ: Miami Bookkeeping Questions
What's different about bookkeeping in Miami?
Miami bookkeeping regularly involves things a generic bookkeeper rarely handles together: transactions in multiple currencies, entities owned by foreign persons or companies, real estate income split across properties and short-term-rental platforms, and a huge tips-and-seasonal-labor hospitality sector — all on top of Florida's ~7% Miami-Dade sales and use tax. Florida's state side is light (no personal income tax; only C-corporations pay the 5.5% corporate income tax), but the complexity lives in how money moves, not in a state income-tax return. Your books have to serve as a currency ledger, an IRS record trail, a per-property P&L, and a lender's underwriting file — often at once.
How do I record foreign or multi-currency transactions?
Record everything in your USD functional currency, but keep the original source-currency amount and the exchange rate you used, and book the foreign-exchange gain or loss that appears between the invoice date and the payment date in its own account. For example, a €10,000 invoice booked at $1.08 is $10,800 of revenue; if $11,000 arrives when the euro is worth $1.10, the extra $200 is an FX gain, not more sales. Turn on multi-currency in your cloud accounting, choose a rate source, and add an FX gain/loss account — then have someone who has done international books review the setup.
What records does a foreign-owned LLC need for the IRS?
A foreign-owned single-member LLC generally must file Form 5472 (attached to a pro forma Form 1120) to report transactions between the business and its foreign owner or related parties, and the failure-to-file penalty starts at $25,000. Your books are where the supporting record trail lives: every related-party transaction — capital contributions, distributions, loans, repayments, intercompany charges — documented with date, amount, currency, and type, and posted to dedicated related-party accounts rather than 'miscellaneous.' The filing is your tax preparer's job; keeping the defensible records is bookkeeping. Confirm your obligations with a tax professional and the IRS Form 5472 instructions.
How do I track Airbnb or short-term-rental income?
Don't just book the deposit — reconstruct the story behind it, per property. A platform payout is a net number: gross rent minus the platform's service fee, plus cleaning fees, minus any taxes the platform collected and remitted. Pull the platform's payout report and record gross rent as income, platform fees and commissions as expenses, cleaning fees appropriately, and taxes correctly, all tracked per unit. Booking only the net understates revenue, hides expenses, and makes occupancy and profitability math meaningless. Each property should read as its own mini income statement that reconciles to the platform report.
How far behind is 'too far behind' to catch up?
Almost never too far. Catch-up bookkeeping is routine work — we regularly rebuild a year or more of books from bank feeds, POS reports, and platform payout statements. The real cost of waiting isn't that it becomes impossible; it's that it gets more expensive and riskier, especially in Miami where being behind can also mean a missing Form 5472 related-party trail or months of untangled multi-currency activity. The sooner catch-up starts, the cheaper and cleaner it is — and you'll want it done before tax season or a lender call, not during.
Do you do bookkeeping remotely for Miami clients?
Yes — we serve Miami and Florida businesses entirely remotely, and about 80% of our own local clients run the whole relationship that way and never come into an office. Modern bookkeeping runs on cloud accounting, live bank feeds, and screen-share reviews, so the work happens the same whether your bookkeeper is in Miami or across the country. What matters is expertise — multi-currency, foreign-owned entity records, real estate and short-term rentals, hospitality, and Miami-Dade sales tax — not proximity. A great remote bookkeeper who knows those beats an okay local one who treats your books like any other.
Miami Books Snapshot
What Miami books must handle
Miami Bookkeeping
Clean, international-ready, remote.
About the Author
Jason Anderson
Co-Founder, 406 Consulting Group
Jason is a big-firm-trained accountant and Six Sigma systems builder who designs clean, audit-ready, lender-ready books from a whole-company view — delivered remotely to Miami and Florida businesses.
Read the Full Story