
A Maturity Score Is the Easy Part.
The Plan — and the Partner — Is What Changes Your Business
Maturity assessments are everywhere now. But a score doesn't move a business — a sequenced plan that fixes your weakest link first, and someone who holds you to it, does. Here's the difference.
Maturity assessments are having a moment. Every consultant, every software platform, every LinkedIn post has a quiz that spits out a tidy score and a rung on some ladder. And they're not wrong — knowing where you stand is a real first step. But here's what almost nobody says out loud: the score changes nothing. We've watched owners get a slick assessment, feel genuinely seen for an afternoon, and land in exactly the same spot six months later. The number isn't the product. The sequenced planthat fixes your weakest link first — and a partner who actually holds you to it — is.
By Jason Anderson
Co-Founder, 406 Consulting Group
Degreed accountant with 10+ years in tax and a decade of enterprise operations and accounting at BP — with a Six Sigma discipline for systems and job costing.
Figures and the example business below are illustrative, to show how the method works — not a valuation or a guarantee. Your numbers and timeline depend on your situation.
Quick answer
What is a financial maturity assessment — and does it actually help?
A financial maturity assessment scores how developed your business's financial function is — across areas like your books, your processes, and your strategy — and places you on a ladder from Chaos (unreliable numbers) up to Strategy(forward-looking decision support). It's a useful mirror.
But a score on its own is a horoscope. What makes it actually move a business is what comes next: a sequenced action plan that fixes the few gaps costing you the most — weakest link first — and someone in your corner holding you accountable until it sticks. That's the whole argument of this piece. You can see your own starting point with our free financial maturity assessment.
The assessment everyone's selling — and why most change nothing
Picture the owner of a $20 million commercial GC — call them Summit Builders. They take an online “financial health” quiz, get a score, and a sales rep books a call. The score feels accurate. It names the pain. And then… nothing. No plan tied to what Summit is actually trying to do. No next step beyond “book a demo.” Six months later the books are still late, cash is still a white-knuckle ride, and the owner is still the only person who knows how anything works.
That's the trap. A maturity score has become a lead-gen gimmick — a number designed to make you feel a problem, not to solve one. The assessment is the easy part. Anyone can hand you a grade. What's rare — and what actually changes a business — is everything that comes after the grade.
What a maturity assessment actually measures
Strip away the buzzwords and a good assessment does something simple: it scores how developed your financial function is, area by area, and places you on a ladder. We use four rungs — the Financial Maturity Ladder:
Numbers are late or wrong. You run on gut and the bank balance.
Books get done, mostly for taxes. Accurate, but backward-looking.
Timely, trustworthy reporting and a real financial rhythm.
Numbers drive forecasting, pricing, growth, and exit decisions.
Underneath the single rung is the useful detail: a score in each area — your financials, your processes, your strategy. Summit Builders lands on Rung 1, Chaos. Fine. Now what? That “now what” is where almost every assessment quietly checks out — and where the real work starts. Curious where you'd land? Take the 8-question assessment — it's free and takes about two minutes.
Why the score alone is worthless
A number with no plan behind it is a horoscope — it feels insightful and asks nothing of you. “You're a Rung 1” is about as actionable as “Mercury is in retrograde.” It doesn't tell you what to fix first, what it's costing you to leave it, or how the pieces connect. Worse, a score can make you feel like you've done something, when all you've done is confirm what you already suspected at 2 a.m.
The value was never in the diagnosis. It's in the prescription — and in whether anyone makes sure you take it.
Truth #1: You can't fix everything at once — so fix the weakest link first
Here's the part the quizzes never get to. Maturity is almost never even across a business. One area limps along while another is genuinely solid. When we score Summit Builders area by area, it looks like this:
Summit Builders — maturity by area (illustrative, 0–5)
Summit's instinct is to go after strategy — the fun stuff, the growth plan. But its financials are the weakest link, and the weakest link caps everything above it. Building a growth strategy on books you can't trust is tuning the engine on a car with a flat tire. The right move is to bring the weak area up to parity first, then move the whole business up together. Sun Tzu's version: concentrate your force on the decisive point instead of spreading it thin across the whole front. The practical version, from thirty years of fixing processes: don't boil the ocean — start where the leak is.
Truth #2: The cost of waiting is real money
“We'll get to it” isn't free. Every month those gaps stay open, they quietly bleed the business — margin left on the table because nobody's watching job costs, cash collected 30 days later than it should be, risk you're carrying without knowing it. A real assessment puts a number on that, scaled to your revenue.
Illustrative cost of waiting — a $20M GC stuck at Rung 1
$150K–$400K / yr
in margin leakage, late cash, and avoidable risk — the gap between running on Rung 1 and Rung 2. Closing it isn't a cost. It's the return on the work.
That reframes the whole conversation. The question isn't “can I afford to fix this?” It's “how much longer can I afford not to?”
What a real plan looks like: 90-day cycles, built with you
A plan isn't a 40-item to-do list that lands in your inbox and dies. It's built in 90-day cycles — small, concrete steps that compound — and it's sequenced so each step sets up the next. The climb from Chaos to Control, rung by rung, looks like this:
Chaos to Compliance
Clean up the books, repair the AR/AP process, get payroll compliant, stand up basic monthly reporting.
Bookkeeping →Compliance to Control
Document the core SOPs, set a financial close calendar, build cash forecasting, reduce owner dependency.
Controller →Control to Strategy
Margin analysis, budgeting, a KPI dashboard, capital-access strategy, real forecasting.
Fractional CFO →Notice the plan maps straight onto the work: a bookkeeper gets the numbers right, a controller makes them reliable and builds the rhythm, and a fractional CFO decides what to do with them. You don't jump to the top — you graduate to it. And the detailed 30/60/90 isn't handed down from on high; it's built with you in the first working session, because a plan you helped write is a plan you'll actually run.
The part nobody tells you: a plan you're handed almost never happens
Here's the uncomfortable truth after years of this work. The plan is maybe 30% of the outcome. The other 70% is whether anyone makes sure it actually gets done. Hand a busy owner a brilliant plan and walk away, and the day-to-day will win every single time — not because they're lazy or incapable, but because the urgent always crowds out the important. A document in a drawer changes nothing.
Handed a plan, left alone
- • A report you read once and file away
- • No one checking whether step two happened
- • The urgent crowds out the important — every week
- • Six months later, same rung, more guilt
A partner in your corner
- • Someone who reviews progress on a cadence
- • Holds you accountable to what you committed to
- • Cheerleads the wins and adjusts when life happens
- • Twelve months later, a rung higher — for real
This is the whole difference between knowing what to do and actually doing it. A good consultant isn't just an analyst; they're a coach who's in it with you — part strategist, part accountability partner, part cheerleader. That's not a soft add-on. It's the mechanism that turns a plan into results, and it's the thing a downloadable quiz can never give you.
What this looks like for a real business
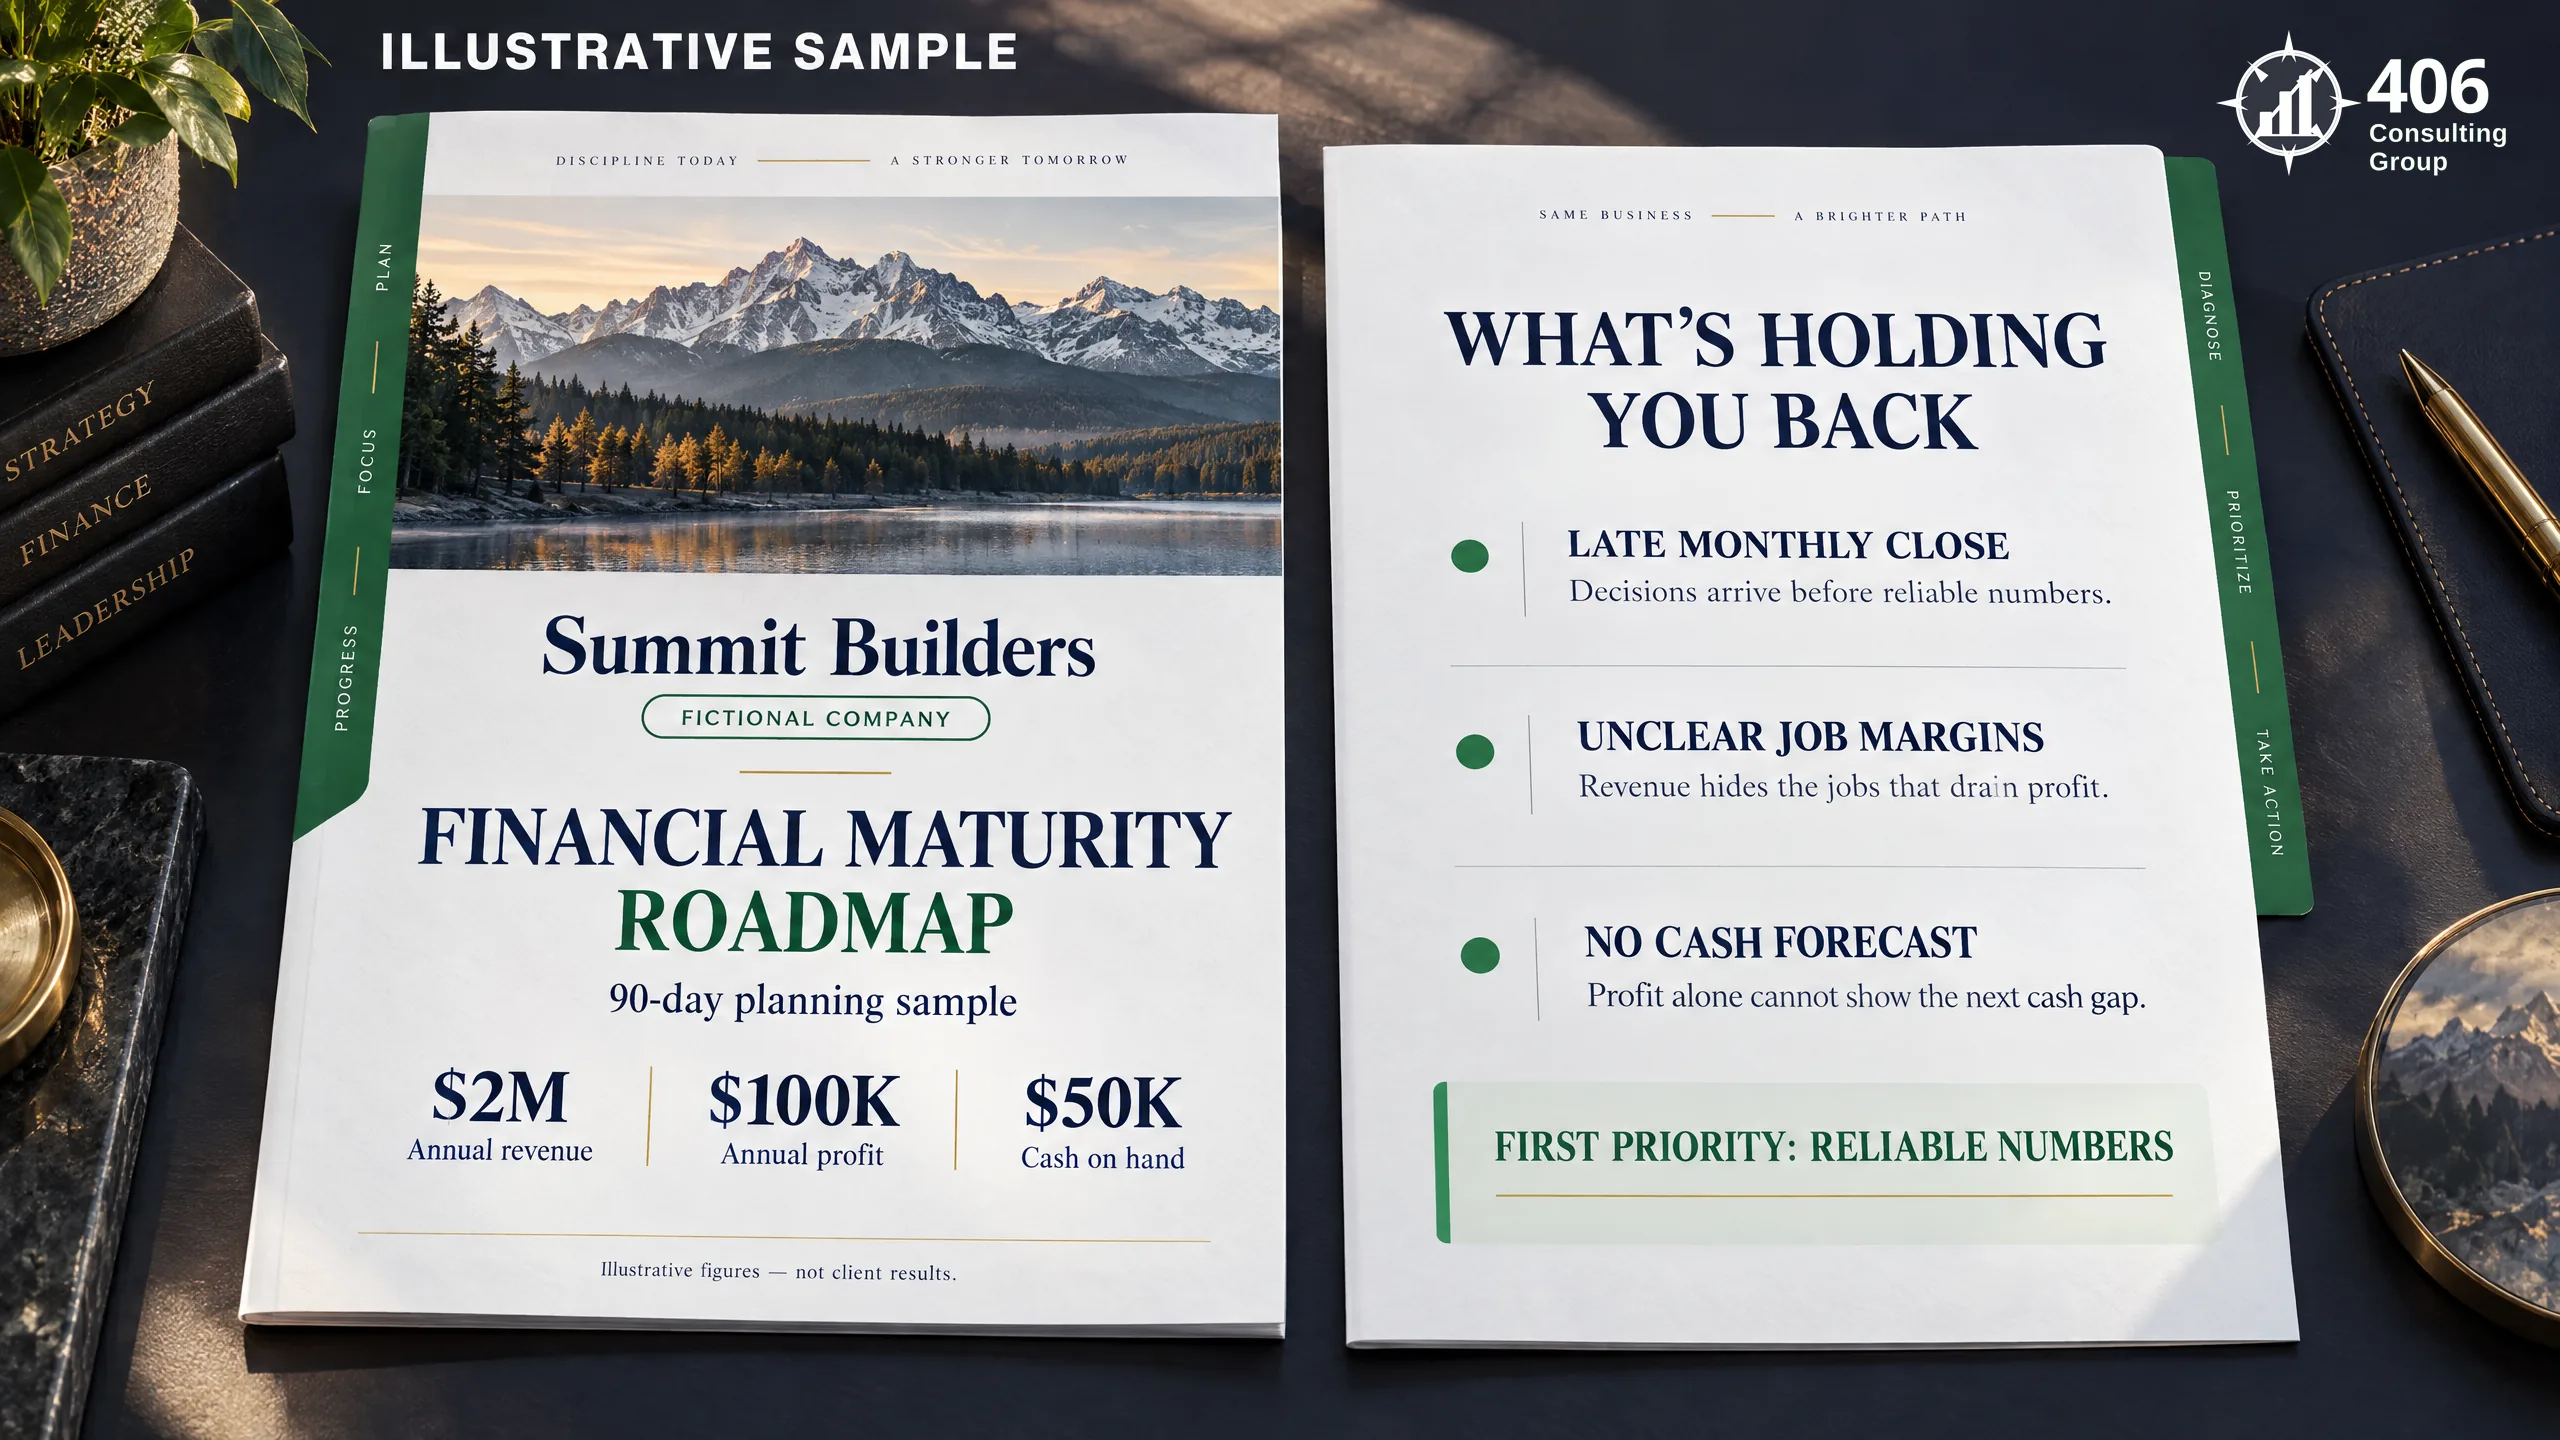
Back to Summit Builders. Their weakest link is financial, and the sharpest symptom is billing: invoicing is a monthly scramble with no real process and no one accountable for it, so draws go out late and cash always lags payroll. That one broken process is dragging the whole rung down. (We go deep on that exact fix in the construction invoicing scramble, and on the industry specifics in our work with general contractors.)
So the first 90 days don't try to boil the ocean. They target the leak: a standardized billing and WIP cadence, one owner of the process, and a weekly cash rhythm — supported by tools like a job-costing calculator and a cash-flow runway model. Clean books follow. Then reliable reporting. Then — and only then — the growth strategy the owner wanted on day one, now built on numbers that are actually true. Each 90 days, we review together, hold the line, and set the next sprint. That's how a Rung 1 becomes a Rung 2, and a business that depends on the owner for everything becomes one that could actually run — or sell — without them.
Where to start
The score is the easy part — so get it, for free, and treat it as the opening move, not the answer. Then do the two things that actually move the needle: fix your weakest link first, and put someone in your corner who won't let the plan die in a drawer.
See where you stand — then let's build the plan together.
Take the free Financial Maturity Assessment to find your rung and your weakest link. Then talk to a founder about a sequenced, 90-day plan — and a partner who'll hold you to it.
Who You’re Actually Working With
Two founders who’ve sat on both sides of your financials
A score tells you where you are; a partner who's operated businesses and built the processes gets you where you're going. You aren’t handed off to a junior bookkeeper. You work directly with the people whose names are on the door — and their backgrounds are exactly the ones a growing business needs in its corner.
Carrie Anderson
Co-Founder · The Lender’s Eye
A former corporate controller and the contracted commercial loan analysta Montana community bank relies on — she has spread, packaged, and recommended 300+ commercial loans. She knows exactly how a bank reads your financials to decide what you can borrow — because she’s the one doing that analysis. That’s why our clients’ books come out lender-ready, not just tax-ready.
Jason Anderson
Co-Founder · The Operator’s Eye
A degreed accountant with 10+ years in tax and a decade of enterprise operations and accounting at BP, with a lifelong discipline for process, efficiency, and Six Sigma— made practical, not academic. He builds the job costing, tax strategy, and systems that let a company actually see where its money goes and scale without the wheels coming off.
Both spent years in the oil & gas industry, and both design financial systems from a whole-company view— not just an accounting lens. You get a firm that reads your numbers like a lender and builds systems like an operator.
Meet the teamFAQ
What is a financial maturity assessment?
A financial maturity assessment scores how developed your business's financial function is — across areas like your books, your processes, and your strategy — and places you on a ladder from Chaos (unreliable numbers) up to Strategy (forward-looking decision support). The useful ones don't stop at a score: they identify the few gaps costing you the most and lay out a sequenced plan to close them.
Is a maturity assessment just a sales gimmick?
It can be, if it ends at a score and a pitch. A score by itself is a horoscope — it feels insightful and asks nothing of you. What makes it worth anything is what comes next: a prioritized, sequenced action plan tied to your goals, and someone who helps you actually execute it. The assessment is the opening move, not the product.
Why fix the weakest area first instead of everything at once?
Because your weakest area caps everything above it. Polishing a strong function while a weak one leaks cash is wasted effort — like tuning the engine on a car with a flat tire. Bringing the weakest link up to parity first is what lets the whole business move up together, which is why a good plan is sequenced, not a 40-item to-do list.
How long does it take to move up a maturity level?
For most small and mid-sized businesses, moving up one rung is a 9–12 month effort, built in 90-day cycles of small, concrete steps. The timeline depends on how deep the gaps are and — more than anything — on whether the plan actually gets executed, which is where an accountability partner makes the biggest difference.
Why can't I just follow the plan myself?
You can, and some owners do. But a plan you're handed and left to execute alone almost never gets done — not because you're not capable, but because the day-to-day always wins. A partner who reviews progress, holds you accountable, and adjusts the plan turns a document into results. That's the difference between knowing what to do and actually doing it.
This article is general financial and operational education, not accounting, tax, legal, or investment advice for your specific situation. The example business and all figures are illustrative. Your results depend on your numbers, your goals, and the work you put in.
In one line
A maturity score is the easy part. What changes a business is a sequenced plan that fixes the weakest link first — and a partner who holds you accountable to it.
Start here