
SDE vs. Real Cash Flow:
The Owner-Replacement Trap in Buying a Business
A seller's memo says $500K in cash flow. Subtract the real cost to replace the owner — usually more than one hire — and the SBA math changes fast. Here's how to find the true number before you sign.
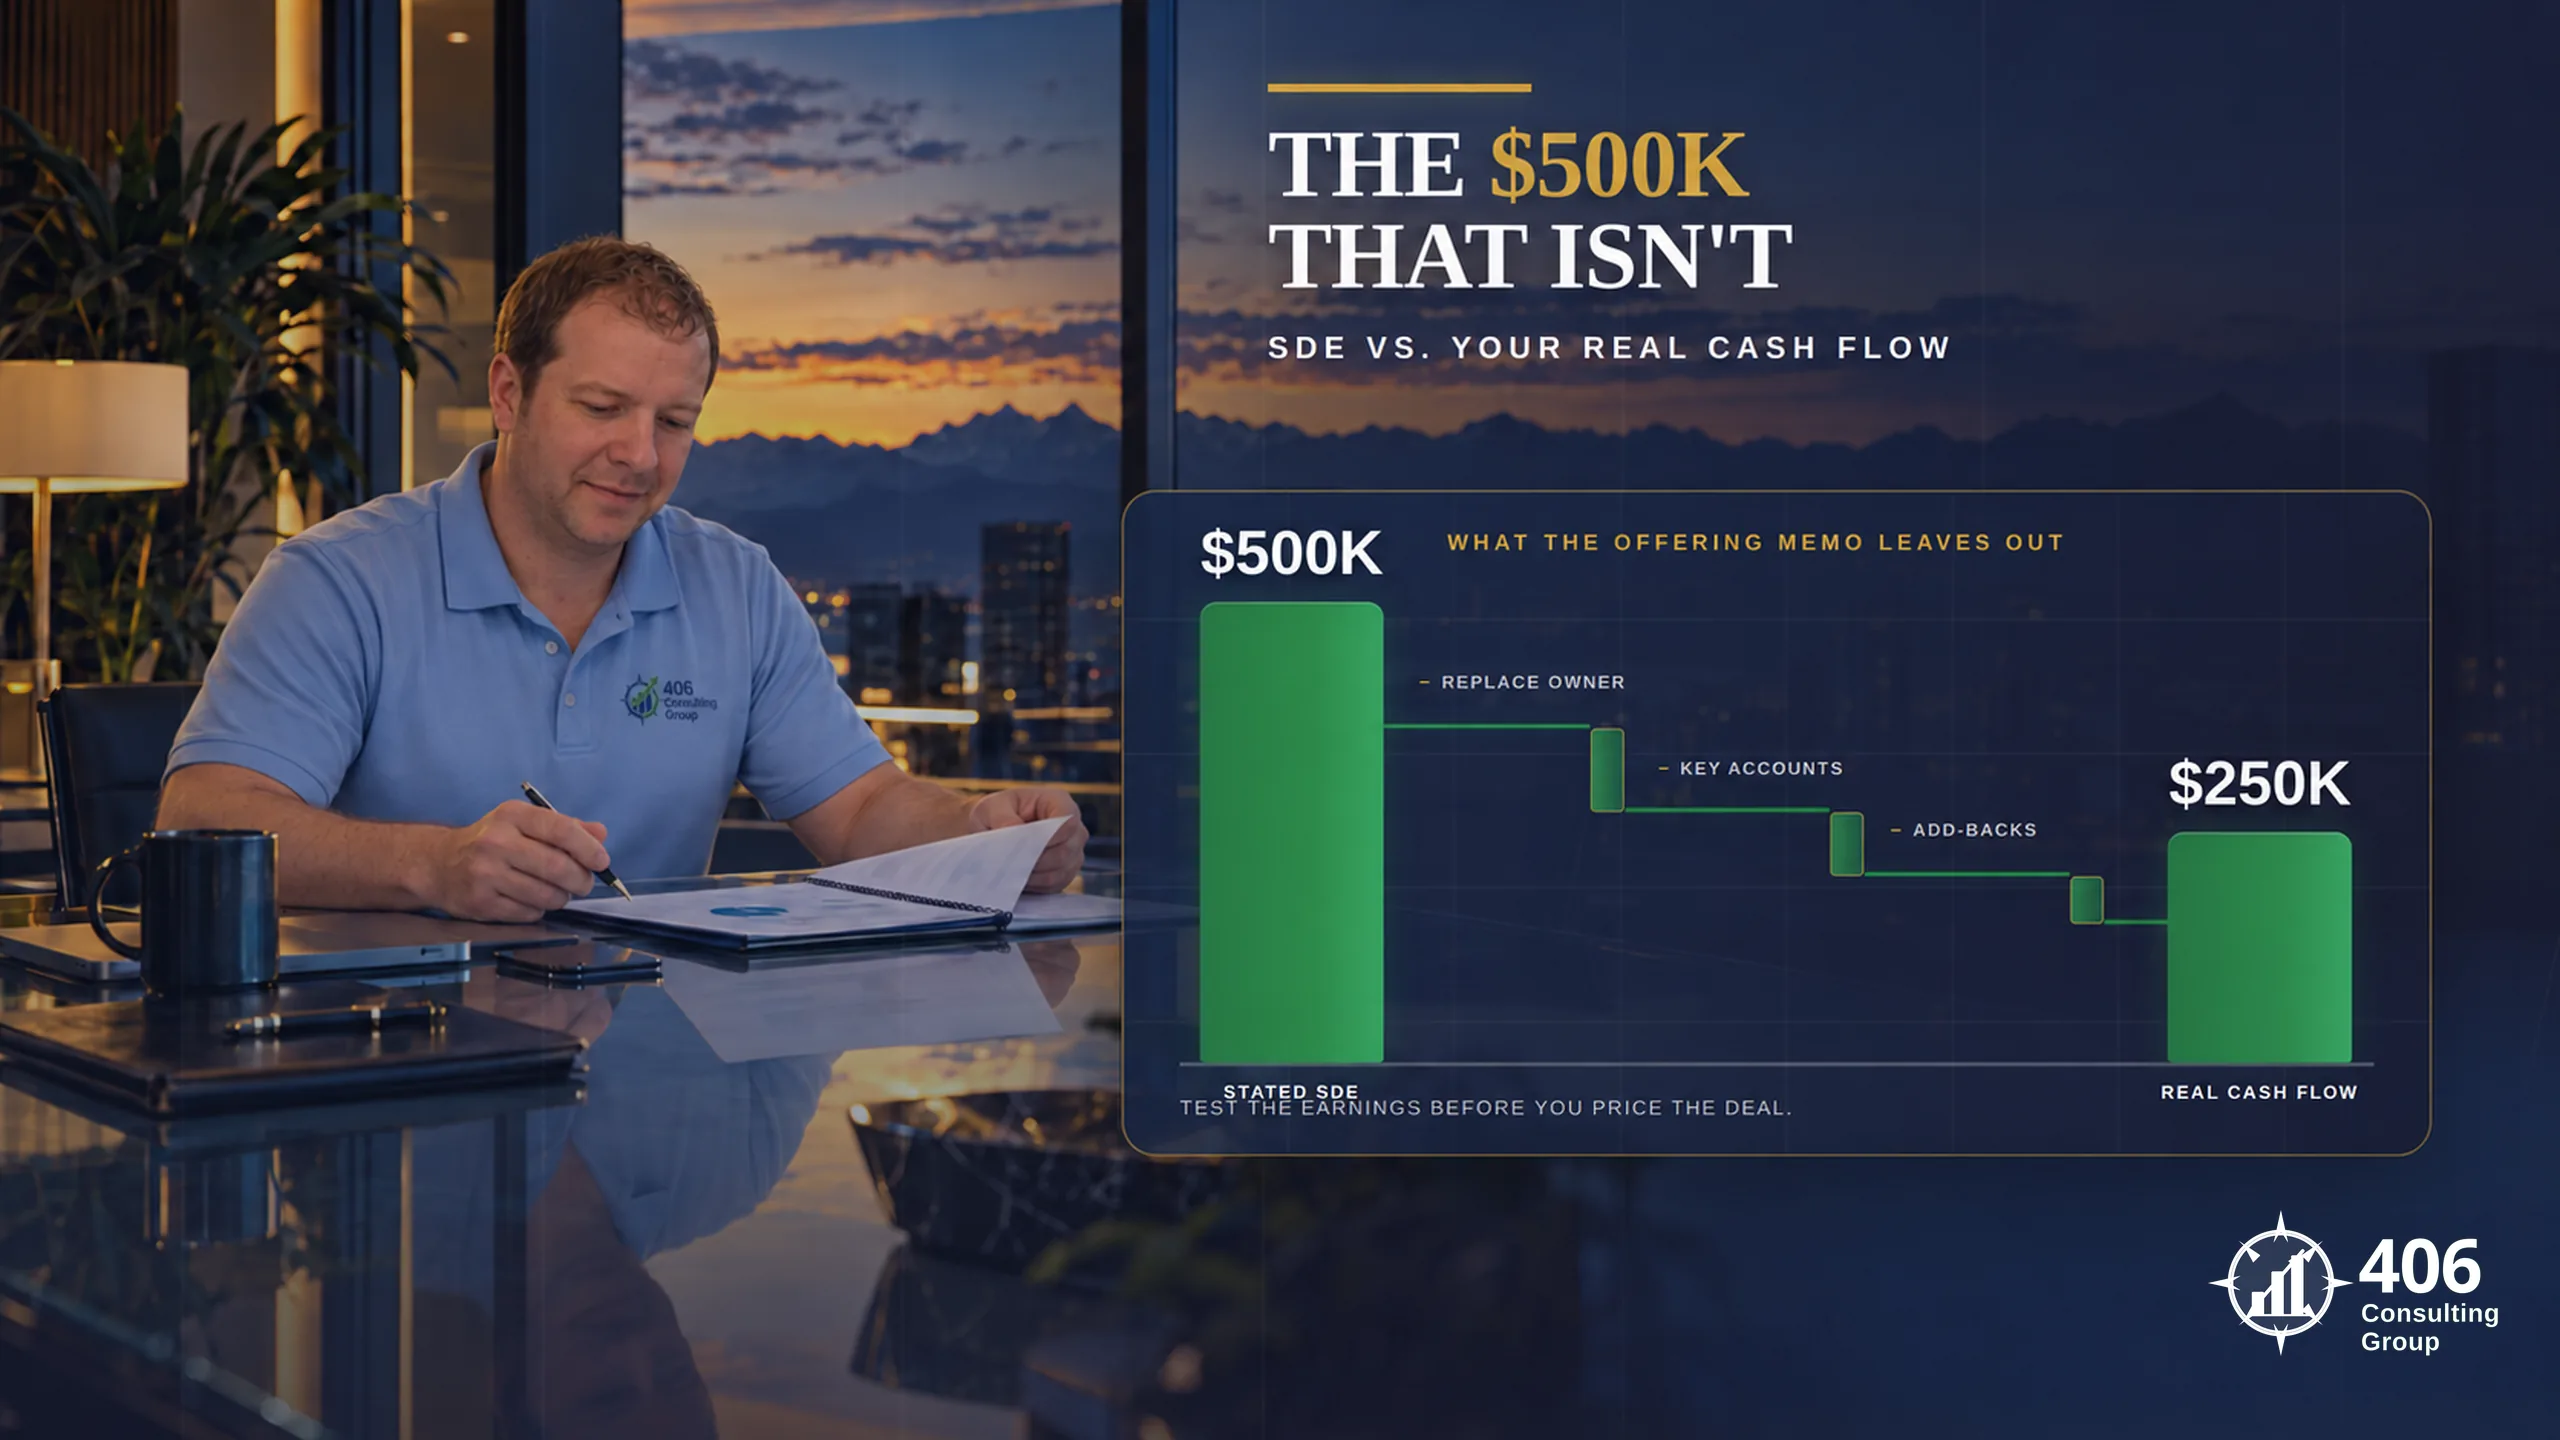
You're looking at a business for sale, and the offering memo says it throws off $500,000 a year in “cash flow.” The broker says it practically runs itself. The bank's early read looks great. And then you do the one calculation almost nobody on the sell side wants you to do — you subtract what it will actually cost to replace the owner— and the real number is nowhere near $500,000. Get this wrong and you overpay, your lender's math quietly falls apart, and you spend year one discovering you bought a job, not a business. Get it right and you walk into the deal knowing exactly what you're buying, and why.
By Jason Anderson
Co-Founder, 406 Consulting Group
Big-firm tax background with a Six Sigma discipline for systems and job costing.
The figures below are illustrative, to show how the math works — not a valuation, a guarantee, or lending advice. Deal terms, lender thresholds, and SBA rules vary and change. Confirm specifics with your advisor and lender.
The short version
- →A seller's “cash flow” is almost always SDE — seller's discretionary earnings — which adds the owner's pay and perks back in.
- →To find your cash flow, subtract the real cost to replace the owner — and that's usually more than one hire, because the owner did several jobs at once.
- →On an SBA acquisition loan, you supply the projections, and the lender tests debt service after a realistic owner/manager salary. Overstate it and the deal doesn't work — or gets caught.
- →The DSCR that looked bankable on the seller's number can fall below the line on the real one. That's the whole game.
What a CIM calls “cash flow” is usually SDE
When a broker markets a business, the headline number in the CIM (the confidential information memorandum, sometimes called a “SIM”) is typically seller's discretionary earnings. SDE starts with the company's profit and then adds back everything that was really a benefit to the current owner or a one-time event: the owner's salary, their health insurance and vehicle, a spouse on payroll, interest, taxes, depreciation, and any one-off costs that supposedly won't repeat. It's a legitimate way to show what the business earns before the owner's personal choices — but it describes their situation, not yours.
Here's the catch every first-time buyer misses: the single biggest add-back is usually the owner's own compensation. SDE pretends the owner works for free. You won't. Either you take a salary for doing their job, or you hire people to do it — and that cost comes straight back out of the number.
Net profit on the tax return
The honest floor — what the business actually reported
+ Owner's salary & perks
Added back — the seller's pay, insurance, vehicle, travel
+ Interest, taxes, depreciation
Added back — financing and accounting choices
+ One-time / non-recurring costs
Added back — a lawsuit, a move, a bad year (if true)
= SDE (the CIM headline)
The number the asking price is built on
The trap: you're not replacing one job
Picture Big Sky Supply, a Montana distributor on the market for a $500,000 SDE. Talk to the seller for an hour and you learn what they actually did: they ran operations, they were the top salesperson and held the three biggest accounts personally, and they signed off on all the finances. Sixty-hour weeks, three jobs in one person. That's not unusual — it's the norm in owner-operated businesses, and it's exactly why the business looks so profitable. The owner is doing the work of a small team for free, on paper.
To replace that, you rarely hire one person. You hire a general manager to run it and someone to hold the customer relationships so revenue doesn't walk out the door with the seller. The cost to replace an owner is frequently more than buyers expect — often two or three roles, not one. And every dollar of that cost comes out of the $500,000.
The riskiest add-back is the owner who is the sales team. If the biggest accounts are loyal to a person, not the company, replacing them isn't just a salary line — it's a revenue risk. A good analysis prices both.
The waterfall: $500K SDE to real cash flow
Here's the move that turns a seller's number into your number. Start at the SDE, subtract the real cost to replace the owner and the add-backs that won't actually recur for you, and watch where it lands.
Big Sky Supply — SDE to buyer's cash flow
IllustrativeStated SDE (the CIM headline)
$500,000
Replace the owner as general manager
−$120,000
Replace the owner's sales / key accounts
−$80,000
Strip one-time add-backs that won't recur
−$30,000
Normalize owner perks run through the business
−$20,000
Real cash flow to you, the buyer
$250,000
The asking price was built on $500,000. The business actually hands the next owner about $250,000 — half. Every number here is illustrative; your real figures come from market pay rates for the owner's roles and a line-by-line look at the add-backs.
How to price the owner's job: the reasonable-salary move
So how do you put a real number on “replace the owner”? You price their roles at market — what it would genuinely cost to hire someone to do each job the owner does. This is the same discipline the IRS uses to test an S-corp owner's reasonable salary: what would the open market pay a person to do this work? If you've ever had to defend an owner's pay on a tax return, you already know the muscle — here you're just running it in reverse, to value a business instead of a paycheck.
Our S-corp reasonable-salary calculator is a fast way to ballpark market pay for an owner's role — the exact number you subtract from SDE. Use it to sanity-check the replacement cost before you ever make an offer, then read how reasonable salary is actually set.
Why the SBA tests this — and will catch it
This isn't just a smart-buyer exercise. If you're financing the purchase with an SBA 7(a) acquisition loan, the replacement-cost math is baked into whether the loan gets approved at all — and here's the part first-time buyers don't expect: you supply the projections. The seller's historical numbers get you in the door, but the lender underwrites the business as you'll run it, and that means debt service is tested after a realistic owner or manager salary is in the model.
In plain terms: the bank will not let you pretend you work for free either. They'll pencil in a market salary for whoever runs the business — you or a hire — and then ask whether what's left still covers the loan payment with room to spare. A projection that quietly assumes the owner's $120,000 role costs nothing is the fastest way to a “no,” or worse, an approval on numbers that don't survive contact with reality.
From the underwriter's chair: having reviewed hundreds of loan files, Carrie's read is simple — the projections that get approved are the ones that already subtract a real salary and still work. An underwriter's job is to find the salary you left out. Hand them a file that's already honest about it, and you've removed their biggest reason to say no. That's the difference between a buyer who looks prepared and one who looks like a risk.
The kicker: the DSCR that looked bankable until it wasn't
Now watch what happens to the one ratio the whole loan hinges on. Lenders size an acquisition loan off debt-service-coverage ratio (DSCR) — cash flow divided by the loan payment. Most want to see at least about 1.15 to 1.25 on an SBA deal. Say the purchase is financed with roughly $260,000 a year in debt service. Here's the same deal, run on the seller's number and then on the real one.
On the seller's SDE
1.9
DSCR · $500K ÷ ~$260K
On real cash flow
0.96
DSCR · $250K ÷ ~$260K
Same business, same price, same loan — and the deal goes from “slam dunk” to “declined.” A DSCR under 1.0 says the cash flow literally can't make the payment once you're paid like a human. That doesn't always kill the deal, but it changes it: a bigger down payment, a lower price, a seller note put on standby, or walking away. The point is you want to know before you're at the closing table — not after. (For the full mechanics, see how much a business can actually borrow.)
One shot with the bank
Here's why getting this right the first time matters so much: on an acquisition loan, you often get one real look. A projection that falls apart under the lender's salary adjustment doesn't just cost you that bank — it costs you weeks of momentum while a seller's patience, and sometimes the deal, runs out. A package that already frames cash flow and DSCR the way an underwriter reads them lands clean the first time. (More on building that file: what lenders want to see, and SBA vs. USDA if the business is rural.)
This is the work a bookkeeper can't do
None of this shows up in the books. A bookkeeper records what already happened — faithfully, and that matters. But recasting SDE, pricing owner replacement across multiple roles, building a defensible projection, and pressure-testing DSCR for a deal that doesn't exist yet is forward-looking analysis. It's CFO-level work, and it's exactly the rung of the financial maturity ladder where recording the past gives way to shaping the future.
Record what already happened
Recast SDE into buyer's real cash flow
Price owner replacement across roles
Build the SBA projection you must supply
Pressure-test DSCR before you sign
What to do before you sign
- Ask whether the headline number is SDE, and get the add-back schedule line by line.
- List every hat the owner wears, then price each role at market — assume more than one hire.
- Rebuild the cash flow after a real owner/manager salary. That's your number, not the seller's.
- Run DSCR on the real number against the actual loan payment — before you make an offer.
- Separate add-backs that truly won't recur from ones you'll keep paying.
Looking at a business to buy?
We'll recast the seller's numbers into your real cash flow, price the owner's replacement honestly, and build the SBA projection the way an underwriter reads it — from a team that has operated businesses and underwritten the loans. Know what you're buying before you sign.
Who You’re Actually Working With
Two founders who’ve sat on both sides of your financials
When you're buying a business, the team reading the numbers matters as much as the numbers. You aren’t handed off to a junior bookkeeper. You work directly with the people whose names are on the door — and their backgrounds are exactly the ones a growing business needs in its corner.
Carrie Anderson
Co-Founder · The Lender’s Eye
A former commercial banker and underwriter who personally reviewed 300+ business loans. She knows exactly how a bank reads your financials to decide what you can borrow — because she used to be the one reading them. That’s why our clients’ books come out lender-ready, not just tax-ready.
Jason Anderson
Co-Founder · The Operator’s Eye
A big-firm-trained accountant with a lifelong passion for processes, efficiency, and Six Sigma— made practical, not academic. He builds the job costing, tax strategy, and systems that let a company actually see where its money goes and scale without the wheels coming off.
Both spent years in the oil & gas industry, and both design financial systems from a whole-company view— not just an accounting lens. You get a firm that reads your numbers like a lender and builds systems like an operator.
Meet the teamFAQ
What is SDE (seller's discretionary earnings)?
SDE is a business's profit with the owner's pay and personal benefits added back in — salary, health insurance, a vehicle, a spouse on payroll — plus interest, taxes, depreciation, and genuine one-time costs. It's the standard headline number in a business-for-sale listing because it shows what the business earns before the current owner's personal choices. The catch: it assumes the owner works for free, so it describes the seller's situation, not what the next owner will actually take home.
Is a seller's 'cash flow' the same as profit?
No. The 'cash flow' quoted in a CIM is almost always SDE, which is higher than the net profit on the tax return because it adds back the owner's compensation and other items. Real cash flow to a buyer is lower still — you have to subtract what it costs to replace the owner's work. It's common for the buyer's true cash flow to land well below the marketed SDE once a realistic salary is put back in.
How much does it cost to replace a business owner?
More than most buyers expect, because owners usually do several jobs at once — running operations, selling and holding key accounts, and overseeing finances. Replacing them is frequently two or three roles, not one, and the right way to size it is to price each role at market pay. The total is what you subtract from SDE to find your real cash flow, so it directly affects both what the business is worth and whether a loan will cover.
Will an SBA lender accept the seller's numbers?
They'll use the seller's history as a starting point, but on an acquisition loan you supply the projections, and the lender underwrites the business as you'll run it — which means they test debt service after a realistic owner or manager salary. A projection that assumes the owner's role costs nothing won't survive underwriting. Building the file with a real salary already in it is the single biggest thing in your control.
Can a bookkeeper help me evaluate a business acquisition?
A bookkeeper records what already happened, which is valuable but backward-looking. Recasting SDE, pricing owner replacement, building the projection the SBA requires, and pressure-testing DSCR for a deal that doesn't exist yet is forward-looking, CFO-level analysis. It's a different skill set — the kind of financial leadership that keeps a buyer from overpaying or getting caught by the lender's math.
This article is general financial education, not lending, tax, legal, or valuation advice for your specific situation. All figures are illustrative. SBA program terms and lender thresholds change; confirm current details with a lender and your advisor before relying on any number here.
In one line
A seller's “$500K cash flow” is SDE. Subtract the real cost to replace the owner — usually more than one hire — and the true number, and the DSCR, can look very different.
Run the numbers
Keep Reading
External Resource
SBA 7(a) Loan Program